Small Cap Value Report (10 Jun 2014) - CML, GTC, MMX, VNET

Good morning!
CML Microsystems (LON:CML)
This is a small semiconductor designer & manufacturer. It's not an industry I understand at all, so that's why I've not looked in detail at this company before in these reports. The reason for mentioning it today is that preliminary results for the year ended 31 Mar 2014 have been issued, and this has triggered a 21% fall in share price to 430p, so commisserations to holders of these shares.
Growth seems to have ground to a halt, with turnover down a whisker at £24.4m, and profit before tax up 6% to £5.8m (note that's an excellent profit margin at 23.8%). Basic EPS is 30p, so the PER works out at 14.3, which seems a reasonable rating for a technology company (which tend to be highly rated).
The fly in the ointment is the forward-looking comments, which are cautious;
The Company was able to deliver on market expectations for a firm full year improvement in profitability although, as evidenced through the period under review, it was record first half revenues and profits that drove performance. Second half sales were affected by the previously explained and unforeseen customer events within storage markets and this, coupled with the cyclical volatility from wireless, created a headwind for revenues that will also impact the current year. In reporting on a year when we have delivered record profits, it is disappointing to now convey short-term caution but, beyond this year, the board is confident of delivering a return to revenue growth.
I'm not sure how to interpret that. It doesn't sound like temporary factors, if H2 was soft, and the current year is also expected to be soft. That sounds more like competitive issues perhaps? I wonder whether the high profit margins are sustainable, given that demand has softened?
Note that the company has some surplus land that it is trying to monetise by getting planning permission for a residential development. The Balance Sheet is very strong indeed, with £16.2m in current assets, versus £2.8m in current liabilities - so that's 579%, one of the strongest working capital ratios I've seen for a while! That includes £11.4m in cash too. Inventories look very tight, at just £1.1m, which is generally a good thing, providing they have enough to service demand.
There is a pension deficit though, which has shrunk from £6.1m to £2.7m, which would be worth checking in more detail in the Annual Report.
It's worth noting that profit is partially helped by them capitalising £4.1m in development costs, although the amortisation charge was fairly hefty at £2.6m. Therefore arguably, if you were being super-conservative, you could argue that profit should be marked down by the difference there of £1.5m to adjust out capitalisation of development costs, which is my preferred way of viewing accounts.
There's a small, but well covered dividend.
Overall, there are a lot of things I like in these figures. So it would be worth considering these shares, in my opinion, if you think that they can kickstart growth again. It would probably be worth talking to people in the industry, and ask about CML's products, and how they stack up against competitors. Is it yesterday's story, or is it a fundamentally good company that has just hit a temporary soft patch? I don't know.
Getech (LON:GTC)
This micro cap is a provider of geological data to oil exploration companies. Shareholders are having a tough year, as the company warned on profit on 17 Feb 2014, and interim results to 31 Jan 2014 were very poor (profit fell by 83% against last year's H1).
I've been pretty sceptical about this company in my reports here, and so far that's proven correct. Today the company has issued another profit warning, with the main part explaining as follows;
The Company has now built what it regards to be a very strong sales pipeline including close to £2m of leads where clients have recently given written or oral confirmation that they intend to proceed. We are therefore confident that a number of significant contracts, including several Globe renewals, will be signed in the very near future. However, with the expected cycle time to convert the sales pipeline into contracts and then revenue, the Directors believe that the Company will deliver pre-tax profit for the 12 month period to 31 July 2014 which is significantly below the market expectation.
The market cap has now fallen to about £12.4m, at 41.5p per share. It all boils down to whether you believe that the orders will come through, and are just delayed, or whether that's just the excuse that's being given for failing to deliver the expected improvement needed in H2.
I remember saying back at the time of the earlier profit warning, that the forecasts were now so heavily weighted to H2 that another profit warning was likely, as that's exactly what's happened. You see this happening time & time again when companies miss H1, but say they will recoup it in H2 - all too often it's wishful thinking, and just delaying another profit warning.
It seems to me that Getech is just too difficult to forecast accurately, as they rely on lumpy contracts with uncertain timing. That said, with the market cap down to £12m, the market isn't expecting a lot from the company. So if they can turn the order pipeline into sales, then the figures start to look better in H1 of the new financial year beginning on 1 August (as they will be up against very soft comparatives).
Tricky one. My instincts say this share could fall further, but I've picked up a small amount of stock this morning to dip my toe in the water. I'm interested to hear reader opinions on this one, so please comment away in the comments below.
Minds + Machines (LON:MMX)
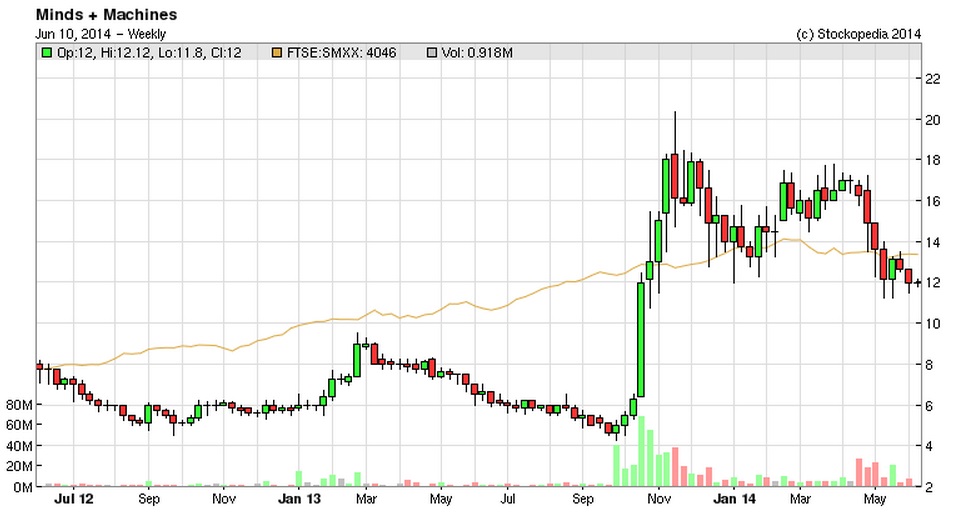
I'm going to risk incurring the wrath of the strident private shareholders in this company by repeating my previous concerns that they seem to be pursuing a business model which, in my opinion, probably has little merit. It's alll to do with new domain names being issued with suffixes like .london, .cooking, .horse, etc.
This company today says;
We believe that we are at the start of a very significant new trend in the entire Internet, where small businesses and individuals will over time dramatically increase the amount of names they use online, and do so with far greater ease.
Very few people I've spoken to agree with this. The point is that nobody needs to remember domain names any more. You just put the company name into Google, and it takes you to the company's website. The domain name is irrelevant.
They're a funny set of figures for a £99m market cap company, the very late audited results for the year ended 31 Dec 2013, published today.
Turnover is only £36k! The company would have incurred a loss of about £2.8m, however a large credit of £4.1m has gone through the P&L described as "Profit on gTLD auctions". See if you can make any sense of the relevant part of note 17 which covers this issue, as I can't:
Of the applications withdrawn, 3 applications were withdrawn as a result of participation in private auction where the Group did not win the auction but received a portion of the auction proceeds. Such auction proceeds, less amounts not recovered from the Group's withdrawal of the application to ICANN are accounted for on the profit and loss account as Profit on participation in gTLD auctions and amounted to £4,120k (2012: nil). The remaining applications were withdrawn based on management's assessment of success of the application of those gTLDs. Of the application fee, those amounts not recovered from ICANN as a result of the Group's withdrawal of the application are accounted for on the profit and loss account as Loss on withdrawal of gTLD applications and amounted to £253k (2012: nil).
That's total gobbledygook to me.
The company has plenty of cash, which was reported at £21.7m ay 30 Apr 2014, following an equity raise in Jan 2014. It looks as if the domain names were not launched until after the year end, so that's probably why there is negligible turnover. The company says it will spend all the cash by the end of 2014 buying the rights to issue new domain names with the new suffixes.
I can see that some businesses might pre-emptively register domain names, so hotels & restaurants, etc, might register domains such as Savoy.london, etc, and then point them at their existing websites. On the other hand, why bother, given that anyone can just Google "savoy hotel" and go straight to their website already? Surely this company is inventing a solution to a problem that doesn't exist?
Anyway, we'll see if it works. The shares are really just for gamblers in my view. Personally until the model is proven, I wouldn't pay more than cash, so about a fifth of the current share price.
Vianet (LON:VNET)
Final results for the year ended 31 Mar 2014 have been issued today, and look OK to me, so am a little surprised that the shares are down 4p to 78p this morning.
The core (and most profitable, by far) business is the beer flow monitoring equipment for tied pubs. Whilst this is a profitable niche, it is also up against a headwind of pub closures, probably worsened by the recent Government statutory code - which was designed to help financially struggling tenants, but probably accelerated the closure of pubs by brewery groups, by introducing more uncertainty.
It's encouraging to see that the vending telemetrics division has moved into a modest profit of £0.35m, so the company seems to (at last) be gaining some traction there.
From an investor's point of view the dividend is the main attraction, at 5.7p per share. That's a very generous yield of 7.3%, but the way I read the figures, it looks like the company is struggling to maintain that level of dividend, so at some point it might well be reduced.
It's difficult to use an EPS figure, as this is distorted by a tax credit to the P&L.
I'll go through the results in more detail later today, but on an initial skim there don't seem to be any nasty surprises there, and in what must have been a very difficult year, the company seems to have weathered the storm over the Statutory Code pretty well.
There is a results presentation online here.
That's all I've got time for today.
Regards, Paul.
(of the companies mentioned today, Paul has long positions in VNET and GTC, and no short positions)
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

28 comments
" .CO (had you heard of it before today)"
Of course, we've heard of it: it's a first generation country code domain, with a full size country behind it (unlike the small island territories ones like .tv .nu etc).
Columbia may be poor but it has nearly 50 million inhabitants, similar size to the UK, and there .co surely plays the role that .uk plays in the UK. It was assigned in 1991 so not surprisingly they have an established customer base, in addition to the global one they've been fishing for more recently.
It's precisely because existing domains like this one own their market that the newfangled ones will have a hard time getting interest.
This discussion has run its course.
Time will tell.
See you when Paul writes his next missive on the subject.
Hi Sue,
Interesting discussion, thanks for your input.
As you suggest, it's all down to delivery now. So let's see what the figures look like in due course, once Minds + Machines (LON:MMX) start trading properly.
Regards, Paul.
Chela
Some very interesting points there.
I currently subscribe to sharelockholmes, which explicitly stores HY results, and also typically updates results by lunchtime on the day of release. So, today with PRES I found myself flipping myself between it and stockopedia to try and get different angles on the data... ...not very successfully.
I am left thinking that the QVM numbers are useful predictors of performance based on last week's webinar, but it probably takes a while before they reflect different-than-expected results and/or (prospective) changes to broker forecasts. That is not to say there is much one can do speed this up.
Still pondering, Martin
Re GTC . I am wary. This is a university spin-out company. A friend worked for a similar venture. When troubles were encountered the reaction was to replace all the experienced businessmen they had brought in with academics. The company was fins up in eighteen months. Unless such companies are Oxbridge products, they seeem not to prosper.This has not fallen far enough yet.
[edit: all director deals in the last year have been sales. Remember SAL!]
Hi Martin
Another relative noob here, so possibly a dumb answer too. I've been pondering similar questions since viewing the StockRanks webinar, wondering how to use the stockranks usefully (especially given that everyone else might be using them too). I must emphasise that I haven't read through
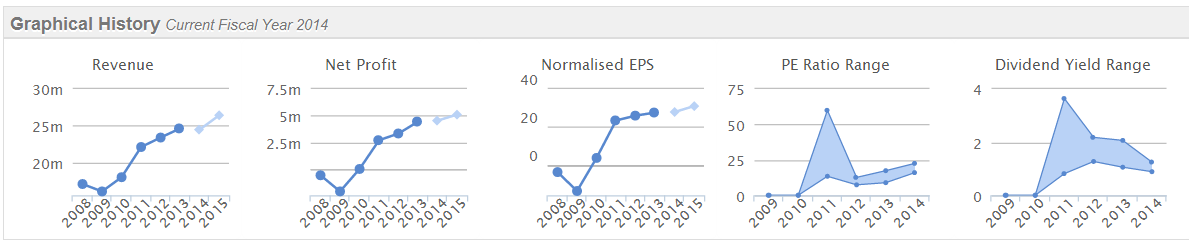
Looking at the report for a share such as CML, hovering the cursor over one of the numbers in the Financial Summary brings up a very useful chart of how each figure (such as Working Capital) has changed over time. Lower down there is a Graphical History (a neat potted summary) of Revenue, Profit, EPS, and ranges for PE and dividend yield. For the basic numbers (revenue, profits, dividends) these show the forecast figures, but not for the more intricate stuff like operating margin or free cash flow.
The traffic-light ratios at the top right of the report for Growth & Value and Quality don't have that same hover-over chart feature, I imagine it would be quite a feat to include it given that the ratios are dependent on the ever-changing price. If I interpret it correctly, the ratios such as PE and yield are based on rolling 12m forecasts, but others such as Price to Book and Return on Capital on a mix of historical and trailing twelve month (TTM) figures.
Until the figures and forecasts are updated (they haven't been yet, as far as I can tell - they only came out today), the only variable which has changed is the price. I haven't got a snapshot from yesterday for comparison, but I imagine that after its 20% drop today the value figures for CML will have improved, and the momentum figures will have worsened, because they reflect the change in price but not any change in such as revenue or earnings.
I guess that this will be reflected in the StockRank (SVM) numbers at the top right - that they have only changed since yesterday based on the change in price, but not the other side of the equations, until the actual figures in the report are updated.
Those StockRank numbers don't have a "hover-over" feature either (that would be nice!). You can however see previous figures by using the print button, which allows you to view a pdf (which opens in a separate window) from previous dates. For CML the earliest is September 2013 (I hope that Stockopedia plan to retain them for longer than that), but the earliest which shows the QVM numbers is November 2013.
Comparing today's report for CML with that for one month ago, May 3 2014, shows V-50 Q-92 M-80, for a combined StockRank of 85. At a price of 572.5p, the forecast PE ratio was 18.2. Today's report (as I write) shows V-54 Q-92 M-52 for a StockRank of 73. So the momentum figure has definitely changed, and it seems that that was the reason for the drop in the overall StockRank. However, at a new price of 421p, the PE ratio is still quite high at 17.3, while the forecast earnings figures between May and today have hardly changed (28p and 31p Norm EPS on both reports), so this leads me to question whether the PE ratio (and other ratios dependent on price) are based not on today's price (as the momentum figure seems to be) but on last night's closing price of 537.5. A drop in price from 572.5 to 537.5 could explain a change in the PE ratio from 18 to 17, but I would have expected a drop to 421p to produce a much larger change - it'll be interesting to have another look tomorrow and see if the Value Rank figure suddenly shoots up, if the financials and forecasts still have not been updated. Indeed, when Paul wrote his report he worked out the PE ratio as 14.3 based on a price of 430p and nearly-unchanged basic EPS of 30p.
There's an article out today about StockRank changes - http://www.stockopedia.com/content/stockranks-upgrades-and-downgrades-june-10th-83874/
Telford homes is the first share discussed, having risen from 80 to 99 in the overall SVM ratings. The results for 31 March have presumably been recently updated - I don't know when, but they were released on the 28th May, nearly 2 weeks ago. The principal reason for the rise in the SVM rating is given as the doubling in operating margins, from 7% to 14%, and the quality rating has shot up to 94 from 65 on the report from the 3rd of May. However on that report EPS was forecast at 23.8, less than the actually reported 25.8 but not hugely so.
The Telford annual report states, amongst the headlines, "Substantial increase in operating margin to 17.1 per cent (2013: 9.7 per cent)". This might be calculated differently by Stockopedia, who give the 2013 figure as 7.4%, but that's nothing compared with the difference between the forecast operating margin of 8.87% (Stock Report 3 May) and the figure of 15% on today's Stock Report.
My conclusion is the oft-repeated DYOR - there's a substantial gap between the releasing of figures by the company and the updating of the Stock Reports, and that the figures should be treated with an extra pinch of salt around reporting time, because the various ratios will probably not yet be "in line". I'm sure I wasn't the only one impressed with the StockRanks webinar, and there will no doubt be plenty who wish to use it mechanically for stock selection - Ed was at pains to point out that doing that wasn't a good idea, and that the StockRankings should only be used as a basis for further research. To catch that rise in operating margin for Telford, and thus anticipate the rise up the StockRankings, you would have had to check the annual report the old-fashioned way - enter your figures on a spreadsheet or just pencil them in on a printed copy of the Stockopedia Report, to get an idea of how the ratios (and hence rankings) would change once the figures were all up to date and in-line. Or just get Paul to do the dirty work, which is what I usually do :-)
I've got other ponderings on the StockRanks too, but I'll be brief. Ed mentioned how (wonderful as they seem) the StockRanks might not work in other market periods, and also that many of the "expensive junk" stocks which were at the bottom of the rankings and had performed poorly were resource stocks - oil E&Ps, junior miners and the like. And I have to wonder how the ratings would fare in a less positive environment, especially given the momentum figure which many old-school fundamental types are wary of. Not something we can predict until it happens of course, as the StockRanks aren't even out of nappies yet. But amongst the impressive backtesting which was presented in the Webinar, I would have loved to have seen the results for the market with those resource stocks on their own, and the rest of the market without them, to see how the negativity against commodity and energy stocks might have skewed the results, and to get one small idea about how the rankings might fare in a different market environment.
Interesting debate on MMX. That's what makes a market. But even assuming there is take-up of the new suffixes, does this really create a sufficient recurring income stream to make this an interesting investment?
There is clearly a short term land grab under way but the experience of other licence grabs (think 3G) is that afterwards everyone realized the companies overpaid.
Whatever happens the land grab will quickly abate. MMX is then left with the choice of having a small registry business earning enough to cover management salaries. Or, (and this is much more likely) income and new money will be spent on new and unproven areas of internet businesses.
I can't see how this can be sensibly analyzed. Time for me to learn how to short a basket of stocks like this!
oldnotbold
Neustar has just bought .CO for $109 million.
Facts:
Since its global launch in 2010, .CO has grown to more than 1.6 million web addresses registered by individuals and businesses in over 200 countries and territories worldwide.
.CO Internet exited 2013 with an annual revenue run-rate of $21 million.
Neustar made $4m revenue in its role as back end provider.
So what does all this mean for MMX? Well now it's time for you to do some research.
How many domains might they end up owning outright?
How many partnerships do they have?
How many backend services are they providing?
How many domain names will minds & machines do directly.
How much money will they trouser on losing auctions?
We know that .CO (had you heard of it before today) sold 1.6 million web addresses for $109m. That's $68 per web address.
Good luck with the short.
Sorry previous post re: GTC!
Re: MMX & gTLD
A reality check can be found here -
https://www.linkedin.com/today/post/article/20140519231432-92568989-domain-name-train-wreck-ahead-why-the-gtld-program-may-not-succeed
Not really a reality check...just an opinion.
Facts: according to United Domains
per annum:
happy.london sold for $990
very.london sold for $495
only.london sold for $495
silly.london - binding pre-order $295
great.london - sold for $2990
greater.london - sold for $249
open.london - sold for $39
fantastic.london - sold for $249
fighting.london - binding pre-order $990
swimming.london sold for $2990
running.london sold for $2990
surfing.london sold for $990
guide.london sold for $495
That will give you some idea of take-up prices.
Then look at ntldstats and see that 85,000 xyz registrations have been logged (nothing to do with MMX, just an example of take up).
Those who say we don't need an extension to find a company are correct. But why set up a new business as .com or .co.uk when you can use a better descriptor. So Paul Scott will probably remain as PaulScott.com but the next Paul Scott may well register as PaulScott.Plumber or Paul.Scott.Builder or whatever.
The doubters are thinking in the past. The future - and where the money is - is what people do from here.
p.s. this company isn't inventing anything.....ICANN are behind the introduciton of new domain names.
Paul, You were right, I think your caution has been well served with a decent entry point. It is hard to say were the earnings may be next half year or the year after. From other investments I was aware of some budgetary constraints in this sector, but again the outlook was OK longer term, time will tell. I suspect this is not a basket case though, sufficient cash in the till and a nice freehold property will help me sleep having just bought my first few!
Re MMX. To be honest Paul I can't be bothered to argue with you. You clearly don't understand the process by which these new internet endings are being introduced and the very many ways money is being made here, including being paid for failing to win a domain name auction (the £4.1m credit.
If you are at all interested in finding out more about take-up then pop along to united domains website and try out happy.london, or swimming.london or running.london, or broker.london...and see the sort of prices people are paying for new domains.
Meanwhile: this is from Singer
SINGER EQUITY RESEARCH - just out!
Value of Portfolio Emerging – The group currently has a market capitalisation of £99m, and an EV of £77m. The group has 30 uncontested top level domains which it either wholly- owns or has an economic interest in. Crudely, this is equivalent to a value (EV) per domain name of £2.6m. On top of this, the group has a further 35 wholly-owned contested applications as well as 8 partner/client applications which it will look to resolve via private auctions which also have value.
As such, we believe that with strong execution on its different business strands (registry, registrar, and registry service provider), the value of the group should exceed the current market capitalisation given the portfolio’s potential to generate significant levels of profit and cash in the future."
"Understanding Company Financial Statements" R. H. Parker (Penguin) is a small book (160 pages) to get an idea of the statements.
Thanks Mark - your advice and the links/recommendations are really appreciated.
Re MMX. The gTLD stuff can probably be clarified here http://newgtlds.icann.org/en/applicants/auctions for anyone who may be interested.
At a quick glance, it looks as if those who have registered speculative claims to domain names enter an auction with others who have registered very similar names for the exclusive right to use the name. The proceeds are then shared with the unsuccessful candidates.
This doesn't sound like a recipe for long-term business success, though short-term it looks like quite a moneyspinner.
Hi Paul
VNET results don't look too bad. Maintained divi. but no big news. Would welcome your views.
Cheers
Mike
£CML's IMS of 17 Feb said "Within the Group's target storage markets, demand for mature flash memory controller products was slightly weaker during the period and this was partially a result of temporary supply chain abnormalities. "
That doesn't seem consistent with today's "sales were affected by the previously explained and unforeseen customer events within storage markets ".
I looked back at that in the hope that it would shed light on "previously explained". This previous "explanation": "partially a result of temporary supply chain abnormalities" explained (to me) absolutely nothing. For something issued under the "...Transparency Rules" this is deeply obscure. I don't want to invest in a company where I feel the management is not really coming l=clean with the shareholders about the trading challenges.
Hi Paul and other Stockopedia subscibers
I'm a new subscriber and am fairly new to the world of trading and find the daily small market reports a valuable resource. I'm always impressed with Paul and other Stockopedia users knowledge and understanding of company accounts. To improve my knowledge could anyone recommend a decent book around reading and understanding of company accounts, or any websites. Any advice would be greatly appreciated.
Best wishes,
Imran.
Hi Imran,
You might want to have look at the suggested reading list on ShareSoc's website.
I see from that that "The Meaning of Company Accounts" may be ideal for your purposes, though I haven't read it myself. I gained my knowledge of reading company accounts by running my own business and having to prepare the accounts for it. I used "Bookkeeping made Simple" (a much older edition than that one!) to gain my basic knowledge of accounting, initially.
Cheers,
Mark
Hi Imran,
Here is a link to a website:
http://www.buffettsbooks.com/
A down to earth book which is easy to read ...and Absorb ( very important) is:-
"The investors guide to understanding accounts" Robert Leach...Harriman house £20.
If you need more detail try this FT book much more dry but then more informative.
"Analyzing Companies & Valuing shares" Michael Cahill. Prentice Hall 2003 I believe I got my copy new on the Web for £2.50--but don't let that influence your decision. The author was a fund manager for 16 years.
There is also a lot on Stocko under explanations + definitions.
Hi Paul
Possibly a dumb question as I only have only just subscribed to stockopedia but do you happen to know if it is possible to view the Q, V, M and SR metrics for a given stock over time. For example, I have just looked at this information for CML and I have no feel whatsover as to how much this data has been impacted by today's results and subsequent SP fall. I would also like to be able to see how the numbers change when the inevitable broker downgrades occur.
I am having the same issue with PRES, albeit I hold shares in them, so noted the numbers down yesterday. However, in their case, they have today stated they will beat full year broker estimates, so upgrades are highly likely to occur soon. In their case, it would be helpful to track the impact of these upgrades and the strong H1 results on the Q, V, M and SR metrics.
Thoughts welcome
Thank you & Regards, Martin
Hi Martin,
I remember someone pointing out the useful print option on the StockReport which then gives you a list of dates for which you can download a pdf of the Company you are looking at. One from 1st March for CML can be found here. Hope this helps.
JJIS @Compound Income?
Jjis
Thank you for your post 18.
Regards, Martin
Hi Paul
Paul Scott 17th February 2014 – Getech (GTC)
“Give me a nudge if it goes below 50p, as that would start to look tempting.”
Around 40p today, so nudging.
Your huge fan, Bernard
(Now seen the update - thanks)