Small Cap Value Report (10 May 2016) - MBH, CAMB

Good morning!
Ed asked me to do a cameo appearance in his talk at UK Investor Show, in a side room. So I dragged myself out of the Westminster Arms, and popped over at 2pm to do a short talk on my favourite shares. Nobody told me that it was being filmed, but it was. Here is the link, of me rattling on about shares. I've not watched it back yet - everyone hates seeing/hearing them self!
Michelmersh Brick Holdings (LON:MBH)
Share price: 79.4p (down 1.4% today)
No. shares: 81.2m
Market cap: £64.5m
AGM statement (trading update) - a simple, but well-constructed trading update:
"After a very strong trading performance in 2015, I am pleased to report that the Group has performed well for the first four months of 2016. The Board expects the Group's trading performance for the twelve months to 31 December 2016 to be in line with market expectations.
This is the correct way to do things. All investors really want to know, is how the company is going to perform in the current year. It annoys me when companies duck this issue, and use a form of wording which gives them wiggle room (as for example was done yesterday with Fairpoint's trading update). The market sees right through it, when companies & advisers try to be too clever, and use weasel words to avoid making a clear statement about the company's performance.
So happily in this case, there is no such confusion. The company is trading well, and in line with expectations.
Valuation - it looks rather pricey to me - a PER of 18, for a brick-maker? That seems a pretty punchy rating to me:
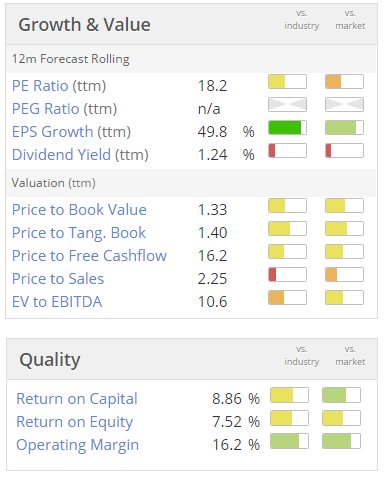
Ah! I've just noticed something. In the graphic above it says "(ttm)" - this indicates the absence of forecasts, so in this situation Stockopedia defaults to trailing twelve month figures - i.e. historic earnings figures. So that could mean that the PER is possibly over-stated?
I've had a look through my email inbox, but unfortunately there's no sign of any broker notes for MBH, so I'm in the dark with regard to earnings estimates for the current year.
It would be helpful if companies actually state what they believe market expectations are, by putting an asterisk next to the "in line" comment, then giving the figure below. Especially where there is little broker coverage, as in this case.
My opinion - since I don't have broker forecasts, I can't really comment any further on whether the shares are good value or not. Bear in mind there are also property assets here, so a hybrid valuation is probably best - i.e. using a PER to value the business, but then adding on an additional (discounted) amount for any surplus property value.
The divi yield here seems unexciting. One also has to bear in mind the cyclical nature of this type of business, and not end up over-paying in the good times, only to see earnings collapse when the next downturn occurs.
Cambria Automobiles (LON:CAMB)
Share price: 77.3p (up 10.4% today)
No. shares: 100.0m
Market cap: £77.3m
Interim results, 6m to 29 Feb 2016 - the market clearly likes this statement, with the shares up 10.4% today.
The figures look excellent to me. The key figure is:
Underlying Earnings per share increased 42.5% to 3.69p (H1 2015: 2.59p)
Can't argue with that! Cambria also makes some interesting comments today about the significant change in car buying habits - people are leasing cars now, instead of buying them:
The UK market has now had a sustained period of year-on-year growth in new car registrations. The March registration data showed 518,707 registrations in the month, the largest single month since the change to a bi-annual plate change in 1999. The consumer offers from the manufacturers make new car purchasing much more affordable with strong accessibility programmes and a dominance of Personal Contract Purchase ("PCP") product penetration in the new car market. PCP renewal activity in the new car market is now becoming the norm and Guest's changing their vehicles in a more structured manner, led by the finance product on a 3-4 year cycle, is now commonplace and has structurally changed the new car market over the past four years. We believe that the new car market is mid-cycle and registrations will continue above the 2.6m unit level for the foreseeable future.
As long as interest rates remain low, I expect this new pattern to continue.
I recently took delivery of a brand new car, because financially it was a complete no-brainer. Rather than paying out increasing repair bills to keep my 14 year old Jaguar on the road, instead I now have a brand new car, for just over £200 per month on a personal lease. Repair bills are nil, and it uses about a third less fuel than the old car did.
Outlook - this sounds excellent - trading ahead of market expectations. So forecasts will be raised no doubt:
Cambria's performance in the key March plate change month was strong and was ahead of both our business plan and substantially ahead of the previous year. The Board is confident that Cambria will maintain this momentum trading ahead of current market expectations for the full year and continue to deliver an improved performance across all its activities.
Balance sheet - very often when companies claim to have a strong balance sheet. they're lying. However in this case, the company does have a pretty sound balance sheet, with plenty of freeholds.
My opinion - I like it. This is a well-managed, entrepreneurial business, on a reasonable valuation.
I'm off for a siesta now.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

26 comments
Interesting article on Cambria and your new vehicle, but you made no mention of upfront costs and the potential mileage, hit which surely have to be added to the monthly payments.
Regards
Bob
Hi Paul,
Cenkos are the only broker I know who provide forecasts for Michelmersh. Latest research dated 21 March expects EPS of 4.9p for 2016 and 5.4p for 2017, which means P/E multiples of 15.8x and 14.4x respectively. I don't have a copy of the note unfortunately.
Thanks very much for sharing your thoughts here, very informative and interesting to read.
Anthony.
Found Pauls video very useful especially in recommendations of useful measures to consider for assessing a share
Given today's 10% + rise in the share price of Cambria Automobiles (LON:CAMB) on the back of bumper sales and profits any thoughts on why the share had fallen by 20% since the start of 2016 (it was one of Ed's 2016 NAPS) and Stockopedia's momentum indicator has fallen from 89 to 67. All this despite record UK car sales across the industry, which suggested they might be losing share to competitors (?). As I posted on the comments to Ben Hobson's recent article about stop losses Cambria Automobiles (LON:CAMB) hit my stop loss and was sold on Friday! Very strange and frustrating for the stop loss approach - inevitably if I break the rules and hang on to share it never comes back.
(PS Ed - did Cambria Automobiles (LON:CAMB) hit your stop loss and did you sell!?)
ACounsell I love to know this as well, seems to have happened a lot with other stocks. I got stopped out at 20% a few weeks back, so I'm disappointed. but I bought back in today , heres where averaging down back in would have been great, but I never did that as the stop loss took me out.. choices are dillemas!!
but yes I would love to know why the share price dropped to over last few months, especially when the company was doing well. 20% loss is a big hit on a share that had great results.
also I cant remember but how did it affect the stock ranking position??
I thought it was to do with the exposure to a recession and maybe Brexit as well, a lot of cyclicals such as house builders have fallen back and recruiters also. The first fall was in January, think that was when there were problems with China and oil. Unless its tied up with the high street retailers fall as well?
I don't think interest rates will rise much in the next 5 years or so by then there could be a recession so maybe interest rates will not rise for over 10 years. But I don't think that is the problem for the likes of Cambria Automobiles (LON:CAMB), but they are very exposed to a recession, I remember 2008 dealers were desperate to sell any cars, I got a good deal then, maybe I should wait to change it or as Paul says maybe I should get some finance deal.
I got a great lease deal in 2008. When demand falls off a cliff and the importers have ship loads of cars arriving at the ports the buyer is king whatever the purchase method. They just need to shift the metal.
on a side note theres talks today interest rates will remain same and even drop till 2019 in UK! Advantage for CAMB
Paul, I was surprised that you are now so keen on Cambria Automobiles (LON:CAMB) as the last time you discussed it on 7.3.2016 you finished off by saying:
"A word of caution though. New car sales are artificially high at the moment, due to the distortions created by ultra-low interest rates. Whilst dealerships make money from used car sales, and servicing too, with the macro factors currently in play, we should be valuing these companies on a low PER.
Therefore where's the upside? I think it's very unlikely that the PER will rise above 10, and earnings may be at or near a cyclical peak. What happens if/when the next credit tightening cycle occurs? Therefore the whole sector doesn't appeal to me at all. Although CAMB is certainly one of the best in the sector, in my view. There is takeover potential too, as I think consolidation is likely at some point.
Trying to guess what will happen with macro factors can be very difficult. Maybe interest rates will stay low forever? So there's also a case for just ignoring macro stuff, and concentrating on the value here. A StockRank of 98 appeals too."
Are you now working on the assumption that interest rates will stay low for a long time and if so does that mean you think it could rise above a pe of 10?
Thanks
Paul
As someone who is rarely able to attend these investor events, I am very appreciative of the video link to your talk at the UK Investor show. It was great to gain an insight to which metrics you scan for and how you view them - only reiterating what one can glean form reading your SCVRs of course but still good to see/hear you in a different medium. And I hope you are enjoying Abu Dhabi - just beginning to heat up in that part of the world I believe.
Cheers
Simon
Good results from Cambria Automobiles (LON:CAMB) . Although it's not mentioned, I wonder if they have benefited from not being a VW dealer and so avoided the fall out from the emissions issue/picked up trade from other dealerships?
I see that British Polythene Industries (LON:BPI) slipped out a trading update at 12.30pm today. I think Paul has commented favourably on this company in the past. Intra day updates are usually a red flag, but this one is a pretty encouraging "ahead of expectations" comment. They also refer to the closure of their Sevenoaks (Kent) facility and relocation to a new facility in the north. Might be a potential windfall if they can get planning permission to develop the site given the location in prime London commuter belt.
http://www.investegate.co.uk/british-polythene--bp...
Either way, market seems quite happy and shares are up 6.5%.
Gus.
Re British Polythene Industries (LON:BPI) trading update - AGM statements are often delayed until nearer the actual time of the AGM, which is late afternoon in this case.
Re. CAMB, when I changed my VW for another one in January before the negotiating commenced he said that they had not really seen any drop in trade... but I guess he would say that, wouldn't he, to think I wouldn't get a good deal with him. Hah!
Re. BPI, in addition to Splode's comment, I note that they also announced earlier on today the closure of a factory, so I guess they'd have an obligation to let the employees know before the stock market. On first glance it does look quite good value with current p/e of about 11, and future p/e below that... but Paul's comment in November after the prelims was:
"Overall though, I'd struggle to buy the shares after such a good run this year, from under 400p to 706p now, it feels too much like catching the tail end of a bull run, and it looks like a mature, low margin business, so not likely to get a premium rating"
One incorrection here would appear to be the price range though, it doesn't look to have been below 600p since start of 2015.
He was fibbing...who'd have thought it from a car salesman? :)
http://europe.autonews.com/article/20160204/ANE/160209915/vw-brand-sales-fall-again-in-uk-as-market-grows-3
Apologies dmj. My Fat finger gave your humour a thumbs down when I meant thumbs up!
There can be a four month wait from order to delivery on a new car. So the salesman can choose the measure to report on - fresh sales will clearly be down, but deliveries probably not for a couple of months. No need to lie, just choose which truth to tell.
Has anyone got a direct link to Paul's video? I am not subscribed to Shareprophets.
Can be found here: https://youtu.be/TP2U-1U-XTY
Thank you.
Great article, Paul!
Cambria Automobiles (LON:CAMB) is a really interesting proposition and agree that the change in behaviour behind car ownership will continue. I've read and listened to a number of commentators, particularly in the US, suggest that this foray into car ownership reminiscent of a sub-prime crisis albeit at a smaller scale - probably scaremongering, but food for thought for those investing in this sector. However, the sector is still in its relative infancy, it tends to be once the market gets very crowded that companies/lenders lower their standard and bundle together all sorts of bad debt. Cambria Automobiles (LON:CAMB) seem to be ahead of the curve here and as you mention I believe them to be a well-managed company, so this concern is probably more sector specific, than directly related to Cambria Automobiles (LON:CAMB).
I don't think its anything like the sub-prime crisis. The sub-prime crisis was to do with houses, people were getting loans for 10x their stated salary on properties that were not worth very much. The lenders did not care as they passed the problem on to someone else. Cars are not usually worth as much as houses. If you default on the loan they can repossess the car and then come after your other property. Think if you are a homeowner they could even get that, rates are lower for homeowners?
They should quote both historic and forecast P/E - at least then the forecast could be marked 'n/a' when necessary.
Cenkos has forecasts of £5m for PBT and EPS of 4.9p for @MBH per Morningstar
Very helpful comment - I often miss the ttm note and skip an opportunity because it seems too pricey. Also it might well be omitted from the results of a screen.
With brick companies it is only a question of time till the wider industry production capacity rises again and results like these become history.
One would hope that an update from a brick company should be "well constructed".... :-)