Small Cap Value Report (10 Nov 2015) - SDY, DSN, GBO, PRES

Good morning!
Speedy Hire (LON:SDY)
Share price: 31.75p (up 9.9% today)
No. shares: 522.0m
Market cap: £165.7m
(at the time of writing, I hold a long position in this share)
Interim results to 30 Sep 2015 - the shares are trying to rally this morning, although (so far) on little reported volume. Mind you, larger orders are often being worked in the background, and are reported later, on a delayed basis. So tracking the small retail trades during the day only gives you part of the overall picture.
I've held this share for several weeks, as a potential turnaround situation. So far, SDY has had a dire 2015 - with 2 profit warnings, in Jul and Sep. It's still not entirely clear what went wrong, but from what I can tell, it seems to just have been the basics of running the business that went haywire. There could be an element of sector problems, as HSS Hire (LON:HSS) also warned on profit around the same time.
The nice thing about SDY is that it has a solid balance sheet, so it shouldn't have any solvency issues whilst it sorts things out. Whereas the same cannot be said for HSS, which has a terrible balance sheet, and is hence not a stock I would go near.
The highlights box (below) from today's interim results demonstrates the operational gearing. So although EBITDA is down by a third, adjusted PBT is down by over 80%, since the big depreciation charge and financing costs are effectively fixed costs, so the impact of top line underperformance becomes more marked the further down the P&L you go.
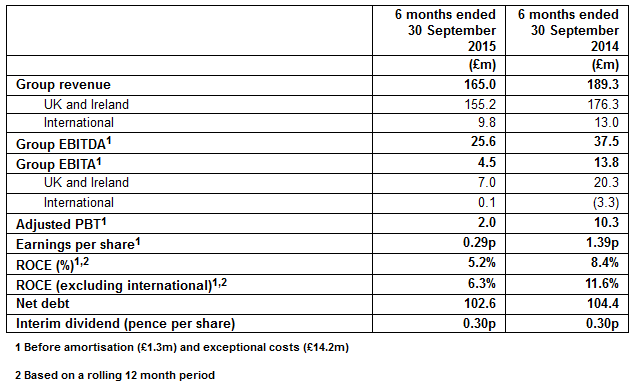
So a lousy half year, but the market already knew that was coming, so it was priced-in.
It's all about looking for signs of recovery. In that regard, I find today's results moderately reassuring, in particular that full year expectations are confirmed;
...confirms that the Group expects to deliver a result for the full year in line with the Board's expectations, as detailed in the Company's trading update published on 28 September 2015.
Clear actions to remedy underperformance seem in hand;
Remedial actions to address legacy performance issues are starting to deliver results;
o Reductions in administrative costs expected to deliver full year savings of c.£13m from prior year
o Redistribution of assets across depot network improving asset availability
o Ongoing IT system upgrades providing enhanced management information and an improved customer experience ·
Programmes to improve customer retention and acquisition being implemented;
o Emphasis on improved customer service provision
o Focus on innovation and differentiation
o Sales function aligned to better address the needs of both Strategic and SME customers
Full benefits of remedial actions will be realised over the medium term
The CEO comments also indicate that a turnaround is underway, although note the mention of medium term several times - clearly they are reining in expectations of a rapid turnaround;
These are early days in the Group's recovery and the full benefits will only be realised over the medium term. However, remedial actions implemented to date have started to stabilise our revenue base and we are expecting to see an improvement in the second half.
Whilst our markets remain competitive, Speedy remains a fundamentally good business which in a more lean, efficient and customer-focussed form, has the potential to once again deliver sustainable profitable growth."
Dividends - can often provide an important clue as to how confident management are about a turnaround, and also how secure the finances are. In this case the interim divi is maintained at 0.3p, so the yield is about 2.2%, if the final divi is also maintained.
Bank financing - the comments today are reassuring, and confirm my view that the balance sheet looks fine. Yes there is a fair bit of bank debt, as you would expect for a hire company, but net debt is only about half the book value of the hire fleet, which seems fine to me;
As at 30 September 2015, net debt was £102.6m (30 September 2014: £104.4m) giving a net debt to EBITDA ratio of 1.69x (2014: 1.38x), on a rolling basis.
The Group continues to operate well within its banking facilities having last year undertaken a re-financing which secured a new £180m 5-year asset-based revolving facility at an improved margin and with agreements in place to support additional funding, if required.
Oulook - comments today sound reassuring - it has the feel of a business which is over the worst of a bad patch, in my view;
These are early days in the Group's recovery and the full benefits will only be realised over the medium term. However, remedial actions implemented to date have started to stabilise our revenue base and we are expecting to see an improvement in the second half.
Whilst our markets remain competitive, Speedy remains a fundamentally good business which in a more lean, efficient and customer-focussed form, has the potential to once again deliver sustainable profitable growth.
My opinion - I quite like it as a turnaround. There's always the risk that more bad news might come out though. A full turnaround should get EPS back up to c.4p that was originally forecast for this year, before various problems emerged. That could command a PER of say 12, so a price target of 48p is the ballpark that I think could be achievable in say 1-2 years.
Not massively exciting, but if achieved, then that would give 51% upside on the current price, with divis paid whilst we wait too. So overall, worth a look I think, for people who can tolerate a bit of risk.
Densitron Technologies (LON:DSN)
Shares suspended - the company has asked for its shares to be temporarily suspended, so I looked into it, worried that the company might be in financial trouble. However, it turns out that I missed previous announcements saying that a maker of gaming machines called Quixant (LON:QXT) has bid for Densitron, at 11p per share.
It looks a good outcome for Densitron shareholders, as the company wasn't really going anywhere on a standalone basis, and the price paid looks fair to me.
Globo (LON:GBO)
Update - there's another short update from the Administrators of the plc. The aIM listing will be cancelled on 1 Dec 2015, which is a formality as we already know that the shares are worth nothing. This is confirmed again today;
The Joint Administrators do not anticipate that there will be any return from the administration for the shareholders of Globo Plc, and therefore they consider that it is appropriate that the securities are cancelled.
Given that the Administrators have now, several times, confirmed that there will be nothing for shareholders, then the Spread Bet/CFD companies really have no excuse for withholding client monies (both on the long & short side, both of which are margined at 100% at IG, for example).
This all begs the question, what happened to the cash pile which Globo claimed to have? Who stole it, and where is the cash, and the people who stole it? Or was the cash just burned up in day-to-day losses over several years, whilst fictitious revenues were put through the books to give the impression of profits?
Other interesting points from today's update - there will be a report published, which should answer the burning questions as to what on earth happened here, and who was responsible? Also, I think everyone wants to know where the Directors are hiding? Have they been arrested yet?
In accordance with paragraph 49 of Schedule B1 of the Insolvency Act, the Joint Administrators are required to submit their proposals to creditors within 8 weeks of their appointment and shareholders are also entitled to receive a copy of the report. This report will be made available to creditors and shareholders at www.thecreditorgateway.co.uk (password: Globo) in due course.
Note further that it's only the group holding company, the plc, which is in Administration. The operating subsidiaries are not. So that should mean jobs can be saved at operating subsidiaries. I imagine that the operating subsidiaries will be kept operating (if they are viable), and sold off - with the proceeds being used to cover the Administration costs, and anything left over going to the secured creditor (the Bank). If those costs are covered in full (very unlikely), then the next in line would be unsecured creditors. Only after all those are settled would any money be available for shareholders.
Clearly the Administrator has done the sums, and worked out that there's not going to be any chance of monies being available for shareholders, so that's that then.
The Administration relates to Globo Plc, and not any of the Company's direct or indirect subsidiaries, which remain under the control of their respective statutory directors.
What a sorry end to yet another overseas company that listed on AIM. AIM really does seem to be a magnet for conmen, doesn't it? That's the trouble I suppose, when you create a market with little to no effective regulation, and where nothing happens when people break the rules and rip off investors.
Once again it is demonstrated that shorters are the only effective regulation this market has. Once again, the City advisers seem to have turned a blind eye, as long as the fees kept rolling in. It's disgusting really, isn't it?
Pressure Technologies (LON:PRES)
Share price: 181.5p (up 23.9% today)
No. shares: 14.4m
Market cap: £26.1m
Full year trading update - covering the year ended 3 Oct 2015. It's surprisingly good actually, considering the sector - oil services, which as we all know is on its knees due to the ongoing low oil price.
As a result of strong performances across certain of the Group's Divisions adjusted EBIT (subject to audit) will be slightly ahead of market expectations. This is particularly pleasing given the conditions in our main oil and gas market and reflects the positive actions initiated in the first half of the year to integrate acquisitions and significantly reduce our operational cost base. We believe we have preserved our core skills, which will place the Group in a strong position when the market returns.
Unfortunately, I can't find any broker estimates for this year, so can't quantify this at the moment.
Outlook - various other details are given, and the outlook comments could have interesting read-across for oil services generally - has the sector hit rock bottom now, and might be a good time to look for picking up some bargains, I wonder?
Along with many others in the sector, we do not foresee any signs of pick-up in our main oil and gas market during 2016, however we do not currently anticipate market conditions deteriorating further. As a result, we remain confident in our expectations for our Precision Machined Components, Cylinders and Engineered Products Divisions. The Alternative Energy Division is project based and consequently is subject to the timing of new contract awards, but we are pleased with the growing momentum in this business.
Although, if no pickup is anticipated in 2016, then perhaps there's no particular rush to get involved in this sector?
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

19 comments
Ref GBO reminds me of Izondia back in about 2001 (the year I started investing), i'm still getting the occasional pay out from the administrators as they carry on searching for the money, what they got back, from memory, they retrieved from the banks for failing to apply proper controls when moving the money. Still nothing like what was lost. a very early lesson in not believing in stories.
Paul, thanks for your analysis of these companies
Paul - with respect to your visit to BOO tomorrow I would be interested to know (although I'm pretty sure these will already be on your list) :
1. Has the substantial increase in quality control headcount (3 to 20 from memory) had a discernible effect on the customer experience ? Carol Kane stated that (despite the price) the garments were not wear once and throw away but recycle as work clothes in which case they will get a bit more wear and tear.
2. Do they have stats on the effect that the App is having on sales ?
Thanks.
Good Afternoon Paul,
Thanks for your report as always. I wonder if you will have any time to take a look at Thwaites (THW) quoted on ISDX, which appear to have had stonking interim results,it looks like they are putting the interest rate swap fiasco behind them. The prospective p/e looks as if it is about 8,with a big discount to NAV,plus the most bullish statement I have ever seen from this chairman-usually she implies that the end of the world is nigh.
I know you have looked at or held them previously.
Cheers, Graham.
Hi Graham
Don't forget Thwaites have recently sold their brewing interests to (I think) Greene King, so this will flatter the figures. They are now also just another pubco; moreover they are one with their base very firmly in the Grim North! I can only hope the Nutty Black survives, and the company's shires are kept in use.
I suppose the spreadbet firms might wait until the actual date of cancellation of Globo shares [December 1st] to pay out on Globo shorts.
Hi Paul,
You've mentioned them in the past so hope you might have time to comment on today's results from Trifast which look good to me. They always manage to put out a short "interview" on the same day as results - why can't all other companies manage to do the same?
http://www.brrmedia.com/event/140657/malcolm-diamond-mbe-executive-chairman
Re PRES, what was that Buffett said? When a management with a reputation for brilliance tackles a business with a reputation for bad economics, it is the reputation of the business that remains intact.
NI
Pressure Technologies (PRES) may be worth a comment. After two profit warnings and stuck in the middle of the oil and gas market problems,they appear to have provided a surprisingly upbeat comment on their turnaround.
The market has already pushed them up 25%, putting back to where you last commented in June.
It looks like this management is putting in a superior performance in an awful industry.
The Pressure Technologies (LON:PRES) management also put out a very positive sounding statement a few months back...then issued a second profit warning! Aren't these meant to come in threes?
Hi Beginner,in fact it was Marstons. Profit has increased while turnover has substantially decreased. They are now a hotel and upmarket pub co. mostly in the North as you say. EPS if pro rata for the whole year would be 15p against an offer price of 1.17.
Prospects good according to the chairman.
Interesting figures from Marstons in their pre-close update a few weeks ago, the beer operation purchased from thwaites increased their beer growth from I think 5% to 15%, so it looks like it was a sound acquisition for them.
I'm keen on brewers such as Marston's (LON:MARS) and Fuller Smith & Turner (LON:FSTA) - Fuller Smith & Turner (LON:FSTA) in particular is a quality operation with a sound balance sheet, but that's reflected in their p/e of around 20. Marston's (LON:MARS) on the other hand has much higher borrowings but a p/e of almost half.
I realise that for many, breweries are out of fashion with the amount of pubs that are closing. But the numbers from the two operations support the thesis that there's room for quality operators who can differentiate themselves through quality beers, food through restaurants / pubs and also offering accommodation.
You only need look at the recent Chinese Premier's visit to the UK sparking huge demand for Greene King (I think) in China, plus the explosion in craft beers in the USA, shows that there is still demand left for the humble pint...!
Nice figures indeed! (Not sure how upmarket they are though, given their pubs in Blackburn!) The hotels are plush mind. Another positive are the awards they won as landlords in the tenanted trade. You could well be on a winner here Graham.
I second that. I remember - painfully - my holdings in a share that was at one time standing at my most profitable and then became my most unprofitable (all assuming I had sold on either occasion!) where the Chairman made a comment in the Outlook with words to the effect that a small fall off in orders in the key Cylinders section could be expected. Clearly, the orders tanked, and so did the shares. I dont think that we can read anything that the current management say and take it literally. No change before 2016 (and probably well after that - my words!) means just that. I dont see the reason for the SP recovery at this level at this stage.
GLOBO 's Administrators are missing a revenue opportunity. I am sure they could sell the film rights to Hollywood. Could make a blockbuster film :-)
How about asking Eros International? Bollywood film maker and current target of short sellers in the US! (Increasing receivables, doubts about revenues etc - you can write the script yourself!)
Hi Paul
I'd be interested to see your thoughts on Hayward Tyler (LON:HAYT) and Adept Telecom (LON:ADT), both of which reported results today.
Cheers,
Geoff
Hi Paul,
I would also be interested in your views on Lavendon, I hold them but they have moved south ever since.
Keep up the great work.
KR Charles
Hi Paul
Thanks for your write up of Speedy Hire (LON:SDY), which looks potentially interesting as a recovery play. What are your thoughts on Lavendon (LON:LVD) and the recent fall in share price there as it looks good value. Is there a read across from the recent problems at HSS Hire (LON:HSS) and £SDY? Looks cheap on a PER basis.
Best wishes,
Imran.
Hi Imran,
Yes, I like Lavendon (LON:LVD) and have been buying more. It seems to be slipping down in sympathy with the sector.
It's got a sound balance sheet, and I like it. I guess the market is pricing-in the risk of a profit warning. Personally I'm happy to take a temporary drawdown on a company I like, and just run it for a couple of years, as it usually pays off. You can't time the perfect time to buy usually. DYOR as usual!
Regards, Paul.