Small Cap Value Report (11 Feb 2015) - TRI, DPP, PTCM, TNG, LTC

Good morning! Do have a play with the new "Ranks" tab on the black menu above - it's great!I was experimenting last night, it's a new page to allow you to browse the stock ranking system here.
Trifast (LON:TRI)
Share price: 113.3p
No. shares: 116.2m
Market Cap: £131.7m
Trading update - this looks positive - note the "ahead of ... expectations" bit (although that refers to organic growth, not profitability - although they should mean the same thing);
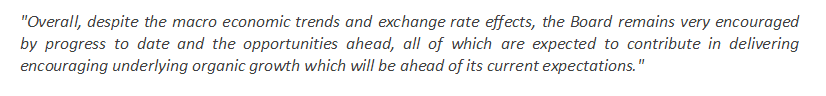
The update also refers to improved efficiency driving higher margins, and the potential for more growth through acquisitions.
My opinion - I've previously been sceptical about the valuation here, but given the positive news this morning, and what now looks like a fair valuation, I'm considering buying a few of these shares at 113p. The company has a good track record (see the Stockopedia graphs below), and seems reasonably priced for a company that has been consistently meeting or beating expectations in the last few years;
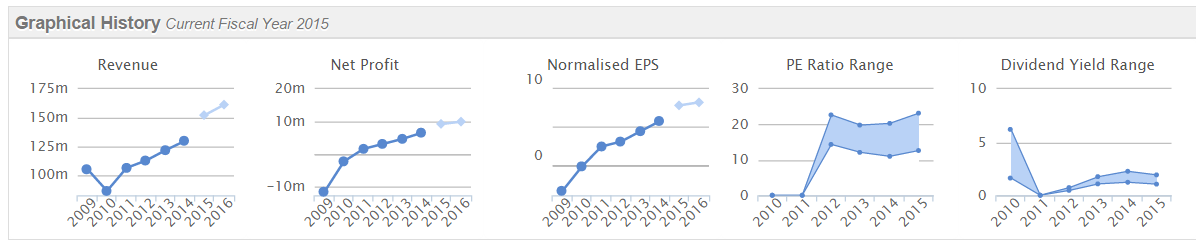
I didn't take to management when they presented at a Mello event a couple of years ago, but it looks like I misjudged them, as the business has performed well since.
DP Poland (LON:DPP)
Share price: 12p (up 27% today)
No. shares: 95.4m
Market Cap: £11.4m
Trading update - this company has exclusive rights over Dominos Pizza in Poland, so the hope has always been that the company could replicate its huge success in the UK. So far the company hasn't even come close, with terrible financial performance to date.
The company operates 12 branches in Warsaw & Krakow, with a further 6 franchised branches. Like-for-like ("LFL") sales were up 19% in 2014, which is very good (but from a low base).
The top 3 stores moved from EBITDA losses of avg. £13k in 2013, to positive £24k in 2014. That's a good improvement, but throwing a bucket of cold water over bulls, I would point out that capex is not paid for by the tooth fairy! The fit-out for this type of store is about £400k in the UK, so whilst it might be cheaper in Poland, you would still be looking at a significant amount. Therefore the depreciation charge is almost certainly bigger than EBITDA, meaning that the top 3 branches are actually still loss-making!
Bear in mind this doesn't even start considering what Head Office costs are. You need plenty of store contribution (i.e. branch profit) in order to fund all the overheads at Head Office. So if your stores are all losing money (as these still are), then you have nothing to cover your H.O. costs - every penny is additional cash burn.
The company made a £1.6m pre-exceptional loss in the six months to 30 Jun 2014, on turnover of only £1.9m. So based on today's statement, if we add say 20% to turnover, and guess that incremental turnover might be on a say 75% gross margin, then that would have added about £285k to profit. Thus H1, in 2015, if trading 20% ahead of H1 2014, would still be a loss of £1.3m on turnover of £2.3m.
In other words, the 19% sales growth the company is crowing about this morning would only reduce its losses a little, but still leave a yawning gap between where the company is currently trading, and breakeven (let alone profits).
My opinion - this company is taking far too long to establish the Dominos name in Poland, and whilst it has made some progress, is still heavily loss-making, even allowing for today's improved sales figures.
I suppose you could argue that sales growth might snowball, and result in it being decently profitable in future, but the figures to date make it look very much like an uphill struggle. It might eventually succeed, but it's difficult to see why investors would get excited about such a hesitant retail roll-out, when there are far more exciting, and profitable retail growth stories out there.
Cash burn is high, and it looks as if the company will be running low on cash by the end of 2015, by my calculations. So yet another Placing on the cards late this year, early 2016 probably. So a share for eternal optimists only.
Porta Communications (LON:PTCM)
Share price: 7.0p
No. shares: 267.6m
Market Cap: £18.7m
Trading update - after a brief initial surge, the shares are now negative on the day. There is clearly an overhang from a seller. It's as if the seller forgets about Porta in between announcements, and only remembers to start selling again when there is an RNS, irrespective of what the RNS says!
All very frustrating, but in the long run none of that will matter. Companies which are trading well will re-rate, even if a seller can delay that process for a year or more sometimes, with small caps.
Either that, or the company is not being honest in how it presents its performance. That has certainly been the case here before, when Porta wildly exaggerated its performance in 2013, claiming to be highly profitable, when it wasn't at all - they came up with a ludicrous definition of EBITDA, which stripped out trading losses for any subsidiary which had been open less than two years.
So I think it's possibly a case that the market disregards the company's trading updates, and will just judge the shares on real performance. So I will reserve judgement until the 2014 results are published.
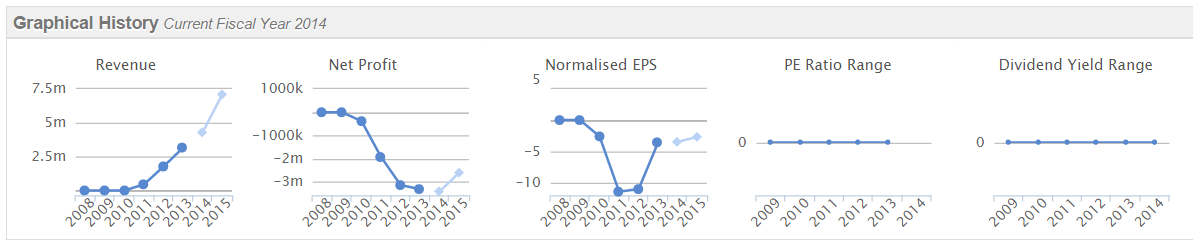
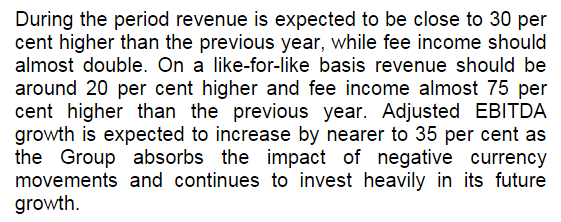
Today's update sounds positive, although negative currency movements haven't helped, and "investing heavily in its future growth" basically means running at a loss!;
My opinion - I think there is something potentially interesting at this group. However, management blew their credibility by putting way too much spin on previous results, which gave a misleading impression of how the group was actually performing. So they need to deliver proper profits, in order to rebuild credibility, rather than trying to massage the numbers to show a profit where there isn't really a profit. PR people just can't help themselves sometimes!
I'm prepared to be patient with this share though, as they are expanding rapidly, and have some interesting & quite high profile companies within the group. What do readers think of Porta? Your views are welcome in the comments below.
Tangent Communications (LON:TNG)
Shares are down 25% this morning on a downbeat trading update.
"Underlying profit" is expected to halve to £1.2m for the year ending 28 Feb 2015. The divi is being passed. Oh dear.
On the other hand, they have net cash of £1.4m at year end, so it still looks a viable business.
There might be a bottom fishing possibility here at some point, but looking at the market cap of c. £10m, it doesn't look cheap enough yet to tempt me. The key questions for me would be why is profitability falling? It surely must be down to competitive pressures. I'm not keen on investing in low margin, highly competitive sectors like this.
It reminds me a lot of £GRA which struggled to make progress in this very competitive sector (printing). That said, if you can time it well, there is the scope to catch a strong rebound with this type of stock. However, as we have seen with Grafenia, the big surge in price didn't hold, and it's slipping back down again.
Hate to say it, but I think both companies are probably quite low quality businesses offering little upside to investors, unless you get lucky and manage to buy at the lows, before a spike up. I'd rather buy into a small business that is putting out strong trading updates, than try to bottom fish ones that are disappointing.
Red24 (LON:REDT)
A positive trading update this morning - saying that the year ending 31 Mar 2015 is "ahead of expectations", and that momentum is expected to carry through into the following year. All very good.
These shares are now up about 50% in the last few weeks. We discussed it here not long ago, I seem to recall, and several of us liked the company.
Latchways (LON:LTC)
Only time for a very brief comment. I've been monitoring this stock for a while, and the trading update today shows the first signs that things might be stabilising, and have potential to improve, after a period of under-performance.
Trading for y/e 31 Mar 2015 is in line with expectations, and the Directorspeak sounds as if there is a more optimistic outlook.
The company has a strong balance sheet with net cash, and pays good dividends. So although it doesn't exactly look cheap, I've dipped my toe in with a small initial purchase this morning. I'm worried it might be too early to jump in, hence have kept my initial buy very small. I'll look at adding if the next trading statement confirms things are improving.
DYOR as usual, and please do let me know your views on this stock too, as I know opinion is divided on it.
Gotta dash, off for an investor lunch, see you tomorrow!
Regards, Paul.
(of the companies mentioned today, Paul has long positions in PTCM and LTC, and no short positions. A fund management company with which Paul is associated may also hold positions in companies mentioned)
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

14 comments
Hi jane,
I agree with you - in fact I usually disregard small Director buys, or even see them as negative.
The worst type of thing is when, immediately after a profit warning, all the Directors buy trivial amounts of shares, relative to their salaries & wealth. As you say, this is normally, if anything, a bearish signal! They get terrible advice on this issue from brokers & PR cos - I've challenged a number of companies on this issue, face to face, and they always say that their advisers told them to do it.
Bottom line is this. The numbers do the talking, and good companies will recover from setbacks, if mgt do what they are supposed to do, and run the company properly, instead of worrying about the share price!
That said, a £6-figure buy of shares is a lot more meaningful, and is worth noting, in conjunction with the fundies, in my view. Depends on the Directors though. Are they fundamentally honest, or are they manipulators? That's really the crux.
Regards, Paul.
So Wincanton has a Stockrank of 97!
Paul, I generally give very little credence to director share buys. Often, the numbers of shares bought equate to a month or two's salary, often they are dwarfed by free or cheap director share options. So, in many cases, they amount to nothing more than a bit of PR fluff. I'm not saying that's the case with PTCM. I have seen many cases, though, where directors' buys mean nothing or are even, imo, a sell signal as they seem to be attempts to fool investors.
Trying to dig in the numbers announced by Porta Communications (LON:PTCM) , an I am quite intriguied by tehe statement "Such was the success [in Newgate Australia] that the impact of the weak Australian dollar will affect Group profits before tax by approximately £200,000."
I am not an accountant, and know little about how overseas profits are translated, but here is how I undertsand it:
That means PBT in that business would have been £200,000 HIGHER if the exchange rate hadn't changed in 2014 right? Since the GBP/AUD rate moved from 1.85806 at 31 Dec 2013 to 1.90284 at 30 Dec 2014, are we to assume that a 2.4% decrease in the value of the Australian Dollar is worth £200,000 to £PTCM? Really?
Please note that the exchange rate mostly moved between these two values during the year, so I just don't understand how that could be worth so much money to PTCM, unless they did a 8m profit in Australia?
If anybody understands this better than I do, I would love to hear from you!
Thanks!
Hi aiminvesting,
I agree, that comment in Porta Communications (LON:PTCM) results about Australia being so successful that it caused a forex loss, seemed bizarre, without a proper explanation.
As mgt have form for being less than clear about the truth, I took that as glossing over a negative.
Maybe it's relating to translation of overseas cash or debt, rather than earnings? Their vagueness doesn't help, and I can quite see why investors are sceptical about this company, and awaiting results. The share price has reflected that.
For a PR company, I am distinctly unimpressed with Porta's PR about itself! Let's hope they are doing a better job for their clients. That said, I do come across the company's name on plenty of RNSs, so they're pretty active in financial PR.
My industry contacts tell me that Porta are trying to grow too fast, and hence are making mistakes, but that they are fundamentally quite good. That's why I hold the shares. Am annoyed with management, but think there could be something interesting in the long run, as they've got a lot of experience in the sector. Also a chunky Director buy today helped.
It may seem strange that I am critical of a share that I own, but my views here are the unvarnished truth, as I see it, at the time of writing. Sometimes it's right, and sometimes wrong.
Regards, Paul.
The results misrepresentation in January 2014 was very convenient for Porta Communications (LON:PTCM) in my opinion, if you consider they managed to double the share price just before placing the shares they needed to fund some acquisitions. In fact, that is all very nice for existing shareholders, since it minimized the dilution caused by the placing. Of course, downside is that management have lost most of their credibility with shareholders, and I am sure the Insititutions which participated in the placing appreciated. Not very clever on the long term. And of course, quite annoting for private investors who, like myself, invested on the basis of the dishonest trading statement, and later discovered they had been used to inflate the share price.
A few things catch my eye with DPP (£DPP)
It is the smallest in a very successful stable of quoted Dominos Pizza master franchises. Dominos Pizza has thrived in just about every territory that it has entered. It seems we all love a stuffed crust, double pepperoni with extra jalapeno. Look at the global store footprint: 5016 stores in the US, 6265 stores internationally with management estimating it can grow the international store footprint by a further 50% to 9300.
DPP has had its troubles, but has changed internal management, changed some of the operating metrics eg replanned the stores to make them smaller (less rent payable) to try and deal with them. Importantly they are getting the Pizzas to the customer hot and as ordered. I hope they can improve it enough to get the model to work because when it does, it is phenomenally successful. I agree with Paul cash burn will probably require the business to seek extra capital which will be problematic. If though, the stores can be brought to cash profitability I expect management to sell down its remaining 12 corporate stores to franchisees and accelerate the roll out. That is when investors will make serious money.
I had a good look at the Dominos franchise system about 3 years ago and made the worst decision based on upside rather than what was my downside. I bought DPP, not the parent company Dominos Inc ($DPZ). One has tripled the other has halved !
So why haven't I sold ?
As i mentioned this is a tried an tested model for consumers AND investors.
Some interesting stats
One thing to point out is that Dominos Inc ($DPZ) has an EV/Store of £930k / store but this is misleading as all of the 6265 international stores contribute c3.1% of revenues as a royalty payment pa for the right to use the Domino’s brand. This provides DPZ with an extra $240m of revenue pa at a 49% margin. I have not adjusted for this in the spreadsheet.
If I compare DPE (Dominos Pizza Enterprises: quoted in Australia and owns master franchise for Aus, NZ, France, Netherlands and Japan) and Domino's Pizza (LON:DOM) (Dominos Pizza plc which owns master franchise for UK, RoI, Germany & Switzerland) they both capitalised with an EV / store of c£1m. These are mature proven formats making cash profits and paying dividends to investors. So not a fair comparison with DPP, which is more of a very immature, ugly step sister at best. But DPP originally wanted to get to 200 stores (from memory, I may be wrong). Maybe this could be 100 long term? If the model can start to work then this could be worth £50m (100 stores capitalised at £500k, a 50% discount to the valuation of Domino's Pizza (LON:DOM) and DMP) vs current mkt cap of £9m.This probably a case of hope over reality but explains why I still believe it COULD be possible and why I am holding on.
Thanks for the analysis VegPatch, good work.
I looked over DOM.L about 6 or 7 years ago. I didn't manage to find anything at all about the master franchies agreement with the US parent, how long it lasts for and what stops the parent asking for an extra 2% or so, if the contract comes up for renewal. With hindsight, that's one that got away.
I have held Trifast TRI or a while now and have been very happy with their performance, but as you noted in earlier comments this is in the end a nuts and bolts company that is riding on a (welcome, if modest) UK manufacturing revival.
It is a general concern for me that for this revival to continue some worldwide growth is needed to take things much further. This concern also affects holdings in Hayward and Tyler HAYT, Castings CGS, 600 group SIXH, Scapa Gp SCPA and others.
Is it time to look sceptically at this sector in general? Usually the market anticipates downturns and I wonder if anyone else is beginning to find their finger hovering over the "SELL" button
Hi Paul
For what they are worth, here are my views on Porta Communications (LON:PTCM) and Latchways (LON:LTC) . I have a small holding in the first, and have the second on my watchlist. Porta Communications (LON:PTCM) is really a gamble on the management. They are experienced and have done this growth by acquisition job before. In other fields it has worked well (eg Oxford Instruments (LON:OXIG) and Melrose Industries (LON:MRO) ). The credibilty gap they created will take some bridging, but I am happy to give them the benfit of the doubt for now. Results in April will allow me to decide if this is worth putting a little more into or not. As the price appears to be being suppressed by a seller, little dips below 7p could be a buying opportunity in the present.
As for Latchways (LON:LTC) their niche products are a positive, but the problems in the US that started the price decline here have not been sorted out yet. The US is a key market, especially at the moment as it is one of the few areas of economic expansion. We should also not foget their ultimate markets include aviation and oil engineering, so their could be further setbacks to come. I would be happier entering below 700.
Snoozebox (LON:ZZZ) still jam (possibly with a croissant) tomorrow. An EBITDA loss in 2015 is disappointing since it excludes the cost of the V2 unit.
EPS f/c was already for a 0.58p loss.
I've seen the demo V2 and it looks very good but long term earnings visibility is still poor.
Looked at DPP a while back came to the same conclusion re. capex and cash burn -- assuming DPP does gain enough traction in the Polish market, it will probably still have to raise more money before that point.
Of Domino's Pizza Group (DOM, not DPP), its RoI business has faltered at points and its Germany business looks to have been a pain. Switzerland seems on track and the UK is thriving. Clearly the model does not work everywhere, or can be a bumpy ride as the brand establishes itself and the marketing and promotions do their work.
This may be the case in Poland. The management are experienced and any significant pick up in business will be well-flagged for those that choose to keep their eye on this one. Just no point being in it right now.
Any views on ZZZ?
Paul
Red24 (LON:REDT) has issued a positive RNS this morning. I'm happy to be long.