Small Cap Value Report (11 Sep 2017) - ITQ, UPGS, LUCE, XLM, EKF

Good morning!
Seems busy in RNS-land, so I might make each comment a bit more concise, to extend coverage.
Interquest (LON:ITQ)
- Share price: 28.5p (suspended)
- No. of shares: 38.7 million
- Market cap: £11 million
Update on Nominated Advisor and Suspension
I'll start by bringing this recruitment company's story (scandal?) up to date.
In a late announcement on Friday, Interquest released an "update" saying among other things that when it fired Panmure Gordon, it believed it was going to be able to find a replacement within the required notice period to avoid suspension.
But since it unfortunately (!) failed to carry out due diligence in time, the shares have been suspended as of today.
It also said the following:
The Company is actively working to engage a replacement nominated adviser and broker and expects that an appointment of a replacement nominated adviser and broker will be completed within one month of the suspension. Any appointment of a new nominated adviser and broker is subject to the satisfaction of due diligence and therefore, whilst the Company does not foresee any circumstances at this stage which would lead the admission of its AIM securities to be cancelled, there can be no guarantee that such due diligence will be completed satisfactorily.
No reason has been given for firing Panmure Gordon in the first place. So one is left with the conclusion that the powers that be simply don't want to have a stock market listing.
The risk of de-listing is particularly high with smaller companies, for investors who need liquidity.
If you don't need liquidity, then there is nothing wrong with owning shares in private companies. Most companies aren't listed publicly, after all.
What makes this particular episode a bit distasteful is that there hasn't been a positive rationale given for choosing to be a private company rather than a public one. Unless there was some specific problem with their existing advisor (and we have no reason to believe that there was), then it looks as if the company is being taken private on a technicality, deliberately. Which isn't in the spirit of how the stock market is supposed to work.
UP Global Sourcing Holdings (LON:UPGS)
- Share price 117.8p (-44%)
- No. of shares: 82 million
- Market cap: £97 million
This branding, sourcing and distribution company has been listed since February. It imports a range of consumer products from Chinese manufacturers (cookware, tabletop, laundry, etc).
Growth for the current year sounds excellent. But when you read through the statement, and get to the outlook, you find the growth picture suddenly evaporates.
For the year ended July 2017, performance is above expectations:
Group revenue increased by 39.1% to £110.0m (FY16: £79.0m), and continued to be driven by three main factors: growth in sales to discounters in the UK and in Europe (up 64.6% to £63.8m); increased sales from the main UK supermarkets (up 95.0% to £10.3m); and the emergence of online platforms as a new revenue for the business (up 63.6% to £4.6m).
The Board anticipates reporting underlying EBITDA and underlying PBT performances that are above market expectations, mainly driven by higher revenues.
Major retail accounts have been opened in Germany, where the potential sounds really strong.
And then we have the stark announcement that revenue growth for FY 2018 is unlikely, for the following reasons:
Consumers' discretionary spend is under pressure and confidence is therefore lower than it has been for some time, which is inevitably being reflected in purchasing behaviour. For retailers, this has also coincided with cost price increases in the wake of last year's sterling devaluation. As a result, retailers are generally exercising caution with regard to their non-food buying for Autumn/Winter 2017. This is manifesting itself in a reluctance to commit to purchasing too far forward, with retailers instead placing orders later or buying from stock.
Is this really news, in terms of the macro conditions?
Despite the stock market being so richly-valued, investors can see where the price of sterling is and we have known very well that high street conditions are tough.
I suppose what's particularly worrying about this announcement is how growth can go from such a fantastic clip to suddenly drop all the way back to zero.
PBT was £6.7 million in H1. The company is more than 60% weighted to H1 but even if you assume little profitability in H2 and negligible growth going forward, maybe the shares are decent value here?
As I said with Safestyle UK (LON:SFE) last week, though, I would try to be a bit more ambitious in my timing when it comes to some of these most highly cyclical sectors. We are still very far from peak-gloom, in my opinion!
Luceco (LON:LUCE)
- Share price: 245p (-1.6%)
- No. of shares: 116 million
- Market cap: £284 million
This LED manufacturer is a recent IPO which has been more successful for investors. It joined the stock market last October and the shares are now up almost 70% from when they listed.
I covered the full-year results earlier this year and was really impressed by the growth. The shares had already appreciated by then, though I said it looked like the company might be able to grow into the valuation.
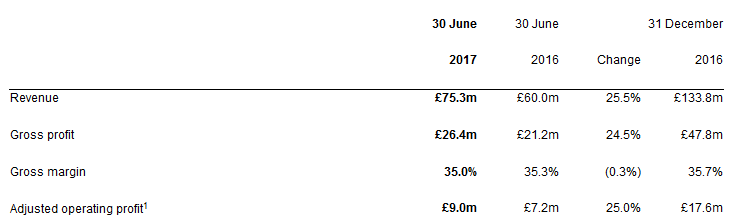
These are fine growth rates and I would note that no adjustments were made, so adjusted operating profit equals operating profit.
The outlook for the full year is in line with market expectations.
Net income improved at a much faster rate than operating profit due to the post-IPO capital structure with much lower net debt, so interest costs to be deducted from operating profit are much lower now.
Net debt is now £26 million, or 1.1x adjusted EBITDA. Gross debt is around £32 million. Seems fine versus annual earnings power.
One slight negative perhaps is the failure to improve the operating profit margin, due to distribution and administrative expenses rising proportionately with revenues.
It's still a high-quality stock, though. 12% operating margin isn't bad and combined with its asset turnover (revenues/assets) and the use of financial leverage, it generates a massive return on equity:
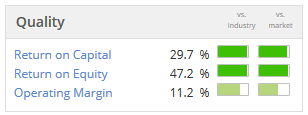
So my overall impression remains pretty good and I don' think the valuation is too far out of line. I'm not expecting industrial/commercial LED lighting to be highly cyclical markets, Luceco has broad geographic exposure, and there is plenty of market share for it to reach for.
XLMedia (LON:XLM)
- Share price: 139.5p (+8%)
- No. of shares: 204.4 million
- Market cap: £285 million
Lots more progress from this Israeli performance marketing group. It funnels internet users into gambling websites and other highly commercial venues, and operates related websites which do the same.
It gets a stake in the long-term revenues of the users it sends to gambling websites, making it highly incentivised and richly rewarded for finding and converting the highest-value users.
It's also growing in the financial sector (credit cards, etc) and is making acquisitions with the large cash pile it has accumulated. Gambling has reduced to 63% of total revenues.
For this latest period, revenues are up 33% to $68 million and PBT up 23% to $19.5 million.
The Board is confident of "comfortably meeting market expectations" for the full year.
My opinion
I think the co-founder and CEO of this company is an intelligent fanatic as defined by the expert small-cap growth investor Ian Cassel. He has had important colleagues, for sure, but it has primarily been his vision which has created this company out of nothing and which is guiding it toward the future.
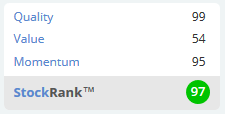
Investors on the whole find the company a bit hard to understand, and have a bit of scepticism toward Israeli companies, therefore you get this incredible StockRank:
For my own part, even though I rarely have ethical objections to investing, I am a little bit squeamish about what might be interpreted as the manipulation of internet users into setting up gambling accounts. Strangely, I don't feel this way about gambling companies themselves such as Paddy Power Betfair (LON:PPB). There is probably a flaw in my thinking somewhere.
Leaving aside the ethics, it looks like a fine investment opportunity.
EKF Diagnostics Holdings (LON:EKF)
- Share price: 24.75p
- No. of shares: 464.3 million
- Market cap: £115 million
I'll offer a quick comment on this, which hasn't been covered in the SCVR for a while.
It's a medical diagnostics business which makes point-of-care patient tests and laboratory products.
Current trading is in line with expectations for 2017. Operations have been streamlined, including the closure of a manufacturing facility in Poland. In total, the number of sites has reduced from 12 to 7. But the growth numbers are still good:
· Revenue up 22.8% to £21.50m (H1 2016: £17.51m)
· Gross profit up 40.6% to £11.84m (H1 2016: £8.42m)
Capital reduction: interestingly, EKF considered splitting itself in two, separating the two divisions. It won't be doing this, for tax reasons. Instead, shareholders will need to be satisfied with a planned share buyback of 15% of shares.
My opinion: all divisions are growing nicely. R&D spending has reduced to £0.8 million for the period, which is probably a bit conservative, but that's ok.
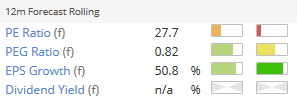
The rating is on the high side so I'd need to see more evidence about the underlying quality to have interest in making a purchase. It might be worth exploring in greater detail:
That might be it for today, I'll see if I have any more time later this evening.
Thanks for dropping by,
Graham
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

67 comments
Regarding XLMedia (LON:XLM); the way you describe it as "manipulating users" suggests something far more malicious than say a company advertising for gambling companies, or a betting company offering sign-on bonuses (you could argue both are trying to manipulate economic behaviour of others). Seems you have looked into this a bit, could you shed a bit further light on this matter? I'm genuinely intrigued.
Thank you.
Off Topic -Cliches
Did you hear about the dead cat that bounced until it was hit by a falling knife?
LOL. This is pretty brutal. I hope the directors hang their heads in shame.
re UPGS Fall of over 50% seems harsh and I would expect a bounce and perhaps a decent one. Let's see.
Yes I thought that also but it's down over 10% today.
Another poster earlier mentioned K3C [for some reason the usual pound symbol £K3C trick not working on this one] their first final results since listing today, and it sounds pretty interesting. Though it only recently listed, apparently (according to these guys http://trendwatcham.com/k3-capital-group-buy-127-5p/) it's possible to look at revenue numbers back to 2014, which shows £2.93m in 2014, 4.94 in 2015, 8.55m in 2016, and now just report £10.8 for 2017 till end of May. Profit before tax is up to 3.7m in the latest results, from 0.4m in 2014. Headcount apparently doubled from May 2016 to May 2017.
With a PER of 13, does this look like good value? curious what others think...
I think K3C looks good value. It had been on my watchlist for a while and I took an initial position yesterday morning after results; it meets many of my criteria - steady profit, revenue and EPS growth. As the IPO was only 6 months ago, I think it's under the radar of a lot of investors at the moment. Hopefully it will work its way up to finnCap's 160p price target.
Looked into ITQ and was half tempted when I saw that Jim Mellon had a load of shares, initially I thought that they must be good if he had bought them, but then wondered if my thinking was flawed. Glad I googled him and found a web of associated companies he was involved in and then concluded I would not buy them after I read a post that he has been known to asset strip companies after they get delisted and sell them for more. I will be steering clear from now on of the likes of Port Erin Biopharma, Manx Financial, SalvaRX et al as I don't want to be working until I am 80 to pay for his high life even if one of his companies may on the off chance be able to rejuvenate me enough to do so.
Graham, I understand the premise that a minority shareholder in a private company 'simply' (ostensibly) loses liquidity. However, what is to stop majority shareholders devising to use any of the business' profits to increase remuneration to executive management rather than distribute some of same equitably in dividends to all shareholders? When management have had the original capital from their AIM listing, if they delist (however they achieve this) why would they be concerned at all as to the nominal 'value' of each now-private share? Who would want to purchase such powerless shares? It is for these reasons that AIM regulators ought to be concerned since this kind of unscrupulous behaviour besmirches the AIM brand.
Hi geronimo,
Can't majority shareholders with managerial positions in public companies also use their control to pay themselves too much?
Many stock market investors prefer to see a diverse shareholder base, for the precise reason that they don't want to be disadvantaged versus management.
The problem is primarily the power imbalance. Liquidity is secondary, IMHO.
Graham
Yes, they can, Graham - but in that situation a disgruntled minority shareholder at least has a market within which to exit with cash in exhange for having relinquished any vestigial modicum of a say in his/her notional part-ownership of the company.
Moreover, one would hope that the relevant regulatory authorities might exert some statutory (or contractual) constraints to moderate/mitigate the blatant breach of fiduciary behaviour owed by management to their whole constituency, and not merely to the majority shareholders many of whom have an otherwise rewarding vested interest.
On UP Global Sourcing Holdings (LON:UPGS):
Blimey, they didn't last long, did they?
It's all a sick joke, really. Makes AIM look like little more than a bucket shop.
ed, I once tried to do this myself for a company that in my view had effectively allowed insider dealing by management. Actually two companies I am aware of did that but one it was provable. Nothing happened. I rang up the LSE and the regulatory department is different for AIM. I.e. probably a couple of people in the cellar.
Reeling from near 50% fall in UPGS - esp after reading only first para on exceeding market expectations before dashing to work!
Not worth selling now but is it worth buying at this price? Any views?
Richard
I'd consider any further purchase carefully (after asking the CEO and the board some straight questions), ideally face to face so you can see them answering these points.
The half year report in April states the following:
The directors consider that the principal risks and uncertainties which could have a material impact on the Group's performance in the remaining 6 months of the financial year remain substantially the same as those stated within the Group's Historical Financial Information on pages 96-97 and pages 111-113.
I have today looked at the prospectus and the risks they have set out do not include consumer discretionary spending falling, which may affect their order book. In fact they deem to list competitiveness against other brands a risk, but not that customers may stop spending.
As Graham points out, the macro conditions have been known for some time now and this is nothing new, so why is this now news to them?
Either the directors are incompetent for not seeing these risks and mitigate against them, or (and this is my view) they have pocketed a sizeable chunk via their IPO and any stake they have currently is neither here nor there.
I expect there will be a bounce tomorrow, before falling back over the week, but then again dead cats and falling knives.....
EDIT to add: consumer demand is listed in their prospectus, now I'm reading through all of it, but on different pages than is set out above (page 65 if anyone is interested)
In response to Leven's comment on XLM I would say an issue is that anyone could probably set up a website to direct traffic this afternoon not that they would be very successful because firstly you have to gain a good ranking with Google in order to attract business. I would hope that XLM will have built up a good relationship with gambling sites and can work with them to avoid breaches of regulations. The affiliates are, of course, an important source of business and any dificulties may result in only the more trusted affiliates being retained.
I see that the CEO has purchased nearly 150K shares today.. Having held for some time I have no worries but obviously watch the charts with support now existing at around 128 and hopefully that can be moved up to 140 in the not too distant future.. I would not hestitate to sell on a breach of 128 at present looking to come back in either on a recovery to above that mark or on lower support becoming established.
Graham
Have you (or Paul or any subscribers) any view of Dialight (recent interims end July) midway through their major turnround strategy in comparison with Luceco who you have reported on above?
Peter
Hi iiimurray,
I was interested in your comment because this morning after reading the LUCE results I had a quick look at the DIA ones to form a high-level view. I don't hold DIA (although I used to), and have been aware of them being on a rocky road for a while. My conclusion was more that LUCE look fairly good value compared to DIA with good growth figures whereas DIA seem to be finding it tougher with their transformation taking longer than envisaged - the difference in the two seems to be that LUCE operate in a wider market whereas DIA are more focused on higher-end industrial markets.
Andrea
Hi Andrea
Thanks for comments - don't know much about Luceco market sectors but have had more involvement with Dialight who you are right to observe are now much more focused on industrial sectors which should secure higher margins and allow some differentiation from commodity LED relatively low value producers with bespoke units and 10 year warranty. Dialight's move to contract partner manufacturing allows focus on design and development of next generation technologies along with rationalisation of stock ranges is well advanced as part of 3-year strategy to return to sustainable profit and growth - challenge is to convert more customers to LED with lower operating costs and maintenance to offset higher initial investment cost.
Peter
Re XLMedia (LON:XLM) Graham you may be right to be squeamish given affiliates normally receive a profit share and are often conflicted (i.e. tipsters trying to tip losers). Regulatory pressure is increasing as a result of this...
https://www.casinopedia.org/news/sky-betting-stops-affiliate-programme
Concerning XLMedia (LON:XLM) I was not sure what to make of the statement that they are in dispute with the Israeli tax authorities over a number of historic tax years. In my experience it is not uncommon to have more than one years Tax Comps not finalised (in the UK) at any one time but this seems to be something more serious (as they mention it) - albeit they say they believe they are adequately provisioned.
Has anybody got experience of dealing with Israeli Tax Authorities here and can put some non-specific background to this ?
(Long XLM)
Graham, any chance you might look at LSE:REDS, had an announcement on fri, market doesnt like/believe it . Thanks
I don't know anything about Interquest (LON:ITQ) before it was mentioned recently, but reading the above, it sounds like a complete joke. You have to be a really beyond the pale if you can't find a nomad to take your money. I mean, come on, the company couldn't have been trying to find a nomad.
I have just emailed my complaint about the Interquest (LON:ITQ) termination of Nomad and suspension to aiminvestigations@lseg.com. I meant to do it sooner. I have no position in Interquest (LON:ITQ).
Regards,
Ed
Ed, You will get a standard reply saying they may look into the matter but can't comment. Then nothing will happen. There seems to be no regulator accountability. I am guessing that the head of AIM (Marcus someone) just gets remunerated on the size of the market and the money raised. So as long as the issues don't threaten AIM's overall momentum nothing happens. It is a different story for main listed companies where institutions require standards.
Indeed, that's precisely what I expect, but I didn't want this flagrant rule-breaking and contempt for the wishes of shareholders to go by without challenging it, so I sent an email anyway. Marcus Studdard's tacit acceptance of such malpractice, and the numerous AIM-listed frauds, whose perpetrators go unpunished, ought to shame the City of London.....if it had a modicum of ethical standards. Sadly, it doesn't.
Maybe if (when) you don't get a reply from the people at aiminvestigations@lseg.com, then the next step is a letter to your PM. If enough people follow up complains via their PMs it might just add some pressure.
(I'm not an Interquest holder myself, but still think the whole affair is a bad show)
Yes, I agree, I should follow up, when my expectations of a lack of action by AIM Regulation are shown to be well-founded, with a letter to my useless MP.*
*Who failed to reply to me on the only two occasions I emailed her. Sadly, she is in a very safe seat and won't miss the vote I will never give to her.
Have you any time to comment on Summit (SUMM) with regard to their RNS today.
Regards Tom
Good morning Graham!
I would be interested in your thoughts surrounding K3 Capital (K3C) who have reported maiden final results this morning following their I.P.O. back in April. They are probably best described as a disruptive all inclusive broker/ matchmaker for buyers and sellers of small businesses and claim to generate around 600 leads per month followed up by a dedicated sales team through their website www.company-valuation-services.co.uk
Cheers Denis.
Hi Graham,
If you get a chance, I'd be interested in your view on Diversified Gas & Oil (LON:DGOC). Another AIM listed gas and oil explorer who released half year interims. They own Titan Energy's previously held assets. I picked some up last week and am long, and before you shake your head, some key points from their interims include:
"what we believe to be a unique investment proposition on AIM:low-risk, cash flow positive, dividend paying Exploration and Production Company.... Whilst these half-year results demonstrate the Company's steady progress through to 30 June, they do not reflect the significantly enhanced financial and operational capabilities that we expect to report in 2H17, following the completion of our transformational acquisition of certain Titan Energy Appalachian Basin assets"
So, in effect, another 'jam' tomorrow company, that is already making money, the hope is that they push on further on what appears to already be a cost efficient basis.
The CEO is called Rusty Hutson, which conjures an image of a proper stetson wearing American in my head, which can only be a good thing IMO...
@Ricky65
Good trading and discipline imo. To only give back 8% is a win. You really cant go too wrong with such a solid strategy and cutting loosers fast is the only way to win in the long run. Just my thoughts.
Hi Damien. You're right - I feel like I've won losing only 8% considering the SP is now down ~46% as I write. If my stop wasn't in place and I just logged in now, I'd feel gutted to say the least! It would probably be an agonizing decision on whether to sell or hold. Auto stops make trading a lot easier psychologically in my experience.
I agree with you on cutting losers - reading Mark Minervini's books showed me the importance of stop losses. I don't think you can have long term sustained success without them (I know Paul Scott and others disagree! Each to their own).
Hi Ricky65
Yes, others do disagree, as you say. Thanks for that conceding that!
I feel the issue over stop losses or not depends on one's investment style (trader vs. investor), the stock (volatile vs. steady performer), the market (bull vs. bear vs. on the turn) and possibly a host of other factors. I could quote any number of examples where a stop-loss would have sold me out of a long-term rising share (today's first example would be Mortgage Advice Bureau (LON:MAB1) ). The thing is perhaps to know one's own comfort zone or investing style. I'm not a loss stopper (mainly my holdings have a solid balance sheet and most pay a dividend - which are important to me as investments are my only income), but best of luck with your stop losses, if they serve you well then stick with them :-)
Edit: Since posting the MAB1 bounce-back has faded away, so not such a good example now! Such is life :-)
Hi Lion Tamer
Fair enough, I suppose if you’re a long term investor, short term dips are something you wont be too concerned about. For the most part I’m more short term oriented myself (for better or worse!) and think it’s an opportunity cost to hold while a share drifts downwards or sideways. Bare in mind that having a solid balance sheet wont stop a share from plummeting on say a profit warning.
For long term holds I like to use a back stop just under the 200 day moving average – I note that for MAB1, apart from around the Brexit referendum, it’s been above the 200 MA. Looks good to me. Good luck with it!
Hi ricky - Since you have mentioned Minervini, perhaps you should look into his advice on positioning before a major event.
In his books he states that "he never goes into a major event, such as earnings report, holding a large position".
If he has a large holding with a good cushion, then he top-slices significantly. If not, he sells his entire holding and re-considers his position post event.
I have adopted this method for some time and it has saved my bacon on quite a few occasions - an excellent risk mitigation strategy
Hi Ramridge - I have considered selling prior to an event but would have missed out on a number of 15% plus rises, do you keep a record of the net effect?
Regards
Ken
Hi Ken - Unfortunately I haven't kept detailed stats to work out losses vs gains over a given period.
I should really. I have been using this strategy for about a year (not on all occasions), and all I can say is that it has been on balance profitable and saved me from two profit warnings.
Whilst I've a lot to learn, one must understand the difference between a trader & investor. Selling an entire holding or 'top slicing' to take a lot off the table is a huge mistake I have made whilst investing. Often my ideas, thoughts, research and 'gut' have been proved right time and again. It is this supposed 'strategy' of taking money off the table that has damaged my returns.
When I invest in companies, i.e. own the stock, I am looking at the next 5yrs minimum. I have learnt the hard way that to try and time the rise and falls is not for someone who wishes to play the long game.
That is certainly not to say money is not there to be made trading, and indeed I use spread betting for this purpose. My strategy, however, often varies dramatically from Mr Minervini. When do I believe there is most to gain on the upside whilst keeping my position open for the shortest time period? Trading updates! However, this requires careful entry, sensible risk management and significant research. This is certainly not for the faint hearted.
One Man's Risk mitigation is anothers diminished returns.
IG
Hi Ramridge
You’re quite right. I remember reading that section in Minervini’s new book where he mentions it’s a “crapshoot” holding into earnings. I recently sold out Frontier Developments (LON:FDEV) last week at 1090p as I didn’t want to hold such a large gain (over 200%) into results and it looked very extended from the last base to me. If I were psychic I would have held as the shares are now 1300p! Can’t win em all! If it didn’t look so extended I don't think I would have sold the whole position.
The problem is some major events are unscheduled. Unlike scheduled results – some trading updates and other news are unexpected; I wasn’t expecting the UPGS update today and if it wasn’t for my auto stop I would have woken up to large loss!
I don't hold FDEV but if I did I would have looked at the charts. If something is going wrong there is often some selling. There was no indication that anything was amiss in this case so I would have held. That doesn't mean you can't have a stop loss in place.
Hi doublelutz
I agree, there wasn't any indication that something was amiss with FDEV. The problem is, I've seen shares gap down 20% or more on results after being so extended. It had ran up nearly 100% from the last base in the 600s. Better to be safe than sorry for me.
XLM - Paul has been a bit sceptical on this previously but it is one that I found very interesting and am now sitting on a good gain. It was the very good dividend allied to possible growth in the internet field that attacted me. I also took the gamble that not all Israeli companies can be bent and this one always had money in the bank!
There used to be questions as to who their clients were. Today there is a webcast on the company website which explains in some detail how they go about their business.
UP Global Sourcing Holdings (LON:UPGS) I was fortunate enough to only lose 8%. My auto stop loss got me out at 167p at the open. Bought the breakout in early May at 177p. Another example of the value of auto stops for me. My fantasy portfolio wasn't so fortunate though :(
I sold out of UP Global Sourcing Holdings (LON:UPGS) some months ago, too many warnings from retailers about fall in £, inflation etc. so not a sector I feel comfortable about.
Fulham Shore (LON:FUL) I also ditched. Sometimes you have to get out early. I don't run auto stop losses.
Hi Herbie
Well played on both UPGS and FUL. I’ve removed both from my Minervini inspired fantasy portfolio. FUL shouldn’t have even been included as it didn’t meet his criteria (serves me right for trying to get in early!)
I share your concerns about retailers but the last UPGS results looked like it was performing strongly nevertheless. Incidentally, I was within a whisker of being auto stopped out at 175p back in July and [wrongly] gave it the benefit of the doubt after. At least it was only a few % and some time lost.
I’m still holding FUL in my ISA. It’s the only stock I hold for sentimental reasons (and it shows, being down 30%). I’m Italian and I visit with family who are friendly with the staff. Other members of my family are shareholders too. Long term I hope it will bounce back though I think it will struggle short term.
CALL reported today, a company that Paul has covered in the past. Looks like they're approaching breakeven, the q is whether they can do so without further funds. If time permits, I'd appreciate your opinion.
Hi, I follow Cloudcall quite closely and have an investment in it. My personal opinion is that they will need to raise a bit more money ahead of cash breakeven and I think the appointment of a second (joint) broker is perhaps a clue there. However growth is coming through very nicely and I think the market would be supportive of any cash call. Note Blackrock bought recently in the secondary market to initiate a holding which I think is very positive.
The fact that the bulk of their revenue is recurring and very high margin I think makes this a very interesting company. Personally I think their existing traction supports the share price even if a smallish cash call is required.
Regards
Andrew
The Interquest (LON:ITQ) saga is really shocking. Daylight robbery. I can't understand why Luke Johnson, a man I have respected and admired for many years, would actively associate himself with such morally depraved bunch.
The Interquest (LON:ITQ) justification of their actions is a joke. At the very least it would suggest deep negligence of the board not to have ratified another NOMAD in time, and so what may be arguably a self-serving justification could prove an Achilles heel if someone takes action against them. It certainly does not help AIM's reputation that the regulators are so toothless.
It makes me wonder what has really been going on behind closed doors. To be honest, I don't know how The City works, but this one smells really fishy, even to my nose.
I can only presume that this is a stinking bad company, and Panmure decided that it would much rather retain its reputation than take a fee, and that other potential advisers have decided likewise.
It's just my uneducated guess, of course. We're never going to find out for sure, of course.
That is odd, because most recruitment companies seem to be flying high at the moment.
Bizarre.
Bizarre is one word, outrageous is another, particularly considering that in a recent vote to de-list the company they failed to secure the requisite minimum 75% of votes for shareholder approval.
Yes I remember realising that Interquest (LON:ITQ) was the only reasonably ranked company at that show. It made me wonder why they were there (and whether their good rank was misleading) - as most of the companies present were fairly speculative and pre-profit. Not necessarily bad companies (or indeed bad investments) but tending to need more capital and exactly the sort of companies I'd expect to have low Stock Ranks.
In terms of today's news the results from Servelec (LON:SERV) aren't being taken kindly by the market - problems being admitted despite the overall results being positive. And results from Cloudcall (LON:CALL) not generating much interest. That story is looking increasingly positive IMHO, but there's a good way to go yet. I hold both, but my Servelec (LON:SERV) holding is pretty small (and has got smaller today!).
Am also interested in XLM please... and EKF still look to be trading well too.
As an aside, anyone know why TON is drifting down and down on no news? I thought the last interims looked great.
TON fall could be due to exposure to Korea?
I second the request for your thoughts on XLMedia, also one of my holdings.
Thanks.
Graham, I'd second the request for XLM interims out today. (I hold). Good to see decent organic growth after the last three 6 month reporting periods had seen static revenue. With recent acquisitions kicking in more from H2 and into 2018 then bodes well. Diversifying their business away from gambling which I support. Excellent divi too although I'd be happy for them to pay less and reinvest the balance into higher return on capital acquisitions. Israeli co on AIM so don't think it will ever get the rating it deserves but maybe over time it will improve.
Thanks
Interquest - I met the CEO I think at the UK Investor Show I think a year or two ago. The stock was apparently one of the only ones at the show that came up as quality on the Stockopedia ranks at that time. The pitch was as a specialist and high margin IT recruiter. Personally, I am not a fan of recruiters and so didn't look at it. It is interesting that Interquest scored well with the Stockopedia system at the time. Although this was relative to the low quality stocks at the show.
It was particularly interesting to talk to the CEO who was very optimistic and confident and gave a good impression. A few weeks later there was a huge profit warning. It shows the risk of talking to management. Or rather it perhaps shows the vulnerability of businesses with little revenue visibility i.e. trading is dictated by the short-term demands of clients/customers.
What has happened at Interquest is part of a pattern of a number of AIM companies abusing the lax regulation. Some of the things that happen on AIM are mind boggling and don't appear to be legal. Personally I would just move on. It is pretty staggering what Interquest are doing but that is the AIM market for you. The crux is you have to find AIM companies that have high internal standards as they aren't really regulated externally.
Hi Graham,
Is there any chance you could look at XLMedia (LON.XLM). There interim results look really good as far as I can tell. I am long in this stock at the moment.
Cheers,
Hi Tony et al, XLM is in there now. Looks good to me too.
Regards
Graham
Thanks Graham, much appreciated. I will continue to hold.
Cheers,
Tony
UPGS another company recently IPO'd which has delievered a shocking trading statement only a few months into their listing. Thankfully I held this in my fantasy portfolio and not invested but I'd be seeking a sit down meeting with the company if I were a holder.
Hi Graham. Sounds like you have a lot on your plate today but if you have time I would be interested to know your thoughts on Lightwaverf (LON:LWRF) . It's a small micro-cap who focus on home automation. They are at the speculative jam tomorrow end of the spectrum but they have a very interesting product in an area of the market that is clearly going to grow a lot over the next decade as people inevitably get lazier.
I second that FoolishBen. I have been monitoring LWRF for a while now and it seems, following earlier supply issues, they finally look ready to make a breakthrough.
Hi Graham, if you or other readers could share views on Versarien (LON:VRS) I'd appreciate it. Is graphene about to finally make some money now that it can officially only be designated 'graphene' if it's 10 layers or less thick? The parma ham of new materials.
Hi Graham,
Could you please have a look at Luceco ($LUCE). You have discussed this one before. LED lights etc manufacturer -seems like good growth figures with growth in multiple markets and reasonable debt.
Thanks
Covered it,
Cheers
Graham