Small Cap Value Report (12 Dec 2014) - BEG, HSP, TET, POS

Good morning! The oil price continues to plummet. I was discussing this over lunch with other investors yesterday, and the striking thing we noted is that supposed experts, commentators, economists, etc, pretty much all failed to predict that the price of oil was about to collapse. How can this be? So what exactly is the point of employing such experts, if they fail to predict a gigantic move in the price of oil?
The resources sector is not an area I normally look at (and on the rare occasions that I break my own rule, it nearly always ends in disaster). However, there must be value starting to crop up now, or will do shortly. Over-supply leading to a huge fall in price will inevitably increase demand, same with anything, so the oil price should automatically go back up at some point once demand begins to out-strip supply again. Therefore I'm beginning to research some potential opportunities in the oil services sector.
Begbies Traynor (LON:BEG)
Share price: 43.75p
No. shares: 91.5m (+13.1m new Placing shares to be issued)
Market Cap: £40.0m
Interim results for the six months to 31 Oct 2014 are out this morning. They look lacklustre to me, with adjusted profit down from £2.3m last time, to £1.9m in H1 this year. So not a disaster, but not great either.
The insolvency practitioner says that corporate insolvencies (i.e. its market) were down 16% against last year, so with that in mind the results are actually quite reasonable. Cost control and some small acquisitions have helped. It strikes me as a well run business, owner-managed effectively.
Dividends - the interim divi is maintained at 0.6p. The full year payout is forecast at 2.3p, so that's a generous yield of 5.3%, although note that the bid/offer spread could easily absorb your first year's divis, so it's probably not worth chasing for yield unless you have a good broker who can buy at nearer the Bid price than the Offer price, and/or if you intend holding for the long term.
Outlook - the company today says:
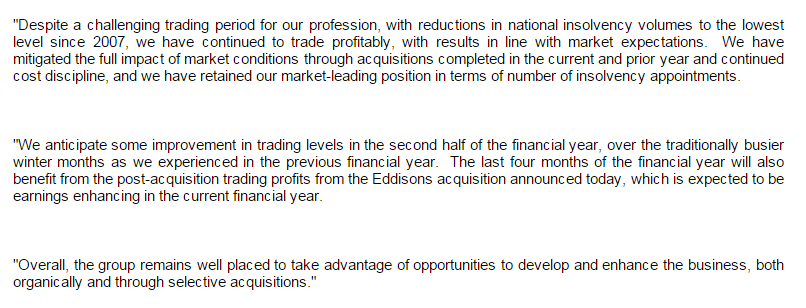
I like that they specifically say they are trading in line with market expectations.
Valuation - this looks reasonable value, in my view:
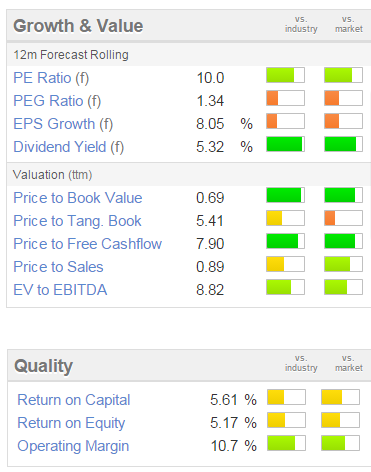
Note also that BEG scores highly in Stockopedia's own ranking system, with a StockRank of 93. That gives me some comfort too.
Acquisition & Placing - also announced today is a £5.3m Placing, to fund an acquisition of Eddisons, a chartered surveyors & valuers, which looks a sensible bolt-on business (as insolvency practitioners use their services a lot), with £0.5m of cost savings having been identified.
The price of the Placing is 40.5p, which raises an eyebrow, since the discount is probably a tad too generous, thus disadvantaging existing holders who have not had a chance to participate.
My opinion - this looks a well run business, doing OK in a very tough market. At some point it will benefit from an increase in insolvencies, but nobody knows when, and we've been waiting 6 years already for normal conditions to return, but they haven't yet.
The shares seem reasonably priced, so I quite like it, but don't currently hold any.
Hargreaves Services (LON:HSP)
Share price: 600p (down 92p today)
No. shares: 32.9m
Market Cap: £197.4m
Trading update - the company confirms it is trading in line with expectations for H1, so it's a bit surprising to see that the shares are down heavily. However, there's a lot of other detail in today's update, e.g. the closure of their Monkton facility, and coal markets generally.
I've given up trying to analyse this company - it's too complicated, and there are too many unknown factors, such as future energy policy, coal prices, etc. Although as a dirty fuel, the pressure is relentlessly against coal, and hence against this company in the long run, which they accept and are very open about. So it's almost impossible to value, as you don't know how long the profits will last.
I prefer to stick to simple, small companies, which can be readily understood in about 10 minutes, and where you can be fairly sure the company will be able to continue in operation for the foreseeable future.
Treatt (LON:TET)
Share price: 140.5p
No. shares: 51.5m
Market Cap: £72.4m
As it's quiet for results today, I'll circle back to this share, which reported results for the year ended 30 Sep 2014 earlier this week, on Tuesday.
The company seems to have come in slightly ahead of forecast, delivering just under 10p adjusted EPS for the year. So that puts them on a PER of 14. It was a good increase on the prior year's figure of 8.6p.
I like the decent operating profit margin here, which is just under 10%.
What puts me off is the narrative, where it talks of substantial capex being needed:
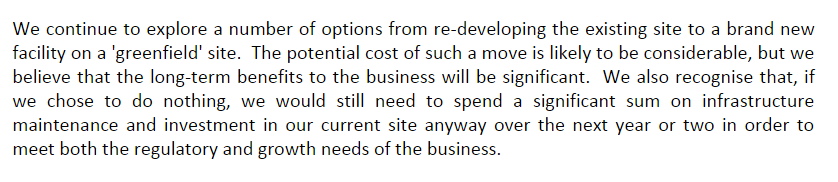
So it would be important to get some figures on this, and how the company is intending to finance it. Also, I am wary of disruption & unforeseen costs that such a relocation would be bound to cause.
Although, as the company points out, it has doubled profits in the last 5 years, which is good going. It doesn't scream value at me, but seems a good quality company that might be worth doing more research on perhaps?
It's the type of thing I would probably only buy if something went wrong, and there was a profit warning. I can't really see the point in buying things that look fairly valued. I want them when they're cheap!
Plexus Holdings (LON:POS)
I've been sniffing around this share, which has plunged in sympathy with the whole oil sector. They make some kind of innovative sealing mechanism for well heads, from what I can gather. It's always looked terrifically expensive, but after recent falls the price doesn't look quite so bad now.
AGM statement - I'm not sure what is reiteration, and what is new in this announcement, but I'm intrigued by the talk of doing a global roll-out for the product, which has been successfully used mainly in the North Sea so far I understand.
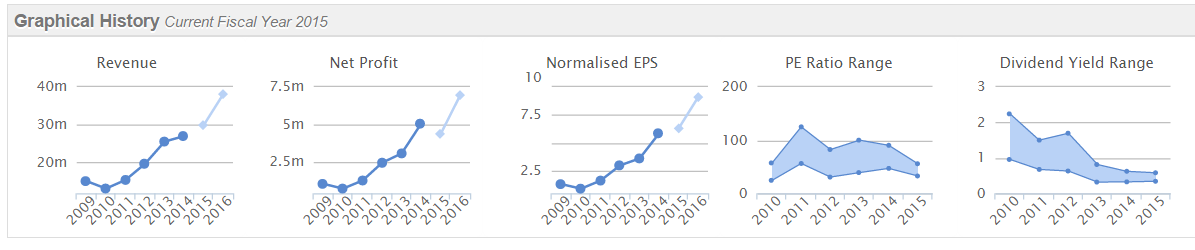
It's already profitable, and the Stockopedia graphs below are pointing in the right direction!
I appreciate they might suffer in the short term from the lower oil price, but it's not as if the industry is going to shut down, is it? So any cessation in capex will only be for the short term. Look through that, and this could be a good time to be buying quality companies in the oil services sector? Anyway, at first glance, I like the look of this one. Would welcome readers views if you know the company.
Got to dash, more meetings today.
Have a great weekend!
Regards, Paul.
(of the companies mentioned today, Paul has no long or short positions.
A fund management company with which Paul is associated may hold positions in companies mentioned)
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

9 comments
Hi Paul, I'm a long term holder of the oil majors but certainly wont be looking to top yet. Perhaps in a few months as other comments have suggested. I dont think the smaller exploration companies will tempt me (though I am quite fickle) but I'm getting excited for a few of the engineering / services firms that are highly oil exposed and traditionally highly rated by the market. e.g. WEIR and AMEC.
I was also going to mention GMS but others beat me to it. It does have a lot of debt though so may not be for Paul. How ever views would be welcome. AMEC is another I like long term and bought a few today.
On a pure oil play Ithaca Energy is worth a look. Oil price hedged at $90 ish for a large part of its production until June 2016. Net debt is high as the Stella field comes into production next year. As always it's a risk .
Hi Paul
I hold some GMS - picked up last week. I think the fall has been massively over done given there is consistent positive news flow and the outlook is good in my view.
I tend to avoid resource stocks these days having been bitten previously but I am minded to pick up one with a view to generating a good return. I have my eye on $AFR which is now sub 40p and Dragon Oil (LON:DGO) which pays a dividend.
Cheers
Ric
paul, with regards to oil price and oil companies , I wouldnt rush to buy in. Of course oil will rebound but I would suggest the rebound will take time. There is no driver for an increase in oil price soon. demand is dropping and the marginal priced oil on the market wont disappear tomorrow. Some producers will sit this out for months. OPEC are becoming less of a threat too. They are already breaking their quota of production and some of their members dont adhere to the plan.
I dont think were at the bottom yet but I also envisage a new oil range of 60-80 over next couple of years.
I remember i read an article about how much froth was in the oil market with regards to speculation and trading. $20-$30 was speculation/trading from memory. That looks about right now given the crash in the price.
its a wonderfully complex market imo.
Look 6 months down the line for bargains imo.
I'm short OIL for now and looking to buy a few oil related shares stocks in the future too but not just yet.
I'd appreciate a quick kick about of oil services companies, if they' re on-topic today: the only one i looked into lately is Hunting, which has opened up a number of new manufacturing plants in various countries, just in time for this oil crash. The management were confident in the extreme about the demand for their products on the last webcast I listened to (ie pre crash. To what extent overconfident i dont know. I wonder if that confidence and capex was widespread in the sector. GMS were expanding their fleet of lift boats also I think.
As Paul says above, oil isnt going to get easier to extract, so long term..
GMS are expanding their fleet by 60%. It's market forces at work - supply increases (mainly due to US shale), price decreases : high cost producers go bust and CAPEX on marginal high cost wells gets shelved - supply therefore decreases and price once again increases.... round and round we go! Amec Foster Wheeler (LON:AMFW) is probably a good bet because it is more diversified than the other pure oil service groups i.e. AMEC is involved with Nuclear, Water, Power, Mining, Transport, Industrial etc.
hi Ben !
Morning Paul. I decided to sell out of Begbies Traynor (LON:BEG) earlier in the week when they announced that they were changing the date of the report from Thursday to Friday. I was a bit spooked - as often bad statements are released on a Friday. Anyway, It's one I made a profit on so I can't complain. I will continue to watch and possibly look for a re-entry at a lower price in the future.. Many of the Oil service stocks are looking exceptionally cheap: Gulf Marine Services (LON:GMS) would be a reasonable buy at these levels as their Self Elevated Support boats actually help Oil Companies save money and therefore demand could increase for their vessels in a lower oil price environment. The CEO stated on the 5th of November:
"As we discussed in our Interim Results, demand for our SESVs across the MENA region is excellent and the market for our assets in Europe also remains strong with our entire fleet of ten SESVs currently chartered. Our backlog has increased by nearly 50% since August with recent contract wins. Our clients are responding to the low-cost benefits that our SESV solution provides them, which is increasingly relevant in the current oil price environment. The outlook, driven by our core brownfield (opex-focused) oil and gas client base, underpins our expectation of continued strong demand going forward. This, together with our ongoing new build programme, will help to maximise opportunities with existing and new clients."
Gervais Williams holds some in his Smaller Companies Fund.
I would also take a look at the larger players such as Lamprell (LON:LAM) , Petrofac (LON:PFC) , Hunting (LON:HTG) , £WG and Amec Foster Wheeler (LON:AMFW)
Have a good weekend - and lets hope the markets perform better in the run up to Christmas!
Hi Paul
A minor question about Begbies - they have announced their interim dividend today, but don't pay it until May! Why do some businesses pay promptly, yet others think it's fine to delay for 5 months?
Andy