Small Cap Value Report (12 Jan 2016) - SPD, KBC, BOO, AVS, BOTB, MCB

Good morning!
I'm overwhelmed with the volume of results & trading updates today, so will do my best, but this report will probably take the rest of the day to write! So I might have to cut some corners, to cover all the companies reporting today.
Reports of the death of retailers seem premature, with surprisingly upbeat statements from both Debenhams (LON:DEB) (I hold a long position in DEB) and WM Morrison Supermarkets (LON:MRW) today. It's interesting to note that, in both cases, the market did not correctly anticipate that recent trading would be alright - the pessimists were wrong. This seems a pattern at the moment - i.e. that price movements on the chart really are not proving good indicators of company performance at all, and many glaring anomalies have appeared - creating buying opportunities. I'm drawn like a moth to the dim lights of companies surrounded by investor gloom, as selectively you can find lovely bargains, if you avoid the value traps (not always successfully done, by any means, but I'm getting better!)
I've been filling my boots c.400p this morning with Sports Direct (SPD) shares - the dramatic sell-off seems greatly overdone, perhaps because tracker funds might be selling ahead of it dropping out of the FTSE 100? This has combined with a mild profit warning, and numerous press articles attacking the company's pay & working conditions, and general corporate governance issues relating to Mike Ashley's tenuous grasp of (and/or disdain for) the requirements of being a publicly listed company. Him owning 59.4% of the business creates a lot of problems. All of which is great from my point of view, as I'm only interested in it being a fantastic business, that is now very cheap in my view. As always, this is just my personal opinion, I'm not giving recommendations, just chewing the cud on things that look interesting to me. DYOR is the whole ethos of this site remember.
KBC Advanced Technologies (LON:KBC)
185p cash takeover - this looks a done deal, with 42.6% acceptances already secured from Institutional shareholders. Well done to KBC shareholders, this is an attractive exit price (a 49.2% premium to last night's closing price), and all in cash too.
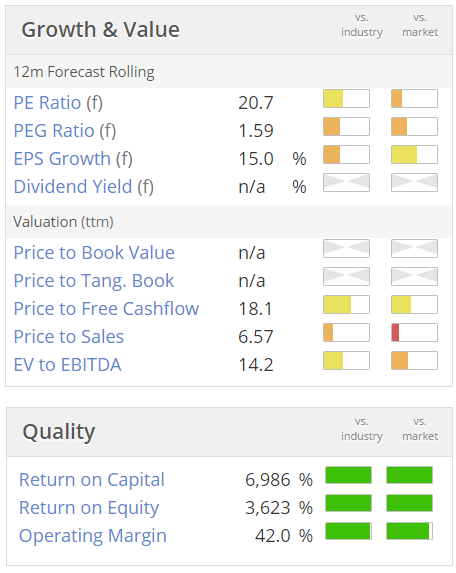
The buyer is a subsidiary of Aspen Technology Inc (NSQ:AZPN) which you can check out using the graphics we're familiar with (on the right), if you have the US edition of Stockopedia.
Aspen has a StockRank of 88, and has amazingly high quality scores, so its fwd PER of 20.7 is perhaps justified.
Note how it's another example of a larger US corporation buying a UK business, in order to drive growth. This is an established trend now, and I suspect we'll see more such takeovers happening. US corporations need to do more than just share buybacks with their surplus cash, so it seems they're exploring overseas for bolt on acquisitions.
Boohoo.Com (LON:BOO)
Share price: 39.5p (up 8.2% today)
No. shares: 1,123.1m
Market cap: £443.6m
(at the time of writing, I hold a long position in this share)
Trading update - this is the one people are really interested in! I know that a lot of readers also hold this stock, as do I - it's my favourite company on the market, as a long-term hold.
Here are the figures, with my highlighting of points drawn out below;
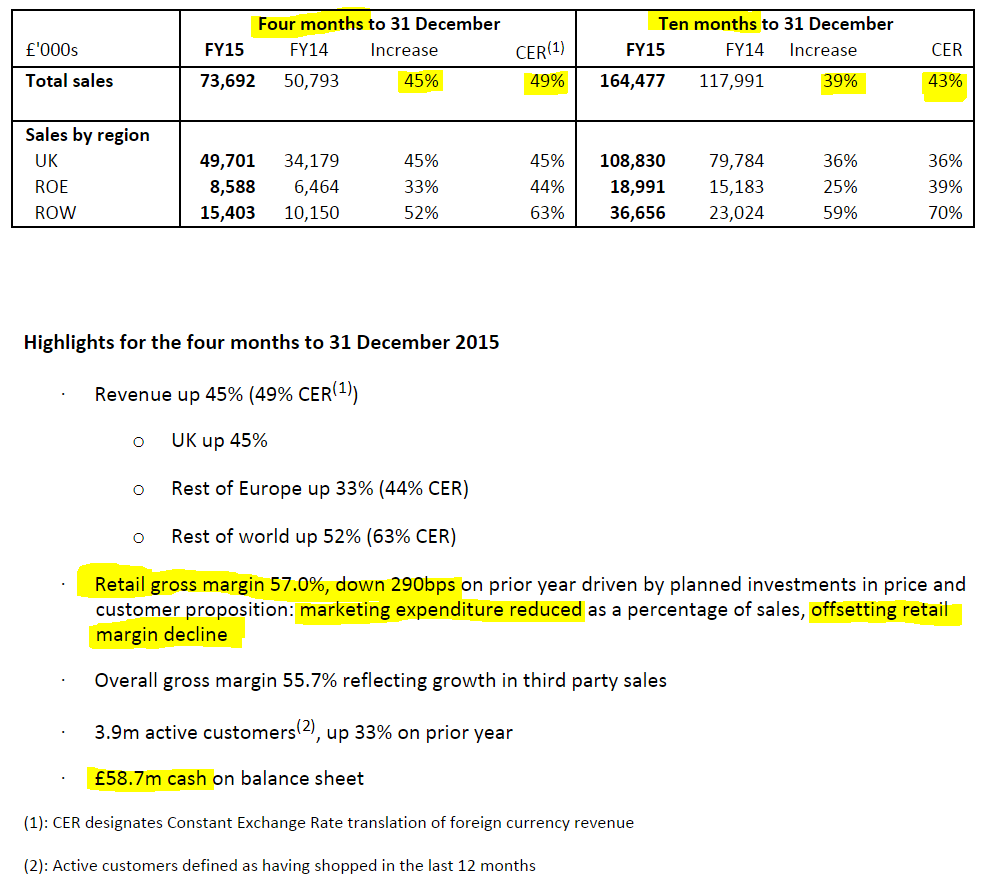
My comments - excellent sales growth, with the 4-month H2 sales being up 45%. That's a marked acceleration in growth, since in H1 sales growth was +35%. Blending the two together, gives 10 month YTD top line growth of 39%.
This is fantastic growth, as it's all organic. How many businesses in your portfolio are achieving this rate of organic growth? Not many, I bet. This is why the shares are on a premium rating, which they fully deserve in my opinion (and then some). Growth companies are never cheap, so it's a red herring to obsess about the PER when growth is this strong. I thought Asos looked ridiculously expensive when it was £3.50 per share, and it went on to 20-bag! (since come back somewhat, but still about 8-9 times that level. Rapid growth at good margins can transform a business in just a few years, so you have to look forwards, not backwards, when trying to value it.
Gross margin - I had a battle royale with Tom Winnifrith late last year, when he published a bearish note on BOO. So I felt compelled to visit him, and give him a 3 hour lecture in person, about online retail margins (over pizzas and a bottle of prosecco). He described this the next day as akin to being waterboarded! He backed off largely to avoid another of my lectures I think, lol!
Tom's suggestion was that BOO's very high gross margins were unsustainable. So no doubt he will be claiming to have been correct all along, as BOO's margins have indeed fallen, by 290bps to a still very respectable 57.0% at the retail level, and 55.7% overall - lower because it includes wholesaling activity, which is obviously lower margin - BooHoo products are now sold online on Asos, and Next Directory, so the brand is expanding beyond its own website.
What has happened though, is that BOO has made a policy decision to give customers better value for money. This is because sales are highly elastic - you reduce the selling price, and demand greatly increases. This is 100% the right strategy. By giving away a bit of its margin to customers, BOO has achieved very high sales growth, gaining market share, and making life more difficult for competitors.
BooHoo's key competitive advantage is its long-established supply network, which is global. The business was set up by experienced rag traders, with decades of experience & contacts. So the company can source very keenly, and also has very little markdown due to its "test & repeat" business model. It therefore has a huge advantage over bricks & mortar retailers, and can undercut them on price, whilst still achieving a very respectable margin.
Marketing - I was a bit worried that BooHoo might have been spending too much on marketing. At the peak, it can hit 17% of turnover, reducing then to c.10% later in the season. That's a massive spend, and can I think be a case of reducing marginal returns. It's far better to do what they are doing now - cut the prices, and recoup that profit from reducing marketing spend. It's working, and gets a big thumbs up from me as the correct strategy.
Full year outlook - sounds confident;
We remain confident of trading in the remaining two months of the financial year and now expect revenue growth for the full year to be marginally above previous guidance of 30% to 35%. We are trading in line with current market expectations for EBITDA as we continue to invest in driving growth and building market share across our key markets."
EBITDA is a fashionable metric at the moment, but bear in mind that the warehouse facilities have been greatly expanded, so there will be a higher depreciation charge each year.
The key message however is that the business is trading in line with expectations.
My opinion - this is a reassuring update. I am pleased that the company is going for growth, and is driving this by giving customers better value for money. That is the right way to build the business.
I see this being a very much larger business in 5-years, so for me, it's a hold almost regardless of what the current PER is. PER is not a reliable way to value rapidly growing companies. In actual fact, BOO is not outrageously priced at all compared with other growth companies, especially when you deduct the nearly £60m in net cash from the market cap.
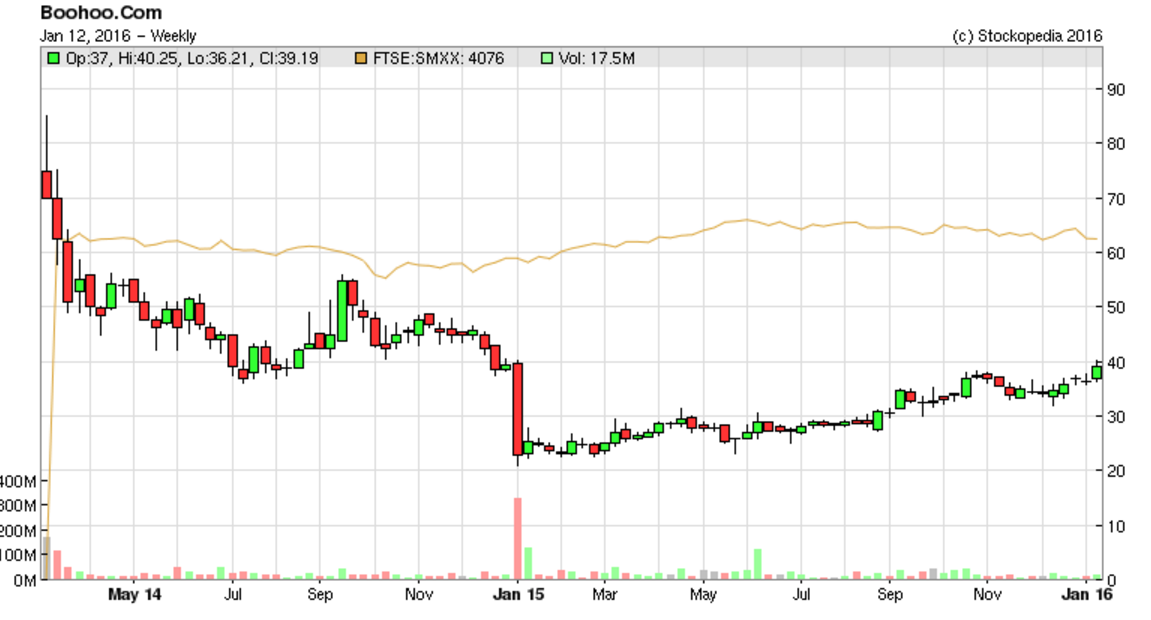
As with all growth companies, if anything serious goes wrong, then it's a long way down - as Instis who bought in the IPO discovered a year ago. In my view though, the expectations set at IPO were too aggressive, and the subsequent profit warning in Jan 2015 was a once-only reset of expectations. Since then the company has recovered well, and investors who saw the buying opportunity a year ago have been handsomely rewarded so far.
In my view this share could be above its original IPO price of 50p in the not too distant future. Note that there are no divis as yet.
I see that the StockRank, which was very low, is rising - now past the halfway cut-off, at 52. With this good update, and continued share price strength, I expect the StockRank to rise further, as the growth & momentum scores continue to offset the value score.
Avesco (LON:AVS)
Share price: 237p (up 11.5% today)
No. shares: 19.1m
Market cap: £45.3m
(at the time of writing, I hold a long position in this share)
Sale of freehold property - regulars here will know that I love freehold property. Why? Because freeholds;
- are hidden assets that can often be thrown in for free (many investors don't even notice that freeholds are owned by companies they invest in)
- can be sold when cash is needed
- go up in value over the long term usually
- banks are happy to lend against freeholds - so usually won't withdraw lending facilities even if trading is poor, if they have security over freehold property.
- can attract takeover approaches
As I pointed out in my report here of 11 Jun 2015, the company's freehold property (several acres used by its Fountain Studios subsidiary) had hidden value;
"Freehold property - this is in the books at depreciated cost, of £6.8m. I've heard that the open market value of the group's land assets could now be significantly above book value, but you would need to DYOR on that, as I have only heard it secondhand, verbally, from a friend who looked into it a few months ago. - See more at: http://www.stockopedia.com/content/small-cap-value..."
The good news is that this property has been sold, for £16m (that's 35% of the group's market cap), so £9.2m above book value - which will be booked as an exceptional profit to this year's results, no doubt.
Moreover, this will not impact trading in any way, since Fountain Studios is actually loss-making, turnover of £5.3m, and a £0.3m pre-tax loss for the year ended 30 Sep 2015. So a double benefit from this property disposal.
Net debt for the group was £17.5m at 30 Sep 2015, so this cash receipt of £16m wipes out all but £1.5m of the net debt - an astonishing transformation of the group's financial position. It will of course also wipe out a hefty interest charge from the future P&L, thus improving earnings.
So a terrific development, and I'm surprised the share price only rose 11.5% today - perhaps the news hasn't really sunk in with investors yet?
Results y/e 30 Sep 2015 - I must admit to finding these figures very confusing, not helped by the fact that the broker note uses a different calculation of EPS (adjusted, fully diluted) to the various versions given with the results.
There are large exceptional items in both years, plus profit from discontinued operations (release of provisions from the Disney litigation). Overall then, I'm going to have to spend more time dissecting the numbers properly, probably over the weekend.
What Avesco calls "trading profit" rose from £6.25m last year, to £7.36m this year, so a rise of nearly 18%. The group is a bit of a sprawl of various subsidiaries in different countries, but to my mind the investment case should focus on the jewel in the crown;
CT USA - this business looks very exciting. It is the "main profit driver" in the group. CT in Europe performed better too, thanks to reduced costs in Germany (which had been heavily loss-making). I was very impressed with the contract that CT USA performed, which turned the Hoover Dam into a giant projection screen, for the launch of a new Ford truck - see this link.
Companies, events organisers, sports, and broadcasters can do so much more with audio visual displays now, and clearly great expertise & experience, plus the right (expensive) equipment is needed. So I really like the niche that Avesco operates in, and this surely must be a good growth area, as the figures today suggest.
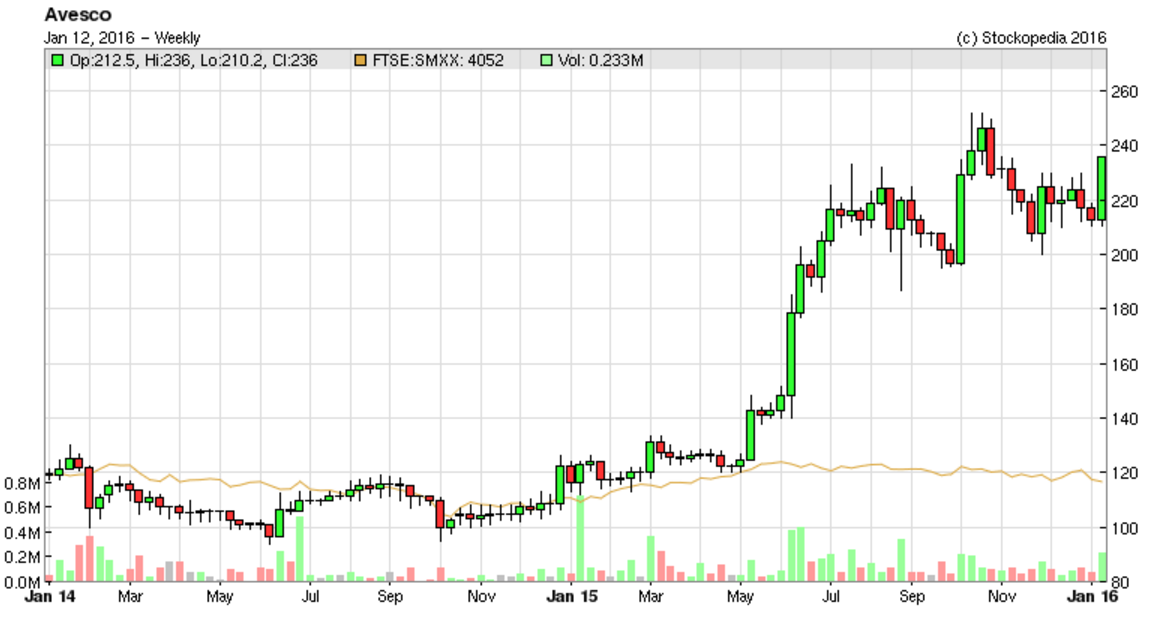
My opinion - with net debt now almost paid off, from the property disposal announced today, and the CT division having made a £9.1m profit in 2014/15, an "odd year" - i.e. when profits are meant to be relatively subdued, due to the timing of big sporting events falling into even years, then I am struggling to see why Avesco is only valued at £45.3m. The problem seems to be that the superb performance of CT is diluted by other marginal businesses within the group.
In an ideal world, I would like to see all other businesses divested, and the group renamed Creative Technologies. That could well trigger a decent re-rating. With Fountain Studios being closed down & sold off, that process looks well underway already.
Note that the Chairman, who is past retirement age, will want to maximise the value of his stake, so I suspect the group is being optimised to get its valuation up, which is great for all shareholders. When he sold £1m of shares last year, the whole lot was bought by other Directors - that's a remarkably bullish signal, in my view.
FinnCap says the company did 25.4p adjusted EPS in 2014/15, and strangely they are forecasting a reduction in profit this year, despite it being an even year. So I suspect the company could thrash the current forecast of 21.6p for this year. Personally I have in mind nearer 30p adjusted EPS for this year.
So I remain very keen on this share, and think long-term it could end up significantly higher than it is now, providing nothing goes wrong, and we're paid generous divis along the way too. Selling the surplus property is a great move, that unlocks a dormant asset, de-risks the shares, and will enhance earnings due to lower interest charges. What's not to like?!
Stockopedia likes it too, with a StockRank of 96.
Best Of Best (LON:BOTB)
Share price: 175p (up 1% today)
No. shares: 9.7m
Market cap: £17.0m
(at the time of writing, I hold a long position in this share)
Interims to 31 Oct 2015 - this company runs the win a supercar competitions at UK airports, but is also now becoming increasingly an online business - online now accounts for 66.5% of revenues.
Revenue growth is reported today at 30%, to £4.98m for the 6 months, which is encouraging. Although the additional gross profit of £0.5m was nearly all ploughed back into increased marketing costs, to drive new player acquisition.
Therefore profit before tax only rose from £431k in H1 LY, to £478k in H1 TY. I'm a little disappointed with that, as I was hoping for a greater increase in profits. Although if the marketing spend drives faster growth in future, then it could turn out to be money well-spent. Time will tell on that.
Valuation - it looks as if the company is heading for perhaps 8-9p EPS this year, so the shares aren't cheap on a PER of between 19-22. That's a lot for such a small company. Although bear in mind that the balance sheet is strong, holding £2.2m of net cash, or 22.7p per share.
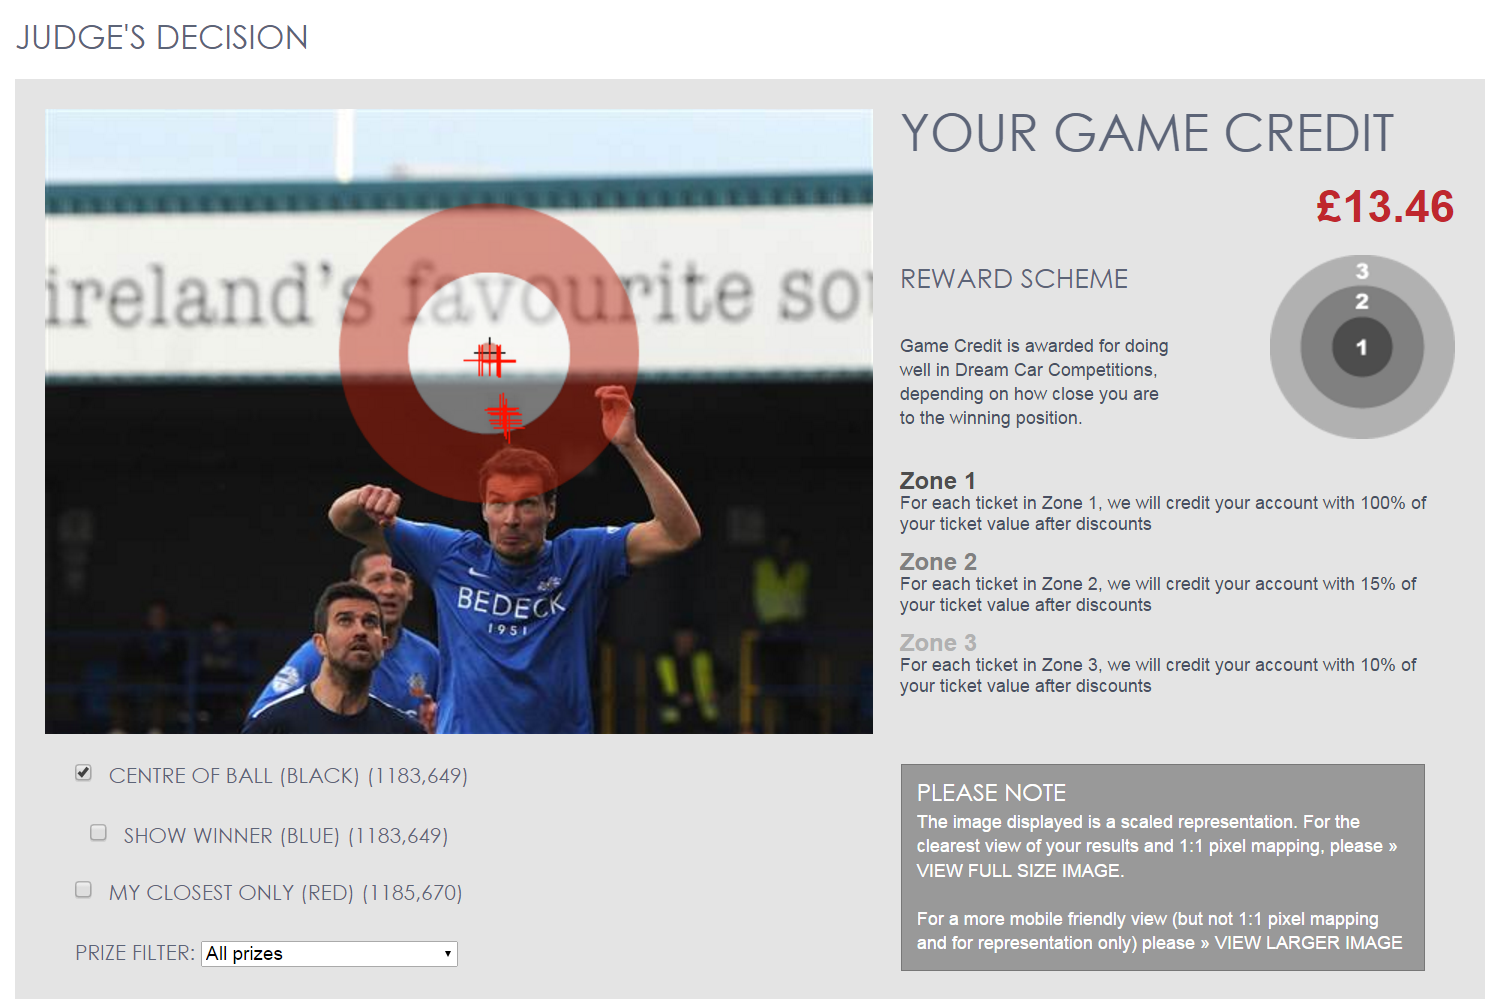
My opinion - I am a keen customer, and I play the online competition every week. It's enormous fun, as the concept is a spot the ball competition. I seem to get very close almost every week (see my result today, below), and a good proportion of my ticket cost is rebated in consolation prizes - I won £13.46 this week. This keeps you playing, as winning seems a realistic possibility, and you don't want to see your game credit consolation prize going to waste. There are also lots of special offers to keep things interesting. It's a genuinely interesting & fun competition, with real winners each week.
I am hopeful that the company might at some point really step up a gear, and see faster growth, e.g. with international expansion. It has done very well so far, in about 15 years of operating, and I see considerable potential here for a much bigger, international business. So far though, only small Indian franchises set up. Imagine if international growth, through franchisees really took off.
Even if overseas customers are playing via the UK website - I see this week's winner is a lady in St. Petersburg - although maybe she bought a ticket at Gatwick Airport?
Note that this share is thinly traded, as the free float is only 14% (about 1.36m shares, according to Thomson Reuters). So it can be very difficult to pick up (or sell) shares in it, which will rule it out for many people. I spent several months building up my holding here, very slowly, picking up scraps of shares as and when they became available.
CEO interview - I am interviewing William Hindmarch, the CEO and majority shareholder, on Friday this week. So if you would like to submit any questions to him, please use this link (NB please don't add any questions below here, in the comments section, as I may miss them).
William visits the competition winner every week (there is a guaranteed supercar to be won every week), and puts the videos on BOTB's website. This particular video is hilarious - where he accidentally detonated the firework the wrong way around - straight into his own meat & 2 veg! (from 2:35 onwards).
McBride (LON:MCB)
Share price: 160p (up 6.8% today)
No. shares: 182.2m
Market cap: £291.5m
Trading update - this maker of household & personal care goods has a 30 Jun year end, so it reports today on H1, being the 6 months to 31 Dec 2015.
Instead of telling us what we need to know - how the company is performing compared with market expectations - this update goes round the houses.
Group revenues increased by 0.4% on a constant currency basis when compared to the first half of last financial year.
Profits are benefiting from actions associated with business simplification, streamlining and cost initiatives, as outlined in the Group's new strategy. As a consequence, first half year underlying trading results will show further overall progress, in particular when compared to the first half of last financial year.
So here is my RNS translation service - turnover is down in sterling terms, but slightly positive when adverse forex movements are stripped out. Profit has risen compared with last year, due to cost cutting. We don't want to tell you how we are performing against management or market expectations, but leave you to assume that we're in line.
Valuation - broker consensus is for 9.91p EPS this year, putting the shares on a rather warm PER of 16.1. That seems a lot for a not particularly good, low margin business, supplying supermarkets which are in a cut-throat price war.
Balance sheet - note that Mcbride has a geared balance sheet, with quite a lot of debt, and a pension deficit. Although I see from the last Annual Report (note 15) that it has land & buildings on the balance sheet at depreciated cost, of £50.1m, presumably freehold property, which would make me much more comfortable about the bank debt.
The business is also quite capex-intensive, but this means that before capex, it is decently cash generative.
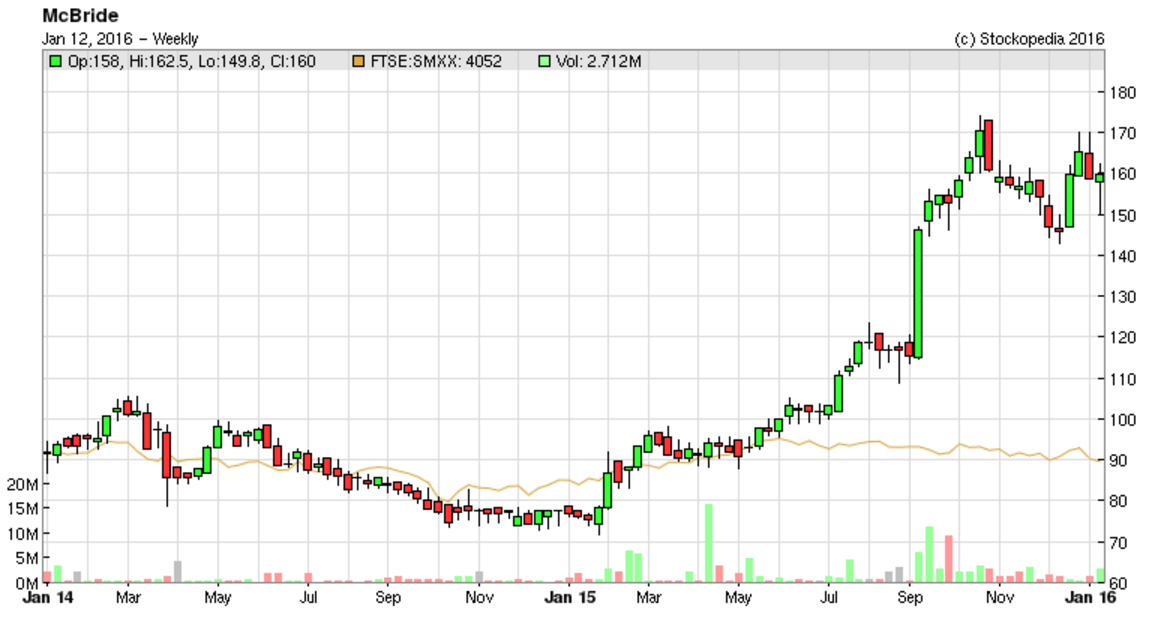
My opinion - the company has undergone a good turnaround, but the shares look up with events now, or even perhaps a tad too high? The trouble is that cost-cutting can only go so far. With not top line growth, and margin pressure from customers, it's difficult to see much scope for further profit growth.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

24 comments
Can't believe anyone here would play Best of Best, the odds must be at best 30p in the pound (if all the cost of revenue is used to pay for the prizes) with the pseudo easy game and kickbacks a simple trick to make everyone think they're geniuses. Reminds me of the old sat TV shows where you have to phone in a premium line to find the missing letter in FO_L for a minuscule chance of winning some trinkets. There are lotteries with much better odds around for folks who want a bit of randomness!
cig,
I play the BOTB game each week just for fun. It's tons better than the alternatives of just picking some boring numbers at random and watching them come out of a tombola!
I like the fact that BOTB does actually involve skill - you have to correctly anticipate where the panel of experts decide the ball was. Be as cynical as you like, but people playing the game enjoy it, and that's what it's all about!
Regards, Paul.
P.S. Plus, I bought enough shares in the company so that if it does what I think it could do, in the long term, I am more likely to be able to buy a supercar from my shares, than from the competition lol!
The FT's Lex column likes the look of Boo. The following links to a video discussion where the head of Lex is asked which internet stock he would choose if he had to pick one of Boohoo, AO World and Just Eat. He tipped Boohoo. Not that Lex has a fantastic record when it comes to share tipping but the fact that it even bothered to discuss the pros and cons of Boohoo will not have gone unnoticed by the heavy hitters in the investment community.
http://www.ft.com/cms/s/0/330c5138-b900-11e5-b151-8e15c9a029fb.html#axzz3x4AUWxHD
Hi Paul
In terms of the sale of Fountain Studios how much cash will Avesco receive. According to the Sale of Freehold property RNS they expect to receive a net profit after tax of £6m and cash of £13m, but according to the Post balance sheet note (9) in the FY accounts profit is expected to be £7m.
Best wishes,
Imran.
Paul,
If you and Tom Winnifrith made a single bottle Prosecco last three hours, I'm a Chinaman and you might like to invest in my sportswear company! :-)
Bought some SPD this afternoon at c.413p. I think it's a good buy.
All the best,
Steve
I appreciate that everyone has an opinion and it depends upon your own point of view as to which one is believed. Yesterday's article on the property bubble and todays report on the RBS market analysis in the Telegraph Business section came to mind as I was reading all of the above. At one time the cycle was blue chip then mid market followed by small company and finally junk with the cycle going in reverse for the bear. Did I read a mention of some confusing signs in the Aim market which Paul wrote about a couple of weeks ago? Anyway it would be interesting to hear everyone's / anyone's view of RBS telling the clients to head for the hills. My view " I am already there". But I was born bearish.
Ken
I'm probably missing something very basic here, but where has the cash gone with BOO ? At 31Aug they had 60.3 million in cash, and have spent (I think) 1.7 million on a warehouse. However, in the four months since the interims they've had a 73 million turnover at a margin of 50+ % - shouldn't that have added in excess of 35 million to the cash figure ? However they announce that they have 58.7 million.....
Maybe inventories are higher?
In principle yes, but for a company that prides itself on trying small samples first I doubt it - that would be a scary amount of inventory ! I also vaguely remember mention of them getting paid before they actually have to pay for the items...
Fishcake
"- shouldn't that have added in excess of 35 million to the cash figure ?"
Absolutely not thats just a silly number.
Lets start by looking at the broker forecasts for the year - they expect (and we expect presumably) that the company will make 15 milion profit for the whole year pre-tax
Take 20% off for tax - say £3 mill
and that leaves £12 mill for a 12 month period
This was a 4 month period so 4/12 of 12 = 4 million expected cashflow in a normal period
say a couple of mill for capital expenditure above depn charge
add in investment in stock that will be needed to cover turnover increases that could easily be a couple of mill.
They may if selling by third parties more also have an increasing trade debtor balance as they will likely be paid in arrears of sales date ??
So the nil positive cashflow is within a few mill of what i would expect - £35 mill is just a silly number. The finals when released will have the chapter and verse.
Unfortunately expansion always comes at a cost but if they are breaking even cashflow wise with 60 mill in the bank whilst expanding at a large LFL rate thats a good job done.
I am no expert but 19 mill invnetories per last accounts compared to 90 mill sales = one very tight ship in my books that i think would compare favourably with the likes of ASOS (just guessing)
The main danger is if there are funnies capitalised or exceptionals outside of broker forecasts when the final ye figures come in but i see nothing unduly wrong with the lack of positive cashflow at present. Job well done spending cash as necessary creating new/additional sales and future room for efficiency gains - you need to start off with over specc'd warehouse /website etc etc etc and grow into that. Amazon got where they are by re-investing all cash in expanding.
Thanks to rmillaree and Bezhe for taking the time to correct my beginners mistakes !
In reply to Fishcake's query on £BOO's cash position: The reference was to "gross margin" which is sales revenue less cost of sales but before overheads. The overheads, including marketing costs, are deducted from gross margin to arrive at operating profit. Hence, the retained profit (and resulting cash increase) for the period will have been much lower than 43% of sales. In addition, as Cisk has suggested, higher inventories and other movements on working capital can also depress the cash position.
(I'm sure that all of this will be included in the book that people are constantly asking Paul to write!)
Paul, Argos do same day home delivery.....
Paul, UK-quoted oil services stocks could well be looking very attractive now to US groups prepared to take a medium-term view and/or where there are synergies with their own businesses. Yes, there may well be yet one more leg down in oil prices but with NYMEX and Brent at just over $30, how much lower is there really to go? Add in the (to me) precarious position of Saudi Arabia, politically and socially, the tensions between that country and Iran, the still growing unrest caused by ISIL throughout the Middle East, adverse developments in any of which (imagine the main Saudi pipelines in their eastern provinces bordering Iran being blown up) could send oil prices racing upward, then throw in the present strength of the US$ against sterling, it's perhaps exactly the right convergence of events for the stronger to start eating up the weaker. So KBC going, no real surprise. I'd also now expect both Petrofac and Hunting, perhaps also Pressure Technologies to be on some US shopping lists.
My concern with oil prices is not going lower which seems unlikely but how long are they going to stay low, with a slow down in China and maybe elsewhere then demand does not seem to be going up, USA relies more on fracking now anyway. KBC is profitable and has no debt. Petrofac and Hunting now seem to be making a loss and carry quite a bit a debt. Of course you could be right but it looks a bit risky to me.
Hi Paul,
I note that Boo used margins to build volume, but I wonder if the RoW margins, i.e. Aust. NZ and some Asian markets, were more an issue of Sterling's strength up to Black Monday. Nothing was said in the update regarding exchange rates. However, the pound has been notably weak over the last month vis-a-vis USD which could be used to boost margins for remainder of the year and surprise on earnings in March.
CER is constant exchange rates, on CER sales inc. 49% as opposed to 45% (overall).
KBC Advanced Technologies (LON:KBC) shareholders, you lucky blighters. Also a 30% premium to its price at any point in last 10 years and a 20+ P/E. Nice deal, I'd be taking if I had any.
Hi Paul,
Thank you for the sound analysis day after day - it's a great help to the continual learning process. Quick question, any intention to take a look @ Ilika (LON:IKA) today? I notice they've put out thir half year today and I know it's in your list of blue sky shares you keep tabs on. Would be interested to know your thoughts.
Cheers
RT
Hi RT,
I'm trying to avoid blue sky shares, as my track record on them is so dismal - I get sucked into a good story, and end up losing my shirt on the shares!
For this reason, I try not to write about them any more here, as I don't want to inadvertently lead people up the garden path, if I get excited about a story stock again.
So I won't be covering Ilika again here, unless & until the company can demonstrate real commercial progress - i.e. proper, sustainable turnover, and profits.
Regards, Paul.
Good news on Boohoo.Com (LON:BOO), Debenhams (LON:DEB) & (apparently) Avesco (LON:AVS) today. I'm miffed about KBC Advanced Technologies (LON:KBC) though, as I sold my smallish holding last week in order to retain some profit. Grrr!
You just popping to Argos for some more HOME shares? ;)
Deleted.
Yup, already sorted.