Small Cap Value Report (13 Dec 2016) - BEG, CPR, ZYT, TSTL

Share price: 47.4p (-1.3%)
No. shares: 106.2m
Market cap: £50.3m
Half-Year Report (six months ended 31 October 2016)
 The
market is slightly underwhelmed with interim results from this
insolvency practitioner, results which the statement describes as
"solid".
Over the past twelve months, Begbies has been diversifying into property services. The insolvency market was taking too long to start moving again, and so the company decided to move into a related service where it hoped there would be synergies (property auctions often taken place during an insolvency process, for example).
The Exec Chairman anticipates that 30% of revenue and profit will arise from the property services division, in the current financial year.
Outlook:
"For the year as a whole, we anticipate growth in
earnings, in line with expectations, with the benefits of our investment
in property services complementing our market-leading, profitable and
cash generative insolvency business. We will continue to look for
opportunities to develop and enhance the group, both organically and
through selective acquisitions.
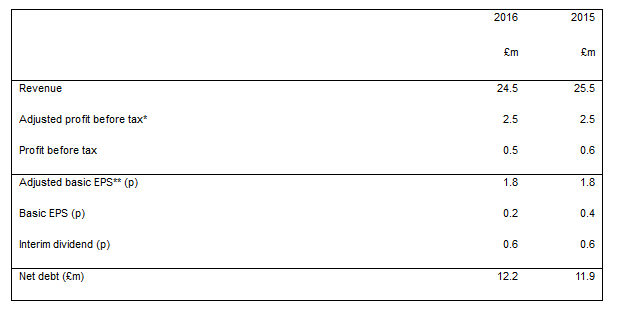
Dividend: interim dividend maintained at 0.6p.
The dividend payout has been flat since 2012, but the company would like to return to a progressive policy when possible:
The board remains committed to a long-term progressive
dividend policy, and to increase dividends when more confident of both
the market outlook and potential for sustained earnings growth..
Macro Conditions: The company is not predicting any improvement (i.e. for everyone else, a deterioration) in economic conditions. In terms of the total number of corporate insolvencies, it says "the market appears to have stabilised at this lower level", and "there are no expectations of an increase in insolvency levels".
No. of employees is reduced to 328 from 355, keeping the cost base under control.
Net Debt:
The company has a £30 million facility with HSBC. Net borrowings are £12.2 million, with total balance sheet borrowings of £17 million offset by £4.8 million of cash.
My opinion:
Overall, it looks like more of what we've come to expect from Begbies - a flattish result and a stable dividend.
While I've generally had a positive outlook on this company, which has been stable around the current share price for two and a half years, I am increasingly reluctant when it comes to investing in professional services companies - personal experience, and recent events at Fairpoint (LON:FRP), have shown me how dangerous to an investment portfolio they can be. Perhaps they are simply more suited to the partnership model.
In this case, £17 million of gross borrowings (nearly £50,000 per employee), combined with a series of acquisitions do make me a little nervous. Although that could be some recency bias talking, after what just happened at Fairpoint!
At least the founder Ric Traynor remains on board here. That is a very good form of reassurance for investors, especially considering that he owns 26% of the company.
 Carpetright (LON:CPR)
No. shares: 67.9m
Market cap: £136m
Interim Results (26 weeks ended 29 October 2016)
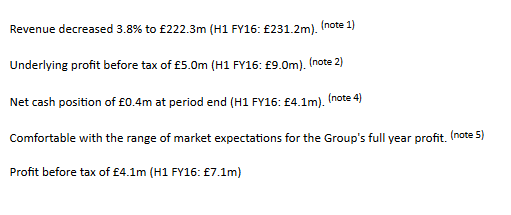
Tricky conditions for Carpetright, reporting "uneven consumer demand in an increasingly competitive market" in the UK. Like-for-like sales are down 2.9% in the UK and 1.5% in the Rest of Europe (local currency).
Outlook
The
outlook comments start off very bleak, talking about various
"substantial trading headwinds": Brexit uncertainty, consumer demand, a
competitive market and, of course, currency movements.
But then:
We have made an encouraging start to the second half with a return to like-for-like sales growth in both businesses. As we enter the important January trading period, we remain comfortable with the range of market expectations.
So things are not so gloomy, although it sounds as if investors might need to brace themselves for results in the bottom half of the range of expectations.
Those expectations are for "underlying" profit before tax of £16.1 million, with a £13.9 million - £18.5 million range. (The definition of underlying sounds reasonable to me).
My opinion:
(Please note that I own shares in a competitor, United Carpets (LON:UCG) )
I like this sector and I think that this could be a very interesting buying opportunity.
The flooring business can be an absolute cash cow, though it does have a tendency to move in fits and starts. Competition can suddenly spring up out of nowhere, and margins rise and fall with a range of macro-economic variables.
Management is key. Carpetright have been investing considerable cash sums (in this most recent period, spending £4.5 million out of the £5.9 million generated by operations) on capex, primarily on modernising its estate.
That obviously causes a lack
of free cash flow in the short-term, and it needs to provide solid
medium-term and long-term benefits. Based on what I know about
Carpetright, I'd be inclined to have a positive view on management's
ability to squeeze out those benefits. It won't be easy by any means,
but on balance I'd say that they can do it. Let me know if you disagree!
Zytronic (LON:ZYT)
No. shares: 15.4m
Market cap: £60m
Preliminary Results (year ended 30 September 2016)
I'm not running into many positive
news stories, as the market is again not entirely satisfied with these full
year results.
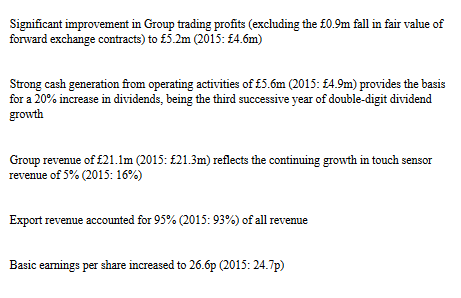
I've not looked at this Newcastle-based company before, but it's in the business of manufacturing touch sensors used in a variety of applications (ATMs, casino games, public informational displays, etc).
Turnover has been creeping higher in recent years.
FX Contracts
Nearly all (95%) of Zytronics revenue is in the export market. With all of the manufacturing facilities in the UK, that makes it a prime beneficiary of the Brexit sterling devaluation.
Note the reference above to trading profits "excluding the fall in fair value of forward exchange contracts".
I'd argue that it's not entirely satisfactory to exclude the losses on those contracts. They are designed to hedge against moves in sterling, so you have to include their gains or losses to get a result which is closer to the constant-currency result.
If the hedges had been profitable (i.e. if Sterling had strengthened), we would likewise want to include them so as to get a result which showed performance based on something closer to the original exchange rates. This is particularly important when it comes to understanding the underlying growth rate of the business!
Volumes:
Excluding the gains from foreign exchange contracts, trading profits were about 6-7% lower, so it is not surprising to find evidence that the underlying growth at Zytronic is rather lacklustre.
The total number of touch sensor units
supplied across all size ranges was 130,000 (2015: 149,000 units). The
single most significant reduction in volume was attributable to a
decrease in medium-sized 15" sensors, associated with vending
applications.
However, as the business has continued to focus on the increasing revenue benefits associated with the ultra-large format markets, with sensors greater than 30", the effects of the reduction in sensor volumes in the smaller size ranges was significantly countered.
So volumes are down overall but the mix is becoming weighted toward the high-end products. Gross profit margin improved to 42.8% from 41.9%.
Outlook:
The year has started well with orders, revenue and
current trading ahead of the same period last year, which provides an
encouraging start to continue to deliver value for our shareholders.
My opinion:
I would like to study it further, but it strikes me as a somewhat
steady, mature business, albeit within a technological niche.
There are no balance sheet concerns, it pays a rising dividend, and so, despite the uninspiring growth, is likely worth the respectable 15x earning multiple at which it trades.
Tristel (LON:TSTL)
Share price: 165p (-7%)No. shares: 42.4m
Market cap: £70m
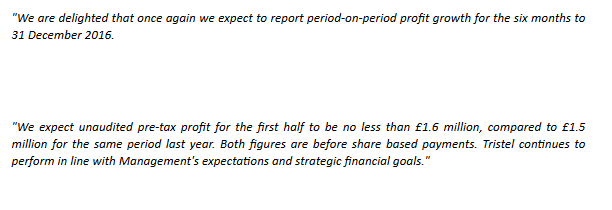
Yet more negativity I'm afraid, but the highly-rated Tristel is under pressure after an AGM statement suggesting pre-tax profit will only show a modest improvement in H1.
The manufacturer of hygiene products has been on a stunning sales growth trajectory, with great imrovements on the bottom line over the past three years.
Brokers have been forecasting pre-tax profit of £3.6 million for this financial year (ending June 2017)
(I am not sure if this forecast includes share-based payment charges, but the company assured the market that last year's charges were "unusually large" and would not be repeated in future years, so perhaps they will not be material anyway?).
These figures imply that up to £2.0 million in PBT will be needed in H2 to match forecasts for the full year. Which doesn't seem out of the question, based on £1.8 million achieved in H2 last year.
My opinion: In a situation like this, I prefer to keep my mind focused on the bigger picture, and not worry about a daily price move. The shares are still higher than they were a month ago.
One thing I'd concede is that the PEG does start to look a bit expensive if you extrapolate this H1 growth forecast ahead for the long-term, so I can understand why a few people might want to bail out at this juncture. But based on the reasonable possibility that it can still hit forecasts for the year, I'd be hard-pressed to say that the value of the company has changed radically in the last 24 hours.
In conclusion: I'd interpret today's pull-back as a healthy correction, nothing more!
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

37 comments
I like the notes today. I am a bull on Tristel but am prepared to wait. There is a useful video of the last results available on the website but my biggest take is simply that they are spending - for a small company - a lot of money on trying to get FDA approval which will take three years or so. The large historic share option costs are not to be repeated (for the time being anyway) we are informed. I am thus accepting the high >20 p/e current ratings on the principle that it is better to buy a good company on a high rating than a poorer one on a lower rating. Earnings I suspect won't grow much in 2016-18 although both Australia and Germany - which also covers Poland and a few other mid/East European markets - are taking up the slack of pretty flat UK profile. I happen also to be looking at the Australian company Nanosonics which is selling in the US in the the same kind of market. Its sales and profits are exploding.
Re:Zytronic (LON:ZYT)
I am a bit surprised at the lack of positive views on ZYT?
Maybe I am a bit new to the company and not yet cynical enough? The results are certainly complicated and overshadowed by the FX, the rapid fall in legacy sales and the flattering tax credits.
But there are three things that make me think that it's worth looking further, the cashflow, the cashpile, the net margins and 5% increase in new product sales. Oops thats four things...There are four things that make me......:Amongs the things that make me.........sorry wrong sketch :-)
The cashflow easily exceeds the underlying profit figures and seems to be a regular feature? The cashpile £12M for a co with £60M mkt value is significant enough to take account of? The reorganisation of the distributable reserves seems to point towards a capital return eventually.
The net margins (even with the legacy projects still declining) are around 20% which is surprisingly healthy in this industry and seems to point towards some kind of USP and/or IP that defends its position and might make it a bid target? If it was just flat touch screens the margins would be minimal and big manufacturers flooding the market - ask Carclo!
I'm not sure about the point of regarding the FX fair value cost as not exceptional? Not that I am an expert on FX! I do agree that they need to hedge their FX all the time so thats not exceptional. But I suspect the 12 months was a mistake based upon years of gradually increasing Sterling and the 4 months they are switching to better reflects the product sale cycle. That aside the 15-20% devaluation during the period is exceptional, even if hedging FX isn't? And I would similarly discount a 15-20% gain on FX in the same way, even more so as the short term gain would be more than discounted by the longer term loss in competitiveness?
As I understand it by taking the fair value of the existing contracts they have taken a charge on all of their wrongly prices FX now? Looking forwards and on the basis that future FX moves are not exceptional within 4month periods then there should be a boost to sales volume from improving competitiveness as well as some improvement in sales value as the old FX unwinds? 15-20% ? Results are to end September so the FX fair value takes all the losses on the chin - before any of the improvements in sales volume or margin can occur?
Apparently sales in the current are ahead. So either the legacy sales are holding up or the sales of new products is accelerating again?
It seems that Management has a tendancy to underpromise? Though looking at the history there has also been the odd banana skin - and perhaps this accounts for the generally negative views?
Looking at an eps of just over 30p this year puts it on an P/E of 12-13 without accounting for the growing cashpile and potential return of capital? That looks like good value to me, ok not Boohoo but it is paying a dividend and growing?
Lion Tamer
I'm sure Peter won't mind me answering on his behalf. I was sceptical until I did a lot of reading around but basically it is much more toxic to viruses, microbes and spores than chlorine or any other common competitive products at lower concentrations and in less time. It isn't unpleasant to use so it gets used, can be used without damage to carpets, matresses and curtains and enables fast turn around of equipment such as inspection probes in outpatient clinics. To ensure effectiveness it must be made on demand to give the correct concentration. Tristel have produced patented methods of packaging the two constituent chemicals which produce ClO2, in various forms for different applications. Several people have pooled their research on ADVFN with links to external websites and Youtube videos. Recommend reading that thread. No idiots on the thread yet so easy to read.
Thanks Samsgrandad, I will read your suggestions
Begbies Traynor (LON:BEG) "£17 million of gross borrowings (nearly £50,000 per employee)".
They could get it under £10k per member of staff by indulging in a massive recrutment drive of several thousand new employees : D
Re: Zytronic, pretty much echo what has been said here.
They appear to have a great product with patents granted but achieiving 'world domination' is taking longer than expected. I feel the management is very conservative/cautious in the way they do things, perhaps they would benefit from a more dynamic board, though a 'safe' strategy is not always wrong.
The currency hit is disappointing as they should be making hay given sterling's weakness.
Happy to hold, cash generative, nice dividend & rating not excessive for what is really a high tech company.
Dennis.
I think Carpetright (LON:CPR) is suffering due to competition from Tapi, which is run by the son of Carpetright's original founder, Lord Harris.
I have never heard of Tapi, but I see they do have quite a few stores so you could be right.
I did get a quote from Carpetright for a bedroom carpet, the carpet price was ok but the fitting and delivery charges were not, so I went with a local company that had reasonable fitting charge and free delivery and gripper, also the underlay was cheaper.
Was the fitters name Walter Wallcarpet ? Did he have a Mexican assistant "underlai, underlai" ?
the best way to make money out of carpets is to wait for the next crash and buy in, not a happy place to be, though commercial floor coverings seem a little easier to judge.
See also sofa manufacturers and bed makers.
Replying to Herbie, Simoan and other supporters.
I've held TSTL for 12 months now, believing it to be a good long term growth share. Acquiring control of the Australian distributor was a significant step forward but the States remain the big challenge - and the big opportunity. Finncap made no change to their forecast this morning but did say they thought the risk was increasingly on the 'upside'.
Hi Michael,
For the record, I like the company, even despite last years ridiculous share awards to the CEO and CFO! It might justify the current rating, and it would not surprise me if it were subject to a bid either, but I decided I'd rather put the money into shares that were better value on current fundamentals; in particular Character (LON:CCT), Revolution Bars (LON:RBG) and Ricardo (LON:RCDO).
All the best, Si
I see directors have sold quite a few shares yesterday in Character (LON:CCT).
Had a quick look at Ricardo (LON:RCDO) does not look great value now, also has £18m pension deficit.
Yes I'm considering Revolution Bars (LON:RBG), at the moment.
I see directors have sold quite a few shares today in Character (LON:CCT).
Yes, supposedly to meet institutional demand. Anyone who deals CCT will know you can't sell that many shares at the market price unless there is genuine institutional interest, which is not a bad thing IMO. If they had sold them at a discount you could probably make a case for it being a negative. Both directors still have substantial holdings.
Had a quick look at Ricardo (LON:RCDO) do not look great value now.
Agreed. I started accumulating at 880p (from memory) and was not expecting them to go anywhere, so the rise up to 950p has stopped me buying more. Still cheaper than Tristel (LON:TSTL) though depending how you judge things :)
Yes I'm considering Revolution Bars (LON:RBG), at the moment.
I've got enough of these for now but will buy more on any pull backs.
All the best, Si
I would agree with you about the bid prospect Si. Because of Tristel's patent protection it may be quite difficult for a larger company to develop competing chlorine dioxide disinfection products, yet selling them through a larger distribution and marketing system (particularly in the US) would undoubtedly boost sales and margins. The fact that these products address a truly global market would also be attractive for an acquirer. I think this is one of the reasons why Tristel is quite highly rated and it is certainly one of the reasons why I am comfortable holding the shares.
Tristel (LON:TSTL)
Out of curiosity , why are "chlorine dioxide" disinfection products so important / better? Surely other disinfectant technologies are available, in which case the uniqueness of the patented chlorine dioxide product may not be much of a moat?
Thanks.
Zytronic (LON:ZYT) was as I've come to expect, nothing startling either way.
I'm slightly concerned by the drop in volumes, but slightly excited by the rise in higher margin sales. If this is, as I think they claim, to be deliberate strategy then it's working and is good. If they're dressing up a change of sales mix as strategy, that's not so good.
Ultimately, if I was to sum it up....follow the cash. Cash is flowing in in excess of profits, and that's good enough for me to hold at this price.
The lack of top line growth seems to be a recurring feature with Zytronic (LON:ZYT), which is a bit odd as one would think they are operating in a growth industry. Great margins, cash flow and returns on capital, which are all the things I look for in a share, but you can only get so far with production efficiencies, margin improvements and tax breaks before lack of top line growth makes itself felt.
I'm a holder, but for me it's not a strong hold.
Yes I find Zytronic (LON:ZYT) lack of sales growth strange too, because the flat screen market is predicted to be growing at 10-14%/annum. So ZYT is effectively going backwards vs. rest of the competition, unless its a case of lumpy sales. I sold out in May after flat H1.
I do find Zytronic (LON:ZYT) figures to be dissapointing, with exchanges rates in their favour why is revenue flat?
Their last statement in September said "the group's underlying profit - before this non-cash item - is expected to be significantly ahead of last year and at least in line with market expectations."
Well I'm not sure it is significantly ahead and I don't fully understand this "£0.9m non-cash provision arising from the group's foreign exchange policy."
I agree that ZYT results look very uninspiring - total revenue down 1% and growth of their new products only +5%, gross profit only marginally up, this all looks rather pedestrian to me.
I also think TSTL's AGM statement is very disappointing and I'd be surprised if the shares didn't drop more - in the last interims their profit was up 36% and in the prelims it was up 20+% (which implies a weaker H2)... so to be told that the coming interims will show a profit growth of at least 6.5% is surely disappointing...?
Valueing Tristel by conventional historic metrics seems to me like driving through the rear view mirror.
There is a huge market to crack for protection against hospital acquired infections, there has been a big take-up by hospitals in building in Tristel's UNIQUE patent protected products into cleaning routines. Google Tristel and work past some of the sponsored results and you'll see several hospital trusts mentioning Tristel in cleaning specifications. One of the posters here has already mentioned increasing expenses eating into the bottom line this time, perhaps, as they build up awareness at exhibitions and pay for testing to get US approval. TSTL has some very good research on ADVFN board but an excellent analysis by Equity Development (who I think are company insiders, if not he was very quick) this morning puts it much better than I can. It's a definite hold for me, I feel sure the next growth spurt is very near.
I also note the significant rise in the dividend. This from a conservative management.
Good afternoon Graham,
It would be great to get your analysis on LON:BOWL who listed a few months back with their maiden results today. It seems to be under the radar with not a lot of coverage. It'd be good to get your analysis of their results.
I am a currently long in the share.
Thanks a lot for the suggestion Phil, I'm sorry I didn't get around to it but thanks for bringing it to my attention - not one I've looked at before. Best of luck with it.
Graham
Interesting shorting attack on Paysafe (LON:PAYS) this morning after an RNS detailing that the CFO had sold half his share options. Here's the link: https://www.scribd.com/document/334063463/Pay-Safe. I hold a few.
TSTL
"I think like me others have maybe seen today's prediction of only a worst-case £100k LFL increase in pre-tax profit as underwhelming for a company on a PER of 26.I am sure they will underpromise and overdeliver on those numbers"
Last year TSTL said it would make at least £1.4m in H1, and the figure turned out to be £1,480k (pre share-based payment). If we assume at least £1.6m this time could mean £1,680k, then we get a £200k improvement.
Also, my notes indicate US costs of £500k are scheduled for the current FY, so perhaps £250k has been spent in this H1.
That compares with £190k spent last year.
So US costs could be £150k higher in this H1, all of which is expensed and has no associated revenue.
So yes, fingers crossed it is management under-promising and about to over-deliver.
That said, it would have been helpful of management to have given a revenue figure and some remarks on US costs, so shareholders had a bit more of a clue what was going on.
With Ref to Carpetright, I was also expecting a bigger fall on those results. The Management saying they are "comfortable" with Full Year Expectations (c £16.1m PBT) and the first six weeks trading LFL being +2.6% have probably mitigated the impact of the first half results. The Brokers Full Year view is a YOY decline of £1.2m...while the first half has already showed a decline of £4m (from £9m to £5m) ....so a big improvement in profit is factored in for the second half in order to get there.
CPR have already guided the Market that Full Year Gross Margin % will be c1.25% - 1.5% lower than LY (Currency Headwinds etc) so one assumes the 1.5% decline seen H1 will continue through H2. Also, if one assumes that the cost savings seen through H1 will continue at the same rate (lower Marketing, Bonus Payout etc). The key sensitivity is what LFL sales will be. .
By my crude calculations, I think they need c+3% LFL in the second half in order to get to £16.1m Brokers View. The Bull Case is that the first six weeks are travelling at +2.6%, and if that rate continues through the half they will get close. The Bear case would be that the demand is "uneven" (their own word!), the first six weeks of second half are small volume weeks in comparison to Post Boxing Day, and therefore the First Half LFL of -2.9% is a better indication of where they really are.. If they achieve an LFL of -2.9% again in second half, then my models would suggest a Full Year PBT of c£7m, a far cry from the Brokers £16.1m.
Like all Retailers, this is a business with high Operational Gearing, and the show how incredibly sensitive the profits are to a small change in LFL assumption,
DYOR - Disclosure - short CPR.
Also NCC (LON:NCC) - I wonder if I've missed a good entry point this morning. Fox Marble Holdings (LON:FOX) looking like a lost cause - staying clear of that one!
NCC (LON:NCC) made a strategic move into cybersecurity some months ago. It's a boom area but that brings its own problems - everyone is struggling to recruit, so staff turnover is high and salaries are excessive for the quality and qualifications of staff. Most companies' approach to cybersecurity is flawed: the y rely on:
(a) telling staff not to click on links or open attachments or plug in USB sticks or visit non work websites using the company computers or network - but they then continue to send out emails with embedded links and attachments, and allow or encourage the use of personal devices at work.
(b) using "penetration testing" to identify vulnerabiities, when it has been known for decades that testing cannot show the absence of problems, but only the presence of problems (so, for each one you find you should assume there are dozens more).
(c) using network monitoring to detect unusual activity, when the widespread assumption in the software industry is that most companies are already infected with malware, so they won't have a clean and stable basis to monitor against.
NCC seems to be a good company but the next 12 months could prove challenging as they integrate acquisitions and give necessary attention to the new business direction.
You may not have missed the best entry point!
I have no stake in NCC, but it's on my watch list.
Good morning Graham,
A few announcements or updates today from Zytronic (LON:ZYT), Tristel (LON:TSTL), Carpetright (LON:CPR), would be grateful for your comments. Don't understand why Tristel (LON:TSTL) went down 10% with inline trading.
herbie47,
Don't understand why Tristel (LON:TSTL) went down 10% with inline trading.
I sold my Tristel (LON:TSTL) a couple of weeks ago as they looked expensive and the update is a little underwhelming for a company on a current year PER of 26. I like the company but it looks expensive for the relatively modest underlying growth in earnings, the PEG must be off the scale! Of course if they crack the US market the current rating will look reasonable, but it's a big IF and you are already paying for it to a large extent.
All the best, Si
Hi Si,
Yes they do look quite expensive now, but PEG is only 1.26 on Stockopedia figures. Yes I did take some profits a few weeks ago as well. I see the shares now are only down 5%. I still think 10% fall is a bit too much. Carpetright (LON:CPR) only went down 4% on a profit warning.
Re underwhelming I think most of their statements are conservative, which I like, nothing worse than hyped up statements that don't deliver.
Yes they do look quite expensive now, but PEG is only 1.26 on Stockopedia figures. Yes I did take some profits a few weeks ago as well. I see the shares now are only down 5%. I still think 10% fall is a bit too much.
Yes, you're right about the PEG, Morningstar has it as 1.5 for FY 2017. I assumed it would be higher. I think like me others have maybe seen today's prediction of only a worst-case £100k LFL increase in pre-tax profit as underwhelming for a company on a PER of 26. I am sure they will underpromise and overdeliver on those numbers, but sometimes you can take that too far and IMHO it is easy to understand why it has sold off this morning.
All the best, Si
agree about Tristel herbie, the update didn't look bad at all. Maybe just not exciting enough for the rating? or maybe a tree shake by the market makers?
What do people think of Carpetright (LON:CPR) ? Personally, I am surprised it isn't down more on the pretty poor trading statement it put out this morning. Like for like sales have fallen, free cash flow has shrivelled, gone from marginal net cash to net debt. Looking at competitors United Carpet and SCS Group (who have marginally positive LFL), I am inclined to think there are problems at Carpetright.
I think some of this is already in the price which has dropped from 485p last year. Also LFL sales in the 6 weeks to December 10, they've improved and are up 2.6% in the UK.
I also noted that EPS estimates for the current financial year have been revised downwards and I assume already in the price. For example in the trading update issued on 25 October 2016, PBT consensus was £18.5m, and if you read the notes to the interims issued this morning, PBT consensus for 2017 is now £16.1m. Obviously EPS will as a consequence be lower.
I don't hold a position, but have it on the watch list. Hope this is useful.
Imran.