Small Cap Value Report (13 Mar 2017) - HAT, RXB

Morning,
I am likely just to cover H & T (LON:HAT) today. Without further ado:
H & T (LON:HAT)
Share price: 270.75p (-0.6%)
No. shares: 37m
Market cap: £100m
(Please note that I currently have a long position in H & T (LON:HAT).)
This remains my largest holding (25% of my portfolio - I do not recommend that others run such a concentrated portfolio as this).
I am pretty happy with these results:
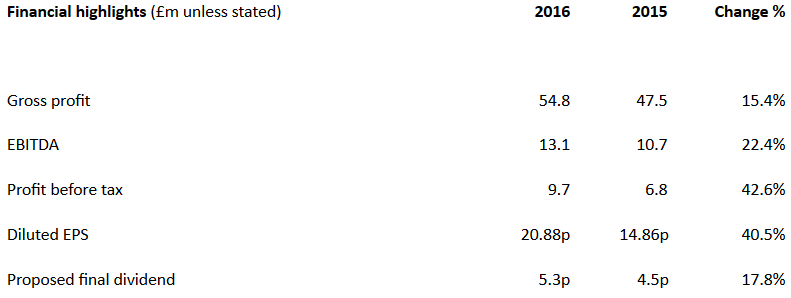
The pledge book is now 6% bigger at £41 million, despite the number of stores having reduced to 181 (from 189).
But the biggest change in the KPIs is the gold purchasing margin having increased from 15% to 26%.
Even though I'm a goldbug, and fully anticipate that the gold price will be a long-term tailwind for H&T, I'm also really excited by the opportunities created by the company's move into related financial services: personal loans, FX and buyback (pawnbroking for electronics, basically).
In that regard:
- the personal loan book is now worth £9.4 million (up from £4.2 million).
- the volume of buybacks is up to £8.5 million (from £6 million).
- FX gross profits almost doubled to £2.7 million (from £1.4 million).
So the sources of income have become more diversified, though they all rely on the company's core financial competencies.
Note that the loan book is something of a wild card - it's far from clear how big it could eventually get, and what its profitability might eventually be.
It generated interest worth 92% of its size in 2016, but 40% of this was lost to impairments (customer defaults). So the margin after defaults came in at 55% of the average size of the book - still highly encouraging. That margin should gradually reduce as the book gets bigger.
Net debt is up by a few million to £5.4 million - this is to be expected when the pledge books/loan books are growing. The CEO has said previously how he wished the company's net debt was higher, because it would be a side-effect of having found more profitable opportunities!
In terms of regulation, today's statement reiterates that all H&T personal loans are below the FCA's interest cap on short-term credit - "in reality, the vast majority are significantly lower than the cap". While regulatory risk never completely goes away, this environment looks quite benign to me.
And the core pawnbroking operation is always going to have modest interest rates anyway, relative to unsecured lending.
Outlook
There is some easing of the competitive environment; the wider economic uncertainty and fall in the value of sterling is supporting the gold price and, as such, demand for our products is strong. The Group is well positioned to take advantage of these conditions with a diverse set of products, developing distribution channels and consumer recognition.
My opinion
I remain very happy with the prospects here, and believe that the valuation should still allow for plenty of upside.
Looking through the CEO's notes, I note the following:
The Board believes that while there is still opportunity in Pawnbroking for H&T the market is shrinking and in order to maintain our position we must develop new channels for customer acquisition particularly through brokers and online.
An increased focus on the online channel is to be expected in the years ahead, as services migrate online as much as possible.
But physical locations remain hugely important - from a jewellery retailing point of view, as well as providing convenient locations where items can be inspected.
It's a shame if the overall pawnbroking market is shrinking, of course. The most important thing from my perspective is simply that H&T remains the biggest and most attractive pawnbroker in the market, and the default choice for the most potential customers.
According to the CEO:
"The Group is evolving into a provider of alternative credit services to serve an increasing customer base.
Sounds good to me.
Of course, if you don't have a view on the price of gold, or if you are bearish on it, you might want to proceed with more caution here
By my calculations, half of the increase in gross profits in 2016 was due to the increased gold price.
But for a company which has been around for well over 100 years, which is number one in its niche, which has recently survived one of the harshest competitive environments ever faced in its industry, and which is now growing a variety of related income streams, I think the current share price of 13x trailing net income remains a modest valuation.
(Please note that this is just my opinion - always do your own research! And also please note that I might change my opinion, and I might buy or sell shares in H & T (LON:HAT) at any time and for any reason.)
Paul Scott adds the following comment:
Reasonably priced & financially strong, but do you really want to own shares in a pawnbroker? I don't!
(This section by Paul.)
Rex Bionics (LON:RXB)Share price: 4p (down 69% today)
No. shares: 25.5m
Market cap: £1.0m
Funding & strategic review update - just a short comment on this one, to close the file.
I met this company when it floated on AIM and it was abundantly clear to
me right from the offset that we were being asked to make a donation, rather
than an investment. However, because it was a wonderful project (developing
devices which enable a wheelchair user to be strapped in, and stand up &
walk using power assistance), I tried not to say anything too negative in
these reports.
Anyway, today's update is basically saying that the company's time as a
listed company is almost over. It can't raise the necessary funding. However,
there is one lifeline whereby a new investor has offered fresh funding, by
investing into a new company that would own the old company. The new investor
would therefore be diluting existing holders, but no indication is given in
today's statement as to what the level of dilution would be.
Existing cash will only last until end April 2017, so I think it's safe to assume that the existing shares are now worth very little, or nothing at all.
My opinion - this was an admirable project, but it never should have listed
on the stock market. This was a charitable project, to develop a product which
is of potentially great social benefit, improving the lives of disabled
people, but this is not a viable business.
I think projects like this should be funded privately - perhaps by
philanthropists, or by Universities via grants, etc. The stock market is just
the wrong place for this. If I want to make charitable donations, then I'll do
so. However, if something lists on the stock market, then it has an army of
hangers-on, creaming money off for themselves - so Directors, NEDs, brokers,
PRs, etc - therefore not enough of the money invested actually makes it through
to product development. I wonder what percentage of investor money in Rex was
basically wasted, paying such hangers-on? A fair proportion, I would
guess.
I very much hope this project survives & does well in private, preferably charitable status ownership. It was heart-warming to see the product demo, where a young disabled athlete rose up in the device, and talked about how it had improved her life. Sadly though, that doesn't make a good investment. Therefore it needs funding from charitable sources, not commercial ones.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

53 comments
I see Oozi Cats sold £24,077,508 worth of shares at 340p in May 2017. Its often a good idea to follow directors selling. Yes it is a problem I had with this company, I think excessive remuneration is the correct term.
Ya bonkers Neary Nuff , 25% in one share sounds like a get poor quick scheme to me ........5% is plenty .
Thanks for your comprehensive review of Modern Portfolio Theory, Wildrides .. it's clear to me that you must have been working alongside Harry Markowitz in the 1950's ;)
I was only a few years old then Karl , and only trading Corgie di cast at the time
Wildrides - post 28 - consider that strike 1.
Graham is a hand-picked, highly experienced commentator. Also, a modest, charming, and very smart fund manager, who has handled a £600m portfolio.
I'll back Graham to the hilt. So any attack on Graham, is an attack on me.
Paul.
I know who Neary Nuff is ..........he used to write on "Share Prophets" before he graced these pages . Whats that got to do with anything ...........25% on one share is still bonkers by any rational standards ..........let the man defend himself if he disagree's . Strike one .....oh er .......its back to school . You are funny "Beam me up"
Hi Graham,
Have you thought of setting up a fantasy fund? I think it gives Paul real credibility that he does one.
Thank Dan
Hi djsdanny,
Hi Graham,
Have you thought of setting up a fantasy fund? I think it gives Paul real credibility that he does one.
Thank Dan
Hi djsdanny - that's a good point actually. I didn't want to set up a fantasy portfolio, because Sod's Law often kicks in. Also, if you set up a fantasy portfolio people copy it when you're doing well, then kick your ass when it's doing badly. So why bother?
The only reason I did it, was because my boss here, Ed, kicked my ass about 2 years ago & said OK you THINK ur a good stock picker - so prove it to me! i said well, kefuffle whatsit, diddly-do-dah! Bottom line, Ed wanted some stats - he's a mathematician, and after I got over my system 1 (caveman) anger, I thought - he's got a point. Also, he's such a nice & incredibly intelligent man, and along the way, he did buy me lunch. So the conditions were all set.
Anyway, there we go. At this point, farts intervened, and a massive bull market started.
So, my point is, that we shouldn't think we're clever in a bond market, or a bull market. A lot of it is luck.#
Cheese.
PP.
Telit Communications (LON:TCM) the problem I have with it is the directors remuneration, I wonder if the company is being run for the directors or the shareholders? Last time I looked Oozi Cats was taking millions of £ out of the company. If it's true that they don't make any money then I don't think that's right. I can see why it's being shorted.
Thanks very much for the feedback,
I think Paul intends to cover Telit Communications (LON:TCM) today.
On H & T (LON:HAT), the 40% impairment in the personal loans product is higher than for example International Personal Finance (LON:IPF) (with impairments running at 27% as a proportion of revenue). I'm still very comfortable with the 55% gross margin on the book this year, after impairments. It's going to be a lot more volatile than mortgage lending, that's for sure. Whether the average gross margin achieved over the long run is good enough to generate an acceptable return on capital, only time will tell and I guess will be up to each individual shareholder to decide for themselves anyway.
As mentioned, the company's net debt has increased because the pledge book and loan book are bigger. Cash goes out the door because it has to go to customers first, before H&T can generate interest on it.
Regards
Graham
Graham,
With such a high impairment charge I wonder if HAT are increasing their lending by funding more of the high risk individuals that the other more experienced subprime lenders have turned down? If so then doesn't sound a great strategy! Echos of subprime house lending maybe?
Hi Graham
H&T - I'm not sure if / why its lending would be more volatile than mortgage lending. It's a widely spread book of small, high risk, loans - but, I suspect, the trigger to default is much more driven by personal circumstances than by macro events. And, being short term loans, there's much more opportunity to steer the book as the economic situation develops.
A mortgage book is much more internally correlated upon house prices. At a time where house prices are lowish, but steadily rising, and LTVs are restrained, economic shocks may trigger a rise in foreclosures - but are unlikely to trigger significant loan losses. BUT, where house prices are high, LTVs stretched, interest rates low and lenders are under regulatory pressure to tighten up lending, an economic shock / interest rate movement could easily trigger multiple foreclosures and drive house prices down - resulting in significant loan losses.
I think people have largely forgotten that property prices can drop.......
BUT, I've been bearish (and wrong) about house prices for decades........
Hi garbetklb,
There is probably an angle you could look at things from, which would indicate mortgage lending is more volatile. I simply meant that the default rates are much higher for personal loans, and will bounce around at those much higher levels. Meanwhile, mortgage lenders will be praying that mortgage delinquency rates don't rise 50 basis points from current very low levels.
Cheers
Graham
Hi Graham,
Sorry I did intend to write about Telit Communications (LON:TCM) today. But then other things interfered - we had a workman round to re-do a few things at the house, then I fancied a cooked breakfast, then I fell asleep, which happens frequently when I have a mega-breakfast from my local greasy spoon. Then I had to get up and go to a meeting in the City, and have a meal & drinks with the people involved, so before I knew it, the whole day was gone.
As I mentioned here before, TCM looked like a short-squeeze to me. The last update sounded more positive, so anyone still short of it was pretty daft. They got their butts whooped today by the looks of it, tough cheese.
I've not got time to look at TCM results, but it's the market's most heavily shorted share, so when things improve, anyone with sense closes their short position.
As I suggested last time I looked at it - here: http://www.stockopedia.com/content/small-cap-value-report-10-jan-2017-boo-som-call-tpt-wine-gaw-tune-tcm-kbt-carr-hat-165939/
... to me this was a share that looked ripe for a short squeeze.
I bought a few, but then panicked repeatedly - I hate holding shares that make me nervous, so am kicking myself now. So it was another fisherman in his waders (my grandad!) moaning when he got home about the one that got away. Whilst presenting his disappointed wife with, well basically nothing. That was at Gullitha Falls, in Cornwall.
Anyway, I had a plump cod & chips from Sutton & Sons on Essex Road today - lovely flakey cod.
Telit reminds me of that B52s song, telit, TELIT (higher octave), like it T I, T I, IS!
Anyway, the signs were there for a short squeeze, as I pointed out in January.
Cheese, Paul.
Paul
Telit Communications (LON:TCM) is down 40% today though the update says:
The Group expects revenues of $400 million - $430 million for year to 31 December 2017
o Any further than anticipated delays of revenues are expected to fall into 2018
· The Group expects adjusted EBITDA of $47 million - $60 million for year to 31 December 2017
· Group confident of reporting over 15% revenue growth for year ended 31 December 2018
In reply to comment 16:Today's review of HAT was written by Graham.
Oh oh - apologies to Paul - and Graham.
Gotta delete that later!
Thanks Clive.
Chris/Clive,
I love you to bits!
We all love you to bits! :-) No harm done.
Cheese, PP./
Paul
Rightly or wrongly I read this to be a half assed apology for your original crass comments. Whether it is or not - it matters not.
In summary, while I erroneously concentrated on the HAT messages, rather than the author, (kindly flagged up to me by both Clive and Howard) perhaps you should follow through the threads before responding. No need for you to showboat and make smart ass insults to a contributor who had already apologized - twice. I previously considered just ignoring your comments but decided an answer really was appropriate.
While I continue to acknowledge your financial expertise/wisdom, I think you need some training in manners.
Hi Chris,
Yup, I'll take this one on the chin.
I apologise to you for being rude & getting carried away in the heat of the moment.
Hope no harm done.
Best wishes, Paul.
Hello Paul.
Thank you for your apology. I think you need to give yourself one strike for the post as it violated numerous site "guidelines". I have flagged this under the "reporting" requirements - although as you are probably judge/jury and on the "Moderation Team", not sure how the sentencing will work out.
Regards
Chris
Hi Paul
Wow - surprised to read 25% of your portfolio is made up of this share - especially after your January 10 comment on HAT -
"I looked at its rapidly growing loan products though, and they're really ripping off desperate people with excessive interest charges. So on that basis, it's not a share I could own - but I do think the share is likely to go higher. So it's tempting!"
That was some change of mind?
Regards
Chris
Different author, Chris
Thanks Howard
Oh oh - apologies to Paul - and Graham.
Gotta delete that later!
Chris,
Oh dear - go to the back of the class, dumbo!!
It's Graham writing the section on H&T, not me! :-)
Maybe we should use a different font in future?
Regards, Paul.
"Graham is a hand-picked, highly experienced commentator. Also, a modest, charming, and very smart fund manager, who has handled a £600m portfolio.
I'll back Graham to the hilt. So any attack on Graham, is an attack on me.
Maybe we should use a different font in future?"
Hi Paul,
Clearer visibility and definition of who is writing what would be appreciated.
However good you both are, your strengths, weaknesses, perspectives and opinions are quite different.
"Monday, Mar 13 2017 by Graham N"
"Paul Scott adds the following comment:"
"(This section by Paul.)"
Seems clear enough to me. Furthermore their writing styles are completely and recognisably different. What more do you want?
I prefer a separate report, it's then clear who is writing it. Maybe it's time to rename these reports, as mentioned before they are not so much Small Cap Value Report anymore.
Exactly
disappointed no comment in Telit. Paul was negative on both the results and the finance in January so further assessment would be appreciated in light of those cooments then
Hi Graham - Re. H & T (LON:HAT)
I am amazed that a long established staid business, pawnbroking (going back to William the Conqueror days) can generate over 40% in profits and a 41% growth in earnings. Either the competitors are asleep or the company has a competitive edge that eludes me.
On my analysis sheet I cannot fault it, except for one question mark. The Operating Cash Flow has come down a lot from 11.2m to 1.3m, and the Free Cash Flow is now negative against a healthy positive £10m in the previous year.. I think this is due to a disproportionate increase in working capital, namely inventories and receivables?. Your comment would be useful.
I know you said their business is off the FCA's radar. But I cannot help feeling that the FCA has a way in meddling with small lenders and upsetting their profits.
About a month back a new kid on the block Ramsdens Holdings (LON:RFX) IPO'ed also offering pawnbroking services. At that time your comment was that H&T was the better business. Is this still your opinion?
Regards, Ram
On balance this one is not for me.
Ram, he has 25% in H & T (LON:HAT), does that not answer your question?
As a Minervini follower I'm surprised you touch IPOs.
Herbie
"As a Minervini follower I'm surprised you touch IPOs."
I am a Minervini follower, not a blind follower.
In any event, he does invest in IPO s,but waits a few months to see some history.
The poor cashflow conversion is also something I noticed. In the RNS they explain it thus:
"Working capital movements led to an outflow of £9.8m (2015: £2.2m inflow), which was principally a result of the £8.1m growth in the Pawnbroking and Personal Loans loan books."
The loan books have indeed increased by around this amount so it seems reasonable that working capital would show a cash outflow. All else being equal this should translate into higher profits in future periods, but as others have mentioned the impairment rates will need close monitoring.
I thought that results at H & T (LON:HAT) were above the already increased expectations, and have topped up today.
I think that the stock will divide opinion, as we have already seen in the report and the comments, a bit of a Marmite share to be sure.
I guess at the end of the day the stock market is a place to make money as responsibly as possible, and I'm happy to hold shares in H & T (LON:HAT) while some would steer clear given the business that it is in.
Regards,
DS.
HAT, I was hoping for more of a jump at the announcement (1%) of my assets, but along for the ride. I understand Paul's issue with pawn, but it is only P2P lending which I also endorse.
REX, is really sad, I put a bit in, just because the looks on the user's faces were so wonderful, it just needed to work, still it didn't help having HQ in UK and business in OZ. Sheds small tear.
I noted a correlation between HAT and Gold priced in Sterling. (Use Stockopedia Charts and overlay SGLN). So I think this is a play on Gold and USD/GBP. I expect the gold price, which is bought and sold in USD to increase and I expect the USD to strengthen with Trumps fiscal policies
Abcurtis
I hold ETFS PHYSICAL GOLD ETC (LON:PHGP) - a physical gold ETF - to track the gold/dollar index, for exactly the reasons you give.
Graham,
The non standard finance market has a tailwind in that many of the rogues have been forced out of the market by the very necessary government action which is a major reason I hold Provident Financial (PFG) and Non-Standard Finance (NSF). The 12M people who cannot get bank accounts still need to borrow money however PFG and NSF are upgrading their loan books but even so currently have impairments of only circa 25%. HAT's impairments of 40% is a major concern implying a much poorer quality of borrower, just the type who may not be able to repay if a recession hits when HAT's impairment rate will go up not down.
I think they are also behind the curve a little with the tech if you have a look at their competitors. I do like the gold angle with HAT but of course the gold price will not necessarily rise if the UK economy falls away later this year.
Dave
PS I am tempted to buy a few but not 25% worth!!!
HAT I had been looking to purchase but thought I would wait for the results due to the move into personal loans. I agree with Aislabie. The impairment gives me no confidence that they have a handle on this side of the business as yet. I will wait for another set of results to see if they can reduce this figure.
H&T and your comments appear very positive, but I am not clear how 40% impairment is anything but a calamity. Surely this is far, far more than a personal loan business is supposed to show, presumably the interest rates have to be penal to keep this business going.
On Telit (TCM) while I note a general enthusiasm for the results and the price has moved sharply ahead, the large short interest in the shares has always been about cash flow. There is nothing in these results to change a belief that the company has still not got any worthwhile net cash flow and continues to be eaten alive by R&D costs (both expensed and capitalised). Worse still, the payables are now appalling, with a rise from a terrible 138 days at the interims to a nosebleed 190 days at the year end.
The collection of receivables at 104 days is either hopeless or suggests that the second half was severely back end loaded, possibly stealing sales from 2017. (A back end loading might also account for the payables delay)
All in all I am happy to watch this from the sidelines to see if the relentless expenditure on R&D ever gets to push up the net cash flow high enough to pay for it.
Good call! Telit Communications (LON:TCM) shares are down 40% today.
Oozi Cats is still promising a profitable outcome for the year ("adjusted EBIDTA") so maybe the fall is an overreaction. Any views?
I sold out at 215p, I'm pleased to say.
FREng, thanks for your note. I am delighted to have dodged some losses here (I sold at 345p) but I am no stranger to losses on other stocks!.
I don't think it is time to go back in as I am sure that this will prove Ed Crofts observation that profit warnings tend to lead to extended declines. (And Warren Buffett's wry comment that "there is rarely only one cockroach in the kitchen")
I sure it will grow and even prosper eventually, but there will be plenty of time to get back in once the future is clearer, it takes a while for people to get over a whacking like this. I certainly would wait for Oozi Cats to seriously trim his own pay and benefits.
"I certainly would wait for Oozi Cats to seriously trim his own pay and benefits."
I think we'll be waiting a very long time!
It turns out that we probably won't have to wait for Oozi to make this decision!
Hi Graham,
Thanks for your write up on H&T. If you have spare time, would you mind casting your eye over Telit Communications (LON:TCM) today. Full year results were announced this morning with the stock up c.8%
Ben
I too would be interested in anyone's view on the Telit Communications (LON:TCM) results. Until recently, I held these shares. To me, the results were in line (given the post year trading statement) but the outlook statement was, to me, a touch disappointing (i.e. double digit top line growth and recurring revenue will increase) and seemed slightly less robust than some earlier statements and there was no mention of guidance for free cash flow, which seemed a focus for the company 12 months ago . Still the stock is up strongly today. Therefore there must have been something that beat someone's expectations. Given the large concentrated short positions in Telit, there are clearly a number of investors whose expectations are below management's - and I think it is difficult to estimate where "real" market expectations are.
Telit Communications (LON:TCM) down 40% today.
As Aislaibe has mentioned before, the cash flow generation needs to be watched. In this half -year, net debt fell only by $8.4 million, despite a $49.7 million capital raise (partly offset by a $7 million acquisition and a $5.7 million dividend). I make that a balance of $22.1 million that has gone on CAPEX, R&D and operating cash burn. Receivables levels have been mentioned before on this thread but now Inventories are also increasing.
Look also at note 5, footnote 2:"An amount of $19.1 million was classified in the balance sheet as short-term debt, as a result of the Group not meeting one of the convenants imposed on it by one of its banks at 30 June 2017. As at the date of this report, the relevant bank has waived the covenant and the Group is no longer in breach".
On top of this no interim dividend.
Thanks! Well spotted for note 5 footnote 2. That looks somewhat ominous as does the cash burn.
The Internet of Things is real and it will generate big profits for some companies, but the competition is getting quite crowded and it's far from clear that TCM will be among the winners.
Re Telit Communications (LON:TCM), note this morning's statement re Mr Cats' leave of absence. I don't know what was known on Monday, when Telit had its conference call - but it is noticeable if you look at the transcript (on the Telit website) that the CFO was taking the lead in answering the questions.
HAT I thought these results looked really positive, so I am surprised the share price is (slightly) down so far - what do people think the reason is? Gold fears? That comment on shrinking pawnbroking market?
Graham, thanks for the H & T (LON:HAT) review. Wow 25% of your portfolio that is some holding. I only have a small holding but may top up today, results are good, seem to be ahead of market forecasts, odd the share price has not gone up. I agree a lot is to do with gold price but I think gold is not a bad investment at the moment.