Small Cap Value Report (13 May 2016) - IPOs, HOTC, MOTR, BRY, RTN

Good morning!
Sorry there was no report yesterday - I had a relaxing day lounging by the pool, and there wasn't much in the way of news to report on anyway. Am flying back to the UK on the overnight Sat-Sun flight.
I've enjoyed Abu Dhabi very much, although the lack of civil liberties & human rights is a nagging concern. There again, the payback for that is a lack of crime - something everyone can enjoy every day, providing you don't fall foul of the law in some way.
Radio 4 - BHS
Last night, Radio 4 broadcast a very interesting programme, "The Briefing Room" concerning BHS & Sir Philip Green. They used a couple of recorded clips of me, about halfway through.
It's an excellent, and very balanced programme, in my view. Here's the link to the audio.
IPOs
The IPO market seems to be perking up again. I'm seeing new floats almost every day in the news feed. Hotel Chocolat (HOTC) is of particular note, because it has launched very successfully on AIM at 148p per share. In the first 2 days of trading, the price leapt to an immediate premium, and is now about 207p, or 40% up on the Placing price.
The founders still own 66.6% of the stock, so that small free float and strong demand have combined to squeeze the price much higher. Whether the shares offer value for money, is another question. I had a look at the Admission Document, and it seems to have had strangely erratic profitability. There was a sharp fall in profits due to a failed IT project, and cessation of operations in USA, and somewhere else. That doesn't exactly fill me with confidence.
I wonder if it will join the long list of companies which warn on profits 6-12 months after listing? Time will tell.
IPOs generally seem to be very poorly structured. The promoters clearly want to do as little work as possible, in return for a large fee. So they just place big lumps of shares with Institutions. Combined with founders often retaining a large stake, this means the shares launch with virtually no liquidity. How on earth does that make sense?
Instead, I think companies should insist on a decent chunk of the shares being offered to private investors, in relatively small parcels. This would greatly improve liquidity from the start, which is surely the whole point of having a listing - to create a liquid market in the shares? So why are promoters currently doing IPOs in the worst way possible - Placing shares in large blocks only? It's just laziness.
Motorpoint Group (MOTR)
Share price: 200p (IPO price)
No. shares: 100m
Market cap: £200m
IPO - this share is launching on the main market today. It looks rather interesting - the company operates a chain of 10 car supermarkets, selling nearly new cars at competitive prices.
The price seems to be a PER multiple of 14.9 times earnings for the year to 31 Mar 2016 (calculated at £200m market cap, divided by £13.4m earnings (highlighted figure below).
As you can see from the table below, the figures show an excellent progression of profits in the last 3 years:
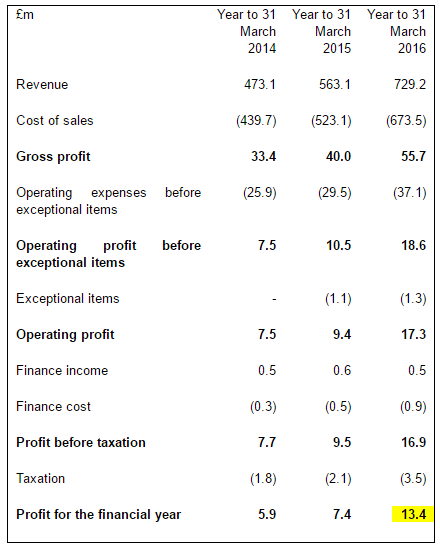
All of which makes me wonder why the founders are happy to sell half the company now?
Both Hargreave Hale, and Miton Group have taken 3% of the company each. It's always reassuring to see them participating in an IPO, as they're shrewd investors, and good judges of management teams, usually.
So this looks a potentially interesting share, I think.
Brady (LON:BRY)
Share price: 62.5p (up 0.8% today)
No. shares: 83.0m
Market cap: £51.9m
AGM statement - this sounds reassuring:
"The Group has continued to make progress in the year to date and the first quarter's results were in line with management's expectations.
More detail is given on contract wins.
On outlook, the company says nothing on the full year, but makes reassuring, but non-specific noises about Q2:
We look forward to reporting deal flow and business progress as the Group enters the traditionally busy second quarter. We will provide a further update in the Interim Results.
My opinion - this share has now recovered by about 50% from the low after a profit warning late last year. So it would have been a good falling knife to catch.
That said, my reservations about this company persist. In particular, its profits seem lumpy, due to a reliance on winning high margin licences in Q4 each year. Success or failure in this regard can mean the difference between good, or bad profits for the year.
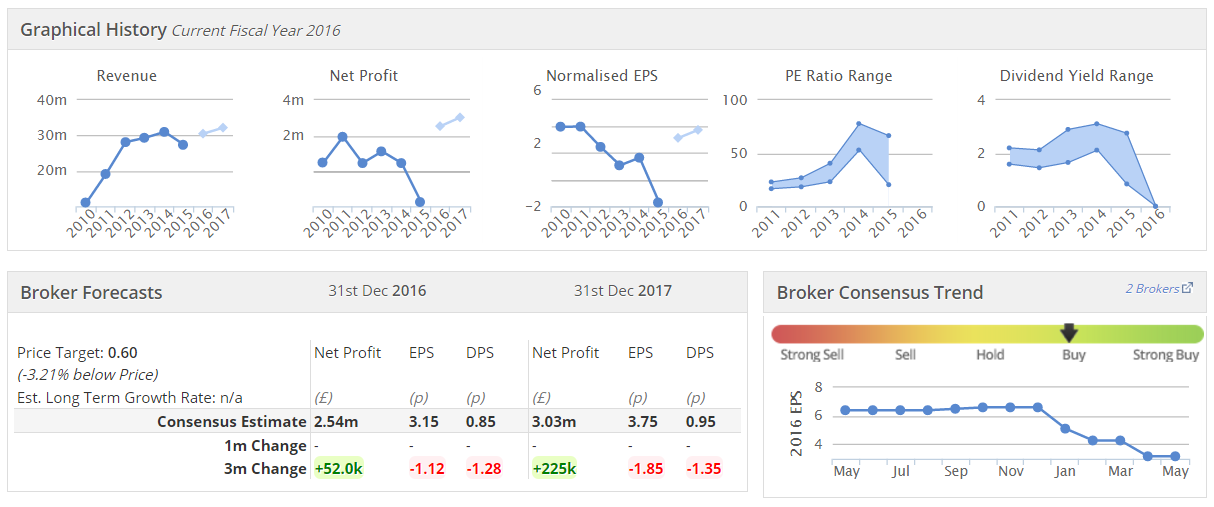
Broker forecasts are therefore little more than guesswork. So I don't see any reliable way to value this share. If you buy the share, then really you're just backing management and hoping that they will perform.
The divi was passed last year, but brokers are now forecasting a resumption of divis this year.
Even if broker forecasts are achieved for this year and next, the share wouldn't be cheap, on a PER of 18.4. So buyers of this share now must be assuming that the company can beat forecasts. It might do, if the right combination of licence wins are achieved. Or, it might not.
I prefer to have more visibility of earnings, so this share is not for me.
Restaurant (LON:RTN)
AGM remuneration vote - it's always pleasing to see shareholders bare their teeth at overpaid Directors. Executive remuneration generally is an absolute scandal, in my view. All too often mundane management are paid outrageously high remuneration packages at listed companies. This happens for a very simple reason - because there's little to stop them doing it! A large number of shares are held in forms which cannot or won't be voted at AGM - e.g. shares held via spread bet or CFD usually won't carry any voting rights. Or funds held in trackers, or other passive investment vehicles. Plus a certain amount is in the morgue, as it can take a very long time for executors to liquidate portfolios of deceased people.
This means that many listed companies effectively have an absentee shareholder base. Management cotton on to this, and ratchet up their own remuneration with impunity. Every company seems to think it has top quartile quality management, which of course is an impossibility!
So I love it when there's a big vote against the remuneration report at AGMs.
RTN shareholders voted 26.3% against the remuneration report. That may not sound much, but many Institutions usually don't like to rock the boat, or just can't be bothered. So it's actually quite a significant sign of shareholder disquiet. I don't blame them either, as judging by the last conference call, the CEO gave a lamentable performance, and gave every impression of being bottom quartile. The collapsing share price has also not endeared the company to its shareholders.
The company published this response yesterday in the notes to the announcement:
The Company notes the significant number of votes cast against Resolution 2, the advisory vote on the Directors' Remuneration Report. The Company understands that this reflects the concerns of a number of investors in respect of the termination arrangements for Alan Jackson and the level of the Executive Director annual bonus awards for 2015. The Remuneration Committee will carry out a detailed review of all of the feedback received to understand fully all of the reasons behind the vote result so that it can reflect, where appropriate, in its approach going forward.
At least the company has sat up & listened.
There's nothing else of interest today, so I'll sign off for the day.
Regards, Paul.
(usual disclaimers apply)
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

23 comments
Restaurant (LON:RTN) looking perky today since Sky News reporting Cinven & others are considering a bid:
http://news.sky.com/story/1698794/cinven-eyes-bid-for-ailing-garfunkels-owner
Hi Paul, great article as always. I wondered if you had any thoughts on the announcement from 32red today striking the deal with Leeds?
Hi bpdm,
No, I haven't seen that announcement.
I only tend to deal with results & trading updates. Plus anything else which moves the share price more than about 10% on the day.
Those filters mean I tend to catch most things of interest. But there's only so much one person can cover from 500+ small cap stocks.So inevitably things slip through the net.
Why not do a quick precis yourself here, if you think something looks interesting?
Regards, Paul.
Just on IPOs, I've heard a couple of people say that there's a bit of a rush on to beat the Brexit referendum. I assume that's because sellers figure that if we get a leave vote then the markets will be shut to new entrants while the dust settles. Normally investing in IPOs is a mug's game because the insiders have control of timing, but if everyone's in a rush to market to beat the referendum date there may be the odd decently priced company coming to market.
However, I can't say that HOTC or MOTR float my particular boat,
timarr
Re Motorpoint.
they make money purely on the metal, but the car is simply a perfect asset to hang a load of 'added value' products that wouldn't otherwise exist. Motorpoint have a very strict sales process that is designed to generate the maximum penetration of these products. The list includes Finance, Paint protection, service plans, Gap insurance , tyre Insurance etc etc I believe the key risk here is that the FCA get more heavily involved in defining what are appropriate add ons, imho many of these products have unduly high margins or are of dubious worth to the customer . If the FCA deems these areas to be potential miss selling then the fall out for car dealers and in some cases the product providers for whom they act as agent could be painful.
I wouldn't touch this IPO with someone else's barge pole but others will feel the opposite!
From RTN response
The Remuneration Committee will carry out a detailed review of all of the feedback received to understand fully all of the reasons behind the vote result so that it can reflect, where appropriate, in its approach going forward.
What a load of bull .. we all know what that means ... We will find a way of supporting all remuneration in a way that stops unwanted intrusion from shareholders so we can continue to rob them blind by extracting huge salaries for our directors as they are irreplaceable and we have to pay them a compatible reward for the industry standard to retain their service for longevity and for the good of all the miserable frontline staff that earn a pittance with no guarantee of work for any length of time.
Total corporate robbery.
Had a quick look at £MOTR website, their cars don't look that cheap to me, only about 15-20% off new list price, well you can usually get a discount off new price.
Re IPOs, yes some are overpriced, some have problems that surface within a year or 18 months but overall they are no worse than the market in fact have done better according to this: http://www.stockopedia.com/content/uk-ipo-performance-analysis-12-months-to-oct-2015-update-452016-112905/
Re. £MOTR
For those who are interested in digging further, the admission document hasn't yet been loaded on their website.
http://www.motorpointplc.com/investor-relations/document-library/
I phoned their PR firm and they said it will be uploaded "some time today" . Some sort of glitch apparently.
Thanks for a detailed report Paul in spite of your hols.
Thanks Ramridge for the information on both HOTC and MOTR.
My own opinions, for what they are worth:
Overall, owing to the high number of IPO disasters, with regular warnings within a short time of floatation, I am REALLY sceptical of IPOs now until a proper market record is established by each company. On the other hand, I suppose it is possible to make a quick buck out of floats, if one can get on board in time... or at actual float.
HOTC to me sounds dodgy based on the link posted. I think their chocolates are very overpriced... although I was given two boxes for Christmas and so they did okay there I suppose in relation to other brands; I consider myself somewhat of a chocolate connoisseur, and personally I find their offerings a bit too rich, and frankly several flavours in one box tasted a bit odd. Will stick to my supplier of yummy handmade chocolates in Belfast which are rather cheaper! Oh, and if you are in Dublin, visit the Leonidas chocolate shop... FAB chocs!
MOTR, hmm... well the pricing admission document is there now... perhaps the delay was the same kind of delay as I see upon looking at their site where for many vehicles it says "image coming soon"!! As far as I can tell (from a quick skim through - am busy at work... or supposed to be, she said, typing away) I can't even see a proper section which says "Reason for IPO and intended use of proceeds"; I could have missed it, but if not, how odd!!! Maybe Mr Shelton and his wife wish to further enrich their lives with the significant proceeds while the vehicle market is strong and the 200p floatation price can be justified; this isn't a criticism by the way, just an observation, am sure they've worked hard to build up the business and as Paul highlights the financial record looks good. The only comment I can see is " we believe that this listing on the LSE will provide the catalyst to take the Company to the next stage of its growth"... but what is that, exactly?!? Perhaps it is to open a branch in Northern Ireland which would then be convenient for me! :-) I looked at the site, and it's quite slick. Price-wise the keenness, or otherwise, of the prices seems to vary on model - I checked the VW Tiguan (which I bought in mid-Jan, 2014 64 plate) and their price is £3200 cheaper than my dealer price (which in itself was quite competitive compared to what was around)... but then I had my own car to part-ex, and I negotiated over £1000 off the price to exchange, I also got a year extra warranty and two years breakdown cover... so considering my geographical disadvantage I doubt I would have considered heading over to GB to make use of Motorpoint on this basis... especially as my traded in car also had a worn clutch which together with replacing the flywheel would have cost me £1500... which my dealer didn't detect until on the day of sale after I had signed all the paperwork :-)
Well, there you go.... ramble, ramble; have a nice weekend everyone!
Re. £HOTC
I had a good look at this IPO and generally liked it. I was on the point of taking a stake when another investor drew my attention to the following article:
http://www.shareprophets.com/views/20645/hotel-chocolate-a-house-of-cards
This refers to the sale of a St Lucia subsidiary to HOTC which was substantially owned by two of the directors.The admission document is pretty opaque about the terms of this connected party transaction.
So this violates one of my basic rule, don't invest in a company when you cannot trust the management, especially if it is an AIM company.
Until more light and evidence are shown that this transaction was above board and fair, I will watch from the sidelines.
BTW, Hargreave Hale have taken a 5% holding in this IPO too.
Hi Ramridge,
Re HOTC - the issue of the company buying a subsidiary from the Directors, 2 weeks before IPO, looks to me like a tidying-up exercise before floating. A similar thing happened at Entu (UK) (LON:ENTU) before it floated - all the Director loan accounts had to be tidied up.
I think if HOTC had floated without doing this, then investors would have kicked up more of a stink that some of the group was owned separately by the Directors. Bringing it all under one roof for the IPO makes sense to me, and seems much cleaner.
Although it depends whether the price paid was reasonable or not, of course.
The other points that Nigel Somerville mentions in his article seem relatively trivial to me. I read his article, and thought to myself that none of the points he mentioned would have any bearing on how I would value the company, or the investment case for the shares.
I don't know whether he queried any of the points with the company before publishing? I find that sometimes people put 2 + 2 together and end up with 5, if they have jumped to conclusions on things without actually asking the company for an explanation. That happened with the silly articles on ShareProphets about Trakm8 Holdings (LON:TRAK) - where I ended up having to spend 2 days preparing 50 questions, and interviewing management, and basically everything bar one relatively minor point that the bears had come up with was incorrect!
Regards, Paul.
Hi Paul,
Thanks for the write of £MOTR. As you say PI's are sceptical of IPO's given recent floats and the profit warnings that have tended to follow 6-12 months after listing. Whilst its reassuring to see established names such as Hargreave Hale and Miton on the share register this isn't a guarantee of success by any means. I seem to recall the shareholder of register of DX (Group) (LON:DX.) had some stellar institutions, and Slater invested in Lakehouse (LON:LAKE) and both issued profit warnings within a year of listing. Just goes to show the risk of recent IPO's and taking the other side of the trade when a company first lists.
Like you say the progression in profits at £MOTR has been impressive, but why are the sellers looking to sell out now? Are we at the top of the cycle? I don't know but why take the risk.
Best wishes,
Imran.
I'd be a bit cautious on it too - it look expensive compared to other motor retailers:
http://www.stockopedia.com/compare/?tickers=LON:PD..
They have all sold off quite a bit this year too, so presumably the owners of Motorpoint also think it is a good time and a good price to sell some stock as the Car market seems to have pretty much recovered now. As you say Imran, maybe it could be the top of the cycle peak given borrowing are back close to highs from before the crisis and savings rates unsurprisingly at pre crash lows given the on going low rates, what could possibly go wrong?
The first company I owned shares in which went bust was The Car Group Plc. Which owned car supermarkets. They were caught out by currency movements which impacted sales prices for secondhand cars and therefore stock values. As we seem to have climbed the wall of worry for the car dealers generally I worry that the directors of £motR are selling at the top and there may be significant risk.
Hi Richard,
Good point about secondhand car residual values.
My view is that, with the very large number of new cars being bought under personal leases, this is likely to cause over-supply of used cars, 2-4 years old, once the initial lease expires.
So I'm wary of companies holding very large amounts of secondhand car stock. There again, the stock turns quite rapidly - I think Motorpoint said it turns its stock about 10 or 11 times per annum. Therefore the impact of price deflation should not really be much of an issue.
I hadn't thought about currency movements affecting secondhand values, but it's a good point to mention, thanks.
Regards, Paul.
Paul,
Surely one other thing to consider with Motorpoint is that unlike mainstream car dealerships they will get no revenue from servicing, so there really is no other revenue stream if car sales dry up. I'd also question how the operating margin jumped so much in the year before it goes to IPO. Is there a possible whiff of some window dressing?
All the best, Si
Thx Paul. Stock turn was also fast at The Car Group. Until the market dislocated and suddenly it wasn't.
Hi Paul, I agree residuals seem likely to fall, any idea which companies are the most exposed?
Just a quick note on financial analysis, if I may (and apologies if what I'm about to say is too obvious).
Paul, you've said before that statistics like ROE are less important to you than Operating Margin.
On the other hand, I note that you also like to keep an eye on stock turn, e.g. with £MOTR.
Perhaps this is stating the obvious, but Return on Equity is just the product of two things which are conceptual cousins of Operating Margin and stock turn, namely Net Profit Margin and Equity Turnover.
Net Income / Equity = (Net Income / Revenues) * (Revenues / Equity)
So Return on Equity = Net Profit Margin times Equity Turnover.
We can make similar formulas for Return on Assets, Return on Capital Employed, etc.
Net Profit Margin is not exactly the same thing as Operating Margin, and Equity Turnover is not exactly the same thing as stock turn, but I hope this goes some way to illustrating why ROE has the potential to be a really useful ratio - it is the product of two other simple and very useful ratios, which I think Paul you are effectively already investigating as a matter of routine anyway!
Regards
Graham
Hi Graham,
I'm sure that's all right, but it's all just too "textbook" for me.
I studied things like that before, but it left me cold.
For me, with small caps, it's all about pondering all the numbers, then just doing a "is this reasonable?", "does that look right?" type of thought process.
Remember that the figures are moveable to (within reason) to anything management want to show. So you can't trust the figures from any company. If management are fundamentally dishonest, then they have remarkable scope to flex the figures within a far wider band than most investors believe possible.
Someone said to me the other day, "the figures don't lie", and my immediate response was, "they very often do!"
That's different from the point you were making of course. I'm sure you're right about ratios, etc. That sort of stuff, ratios, doesn't work for me though. It's not really a science what we do, it's juggling lots of supposed facts, with lots of unknowns, then trying to predict the future.
Regards, Paul.
Hi Paul, again I think we both agree with each other on 99% - and for the benefit of doubt I'm not trying to suggest that ROE is a magical number which takes away the need to apply judgement, common sense or further digging. But Stockopedia does use it along with similar ratios and I'm simply pointing out that one way of understanding why it is a proven "quality" metric is that it does a decent job of flagging up a weak operating margin or stock turn, which are metrics you already check (to the extent that they feed through to net margin or equity turnover).
Best
Graham
To me, equity turnover is a theoretical and not very meaningful number.
Stock turn is always important and can be directly compared across similar businesses. Can raise suspicions about unsaleable stock. The value depends on where the year-end is in relation to the business, but still very useful as long as the company doesn't have too many components.
Absolutely outrageous Paul, the fact that you took a day off too relax while on holiday like a normal person makes me very angry!!