Small Cap Value Report (13 Sep 2016) - CHRT, FLO, GOAL

Good morning!
We have about 20 people coming along to ShareSoc Brighton tonight, which is (just) above the threshold where it's worth doing. So I'm putting the finishing touches to my talk on small caps.
I'm dreading the train journey from London to Brighton. It's bound to be packed full of people who've thrown a sickie from work, to do some sunbathing! Summer is putting in one final appearance today apparently.
Cohort (LON:CHRT)
Share price: 315p (up 1.6% today)
No. shares: 41.0m
Market cap: £129.2m
AGM statement & Q1 update - this group of defence sector companies has a 30 April year end. So it's reporting today on the first quarter (May, June & July), although the figures given are as at 31 August, so that's actually 4 months, and not just Q1.
Anyway, the order book looks strong, and the all-important in line with expectations message is given;
The Group's order book stood at £128m as at 31 August 2016, underpinning a higher proportion of our externally forecast revenue for the year compared to this time last year.
The pipeline of orders beyond this and expected renewals give us confidence that the overall performance for the year will be in line with expectations, despite SCS's market in technical consultancy remaining a challenge.
The cash position remains healthy, although note that most of it is ear-marked for hoovering up minority shareholders in existing subsidiaries;
"The group's net funds as at 31 August 2016 stood at £14.4m. The reduction in the Group's cash position since the year end was as signalled in our final results statement, stemming from the partial reversal of working capital inflow during a very strong fourth quarter of last year.
A further £9m is expected to be spent in the rest of this financial year in acquiring a further 23% of EID, taking our holding to 80%, and the remainder of the shares (49.999%) of MCL, taking our holding to 100%.
That all sounds fine to me. Also, note the valuation is hardly demanding;
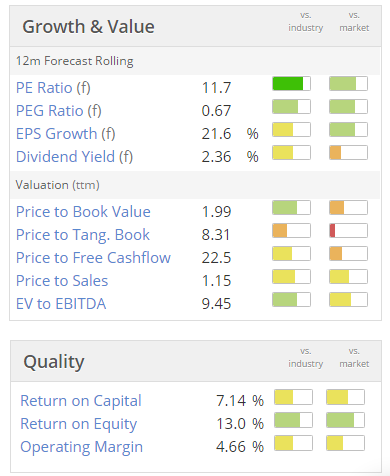
My opinion - it looks good value to me. Although I'm not madly keen on this sector, as contracts can be lumpy, leading to the ever-present risk of a profit warning. Or, something might go wrong with a major contract.
Mind you, at the current valuation, the risks seem priced-in, and overall I could see maybe 20-30% upside from the current price, so it's tempting.
Flowtech Fluidpower (LON:FLO)
Share price: 130p (up 0.6% today)
No. shares: 43.1m
Market cap: £56.0m
(at the time of writing, I hold a long position in this share)
Interim results, 6m to 30 Jun 2016 - this was one of my post-Brexit bargain purchases, at 102p, and it's bounced nicely from there. There was never a particularly valid reason for it to have fallen sharply, in my view.
Since joining AIM in 2014, FLO has made 6 acquisitions. Growth reported today has mainly come from acquisitions. Some key figures for the 6 month period;
Revenue up 28% to £27.4m
Underlying operating profit up from £3.4m in H1 2015, to £4.06m (up 19%)
Net debt has risen substantially though, to £14.1m
Dividends are quite good here - the forecast yield is 4.5%. The 5% rise in interim dividend looks consistent with the full year forecast divi.
Outlook comments are interesting, but reassuring, despite difficult market conditions;
Low global confidence and economic uncertainty is influencing many industrial sectors, particularly in the UK. We do believe this hiatus to be short term, and remain confident for the future.
As we previously indicated, the Group operates in a "live" pricing environment and it is increasingly certain that input prices for many core product lines will increase in HY2 and early 2017 on the back of the sterling downgrade.
The Board is confident that we will be able to maintain overall margins by a mixture of selling price increases and supplier support.
The fluid power sector as a whole has come to expect a heavy bias towards US Dollar and Euro denominated supply lines and the macro economic situation is well understood by the sector's decision makers.
Trading is in line with management expectations despite some disruption over the immediate post Brexit vote period.
Overall, we remain positive that we can deliver results in line with market consensus forecasts and are confident about the future.
Our acquisition pipeline remains dynamic and the Group is now established as a very credible option for investors and owner managers across the sector who wish to exit their position.
Valuation - the PER is only 8.4, based on forecasts which the company is effectively confirming above. That seems good value to me, although of course the significant net debt has to be taken into account for valuation purposes.
Balance sheet - overall looks OK to me. Intangibles are high, but even after writing off all intangibles, the NTAV is still positive, at £6.4m
My opinion - I like it. This group has a good niche position, distributing a wide range of essential maintenance parts for hydraulic equipment. So the key success factors are having the right products in stock, and being able to deliver products to customers very quickly.
The nature of the business is that good margins can be made, and FLO also seems to be doing a good job in bolting on complementary acquisitions. The balance sheet is under control, and there's also a nice divi. The forward-looking comments seem encouraging too.
Therefore it's a company I like, and on the back of these interim figures am happy to continue holding for another 6 months.
FinnCap has put out a supportive note this morning, with minor tweaks to its forecasts, but not affecting EPS for this year or next. FinnCap notes that FLO is priced at an unwarranted discount to its sector.
Goals Soccer Centres (LON:GOAL) - this one might be worth a fresh look. I've had a very quick skim of its interim results today, and it seems to have turned a corner;
LFL sales are now positive again, in the last 11 weeks.
The balance sheet looks tons better, after a recent fundraising.
This share is starting to look potentially interesting, in my view. I wouldn't be surprised if somebody bids for it, as there's an obvious fit with a company like Sports Direct, which is on the shareholder list already, I believe.
I'll have to leave it there for today. See some of you tonight, and everyone else tomorrow.
Regards, Paul.
(usual disclaimers apply)
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

23 comments
My little memo on Cohort written a fortnight ago
'Problem here is the possible exit of Scotland from the Union and the likelihood of an end to Trident if that occurs. Otherwise a vg company and perhaps at 300 worth buying for a probable bumper year in 2018'
The Sharesoc do sounds interesting, but getting from Milton Keynes down to Brighton for a mid week evening do is difficult, with other commitments like work.
The Sharesoc do sounds interesting, but getting from Milton Keynes down to Brighton for a mid week evening do is difficult, with other commitments like work.
People have travelled down from France, Leicester, and even Abu Dhabi to hear my small cap talks in Brighton.
You're complaining about Milton Keynes?!!!
Hi Paul
Any view on IQE?
IQE - no I didn't have time to look at it, and don't feel I have any understanding of their business.
The clue is that I didn't report on it originally.
PP.
Hi Paul, you have previously covered STM, which has published it's results this morning.
The revenue and Profits have dropped but the forward looking statement is interesting.
Just wondered whether you would have time to review them tomorrow perhaps? Would be interested in your thoughts.
Regards
JKT
STM (LON:STM) - look at cash flow though - it's well above profit. It looks very cheap on fcf/EV basis imo and with positive outlook to boot.
>>Costs of imports are bound to rise, this will bring about inflation, which in turn will push up interest-rates>>
Not convinced by that. RPI averaged 5.2% during 2011, caused, I think, by commodities going on a tear due to a construction boom in China. The BoE could see that inflation wasn't caused by increased consumption or wage inflation at home, and sat on its hands.
OK. As promised, some thoughts on K3 Business Technology (LON:KBT) .
- CEO is becoming chairman and search for a new CEO is in advanced stages. The CEO looked a bit jaded to be honest so I think a change is not necessarily a bad thing.
- The business model is moving from one-off up front payments to per user per year type which impacts on cashflow in the short term but is more lucrative longer term. It's a model that many other suppliers are starting to adopt with Microsoft actually refusing to do anything else for some of their products.
- Restructuring costs are specific to this year (business too big in one geography and synergies being realised in another region). The recent acquisitions won't attract any restructuring costs although it has to be accepted that any new CEO might want to reshape things....
- Recent acquisitions expand geography into Scandi and Germany (DdD) and vertically (Merac)
- MyLocal going into admin cost £830k. No chance of getting anything back.
- On track to be debt free by 2018 (although with the changing cashflow profile I'm not so convinced by this - heading in the right direction though.)
- Pipeline at record levels
- Dividend growing by 0.25p each year. It's covered 14 times so maybe there's something that could be done here?
If you knock off this year's restructuring and acquisition costs and take out the MyLocal impact the market expectations for next year are virtually in the bag already. With the pipeline up 23% I would imagine that there's scope for an upgrade all things being equal.
Draw your own conclusions as to whether it's good value at this level or not.
JDW72 (no position)
K3 Business Technology (LON:KBT) is down 40% today.
Brexit has not yet seriously affected FLO, but it is early days. We ain't seen any of the potential
nasty effects of Brexit yet. Costs of imports are bound to rise, this will bring about inflation,
which in turn will push up interest-rates - which would spell gloom for the construction industry
IMO..
Paul
I'm sure readers would appreciate a transcript of your talk at tonight's ShareSoc event.
.
Encouraging half year report from Keywords Studios (LON:KWS) - up 5.8% as I type. I'm a holder
http://www.investegate.co.uk/CompData.aspx?code=KWS&tab=announcements
Don't know if I'd recommend buying shares in Thalassa Holdings (LON:THAL). They've gone from being a pure value share IMO to blowing all their cash on non-core investments.
I would however definitely recommend reading the chairman's report as mentioned by grb! Always interesting.
Paul
Are you not concerned that the returns FLO makes are derisory and that it ,as Charlie Munger puts it ,over the long term the share price will match the ROCE of a company ?
Hi Paul, regular reader but infrequent commentor here. Thanks for all the reports, always interesting. Did you manage to get any info on Redstoneconnect (LON:REDS) as per your report last week? Tough business to find anything substantive out about, if you have any broker thoughts I'd be interested. I have a feeling that the data on Stockopedia forecasts isn't right, can't believe the forward PER of 2.3! Thanks
Hi DurhamMike,
I visited Redstoneconnect (LON:REDS) at their office recently actually.
It's on my watchlist. I like the CEO & FD, but wasn't convinced the value right now is good, in terms of risk:reward.
The broker forecasts look nonsense to me, so the PER would be too.
I'll keep an eye on it for the next 2 years. Could become interesting in due course. But I would ignore that daft forecast.
Regards, Paul.
Thanks Paul, look forward to getting a better understanding of it over time, the space is certainly interesting.
Best
Mike
Thanks as ever, Paul. Today's update from Thalassa Holdings (LON:THAL) has one of the most unrestrained commentaries I've seen for a while - makes for entertaining reading.
It certainly does.
A classic report! Thanks for the link.
Hi Paul,
Interesting thoughts as always. The defence sector is one that I don't like investing in (not some moral highground but it feels like a bet on an uncertain future) but I think we are entering an unsettled period in Europe and Asia and can see defence spending rising, possibly sharply. Sadly.
Interesting RNS from Ensor Holdings (LON:ESR) today which I will try to unpick later. Basically half the market cap is now cash and they're trying to flog the last two bits of the business which seem to be trading well. Would be interested in your 4p worth.
I'm also seeing K3 Business Technology (LON:KBT) management in an hour (released "broadly in line" finals which I think would have been "in line" or "ahead" had it not been for a customer going into administration but a +ve outlook). Will report back.