Small Cap Value Report (14 Oct 2016) - INL, EHG

Good evening,
Apologies for my running late today, this is due to it being Friday, and there being hardly any news of interest today, so I had a lie in.
I'm delighted to read that Tesco & Unilever have resolved marmitegate, although no details of the compromise deal have been released. I think Tesco has played a PR blinder here - setting itself up as the consumers' champion by resisting inevitable price rises from suppliers, which are being triggered by weaker sterling.
We have to prepare for the inevitable higher inflation, and therefore probably a consumer spending slowdown. I'll be sifting through the market over the weekend, making a list of things to open some small short positions on.
I'll update this on Sat or Sun, too tired now, sorry.
OK, here goes, second attempt (it's now Sunday lunchtime):
Elegant Hotels (LON:EHG)
Share price: 64.5p
No. shares: 88.8m
Market cap: £57.3m
Trading update & new management contact - this is my first commentary here on this particular company. I did glance at it when it floated, in May 2015. However, seeing as though its operations are overseas, and it was listing on AIM, that was enough to put me off - that type usually seem to go wrong. Also there's debt on the balance sheet.
I'm very suspicious of all IPOs to begin with - why does the existing owner want to sell, if things are supposedly going so well? Often there's an ulterior motive behind IPOs - the vendor wants to get out because either the price is too high, or the business model is likely to worsen in some way in future. Therefore I'm not usually interested in taking the other side of the trade from the person who knows it best (the existing owner).
Looking back at the first RNS, in May 2015, there is some interesting info. The IPO was done by Zeus Capital, and sought to attract investors with an initial dividend yield of 7%. I got caught on one of these, namely Entu (UK) (LON:ENTU) - also a Zeus float, with a big initial yield. The shares have absolutely tanked, and the divis have been cut.
So already the red flags are mounting, before I've even looked at EHG's figures.
Elegant Hotels describes itself as the;
...owner and operator of six upscale freehold hotels and a beachfront restaurant on the island of Barbados.
I like the fact that it owns freeholds. Tangible assets are always good, and to my mind freehold property is the next best thing to cash.
Trading update - this sounds reassuring;
Year to 30 September 2016
The Board is pleased to report that it expects that the Group's full year results for FY16 will be in line with market expectations.
What are those expectations then? I do wish companies would state the precise figures they are referring to, when quoting market expectations. That would save readers of the RNS a lot of time, and would prevent any confusion over numbers.
Stockopedia shows the broker consensus for y/e 30 Sep 2016 as being US$ 0.12, so that's about 9.8p. At 64.5p, the rating looks very modest indeed, at a PER of only 6.6.
Note how broker expectations have been revised down quite a bit in the last year though;
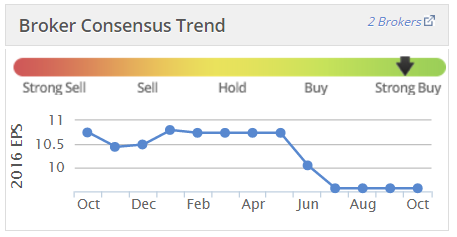
Note that this company reports in US dollars. So earnings, and the company as a whole are now worth more in sterling terms - the share price is quoted in sterling;
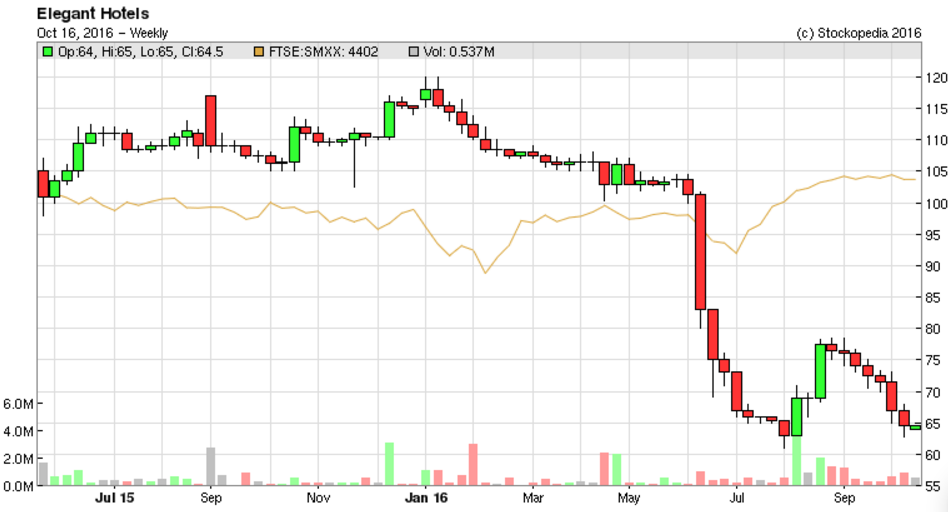
With the share price at a low, dollar earnings (a positive thing for UK investors), and an in line trading update last week, plus freehold property, I'm starting to get interested. More research is required.
Reliance on UK customers - I've been reading the admission document, and think I've found a snag. There is a very heavy reliance on UK customers, and with sterling having devalued sharply of late, this means overseas trips are now more expensive for UK residents;
About 70% of the Group’s revenue is from the UK. Barbados has long been a popular destination for UK travellers. Both British Airways and Virgin run daily non-stop flights during peak periods from London Gatwick (see paragraph 4.1 of this Part 1).
Guests from the UK are particularly important to the Group because their average length of stay is typically about twice as long as guests from other markets such as the USA (the second most important source market for the Group).
Oh dear. That doesn't augur well for 2017 bookings. Mind you, I read something recently which said that UK consumers rank their main holiday as being second only in importance to groceries shopping. So perhaps customers from the UK might keep going to Barbados, and just cough up the extra cost in 2017? There's bound to be some reduction in UK tourists visiting Barbados in 2017 though, so I think this means a heightened risk of a profits warning in 2017.
New site - Waves Hotel & Spa - the latest update on this sounds encouraging;
Elegant Hotels announced in August that its recent acquisition, Waves Hotel and Spa ("Waves"), is now open for business, having been extensively redesigned and refurbished after it was bought by the Group for US$18.0 million in March 2016.
Early feedback from both customers and travel agents has been positive and, as expected, the property is already proving to be highly complementary to the existing portfolio.
The Board expects Waves to be earnings enhancing for the Group in FY17, with excellent potential for further improvement in FY18 and beyond as the property develops its reputation.
New hotel in Antigua - the group has also announced that it is taking on a new hotel, owned by a third party, and under construction, in Antigua. This is being done on a management contract. Financial details have not been given, but they expect it to be profitable.
Dividends - the latest update on this is also reassuring;
As previously announced, the Board has declared - and the Company has paid - an interim dividend for the period to 30 September 2016 of 3.5 pence per ordinary share.
The Board intends to follow this with a second dividend of 3.5 pence in February 2017, representing a total of 7.0 pence per ordinary share for the year ended 30 September 2016.
That's a spectacular dividend yield of 10.9% - a yield that is so high, the market is clearly signalling that it regards this as an unsustainable payout. If the market is wrong, and this high yield can be sustained, then it's likely to drag the share price up.
The company reckons it can maintain the divi, and specifically mentions why;
The Company remains adequately resourced in the short to medium term and, with the additions of Waves and the New Management Contract and the anticipated delivery of these recent growth measures, as well as the gradual return of UK consumer confidence in the longer term, the Board believes it is well positioned to be able to maintain the dividend in the future based on its current estimates.
That wording leaves wiggle room to reduce the divi, if estimates change. Also I think it's odd that there is no mention of the fall in sterling, and the likely impact of this.
Current trading & outlook - so far, this sounds OK;
The Group is only 14 days into its new financial year and, whilst it appears UK consumer confidence is returning, the political uncertainties in the UK over the summer months are, it believes, responsible for bookings for the current financial year tracking slightly behind the same period last year.
Given these recent booking trends, the Board believes it is prudent to have a cautious outlook, with Group revenue for the current year currently expected to be broadly flat in comparison with FY16.
EDIT: Zika virus - I've just picked up on a reader comment. JohnEustace points out below that Barbados has been affected by the Zika virus. I confirmed this from a website referred to from a UK Govt website, here.
The Zika virus is mainly spread by mosquito bites, according to the above website. As I discovered this year in Greece, even if you cover yourself in repellents, you still get one or two mozzie bites. So the travel advice to "avoid mosquito bites" is close to useless!
From the small amount of googling I've done, the main problem with the Zika virus seems to be in it causing birth defects in pregnant women. There's more info here. Whether this would be enough to deter other people (i.e. everyone other than pregnant women) from visiting Barbados, I don't know.
My opinion - I'm in two minds about this share. It's a proper business, with a good track record before & after IPO. It's generating real cashflows & paying huge divis. There's also asset-backing, with NTAV at £96.5m, which looks attractive compared with a market cap of £57.3m.
On the downside, it's overseas & AIM, although management seem to have solid backgrounds. Moreover, Barbados has a British legal system. I've googled "Barbados corruption", and get conflicting results, as follows;
Barbados.org provides statistics which show that Barbados is one of the world's least corrupt countries here.
Barbados Today clearly didn't get the memo, as their interview with a former Chief Justice here declares - "We're corrupt!", and that the problem has been swept under the carpet for years.
Mind you, we're hardly in a position to talk here, after all sorts of scandals seem to surface on practically a daily basis here in the UK. So I don't think we can occupy the high moral ground any more.
The main problem with Elegant is, I think, that a decline in UK visitors to its hotels, which constitutes 70% of its business, seems inevitable now that sterling has greatly devalued against the US dollar. I suspect that current hopes for flat revenues may turn out to be far too optimistic.
For this reason, I'm not going to be buying any shares in Elegant, although it's going on the watchlist as something I might buy if it crashes on a profit warning in 2017 - which looks possible, even likely.
The share price looks to already be pricing-in future problems. However, experience has taught me that shares still drop 30%+ when the eventual profit warning is issued.
EDIT - I've had a look on Expedia, to see what prices Elegant Hotels charge, and am quite shocked by the results! Their hotels are massively more expensive than most other Barbados hotels, so it looks a fairly high end operator. They've got good reviews too from customers. Which makes me wonder how much people will be deterred by the exchange rate? After all, if you can afford to spend £10k per person for a 2-week stay at The House, then are you really going to be that deterred by paying more due to sterling depreciation? Here's the link to Expedia, which may or may not work.
A quickie to round off with;
Inland Homes (LON:INL) - results y/e 30 Jun 2016 - housebuilders are so difficult to value at the moment, because nobody really knows what the future holds for house prices. A long period of unprecedentedly low interest rates has driven an asset price boom. Mortgage availability has been steadily improving in recent years, and the latest deals look extremely cheap. Government has further stimulated demand for new houses through its Help To Buy scheme. Although I note that part of that scheme will soon be dropped.
EPRA valuation of net asset value can be useful, trying to find a reasonable valuation for property companies, as it boosts NAV up from cost prices of projects, to estimates of their current worth. This table provides EPRA valuations for Inland Homes. I'm most comfortable with the highlighted figure, which takes into account dilution from share options, and tax.
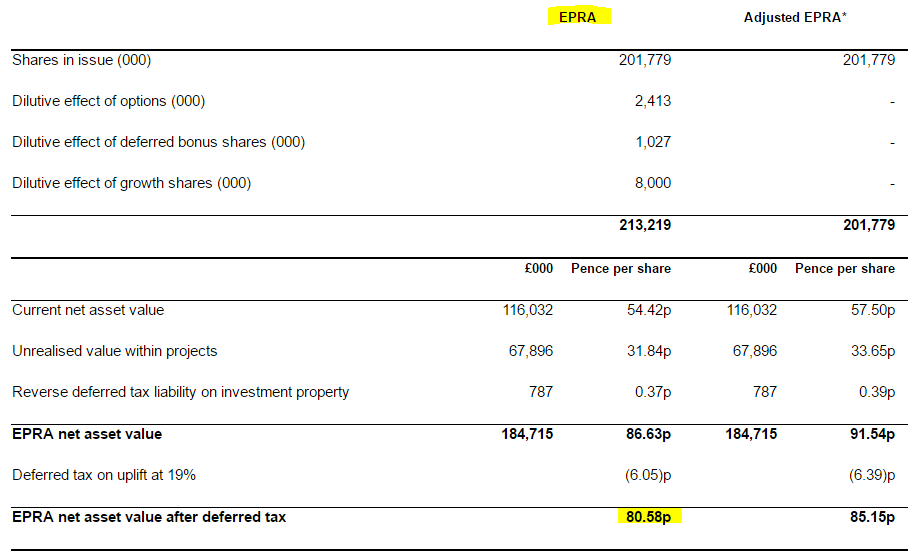
The share price is currently 61.6p, so that's a useful discount to the 80.58p EPRA valuation figure above.
Most property companies learned the lessons from the GFC in 2008, and have built up their balance sheets, taking on much less debt than in the last cycle. So they should be much better placed to survive the next recession.
Inland's balance sheet look fine to me.
It's been very profitable too, making £32.9m profit before tax on turnover of £101.9m. With a slowing economy though, and all the other issues we have at the moment, I wouldn't want to bet on profits being sustainable at that level. That's why housebuilders should never really be valued on a PER or yield basis - the sector is too cyclical.
My opinion - I think this sector is just best avoided. There are too many uncertainties, and I think the risks have increased after sterling's large recent falls.
That's it, see you in the morning!
Regards, Paul.
(usual disclaimers apply)
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

32 comments
The phrase 'follow the money' borrowed from the 1970'S movie, 'All the Presidents Men' is generally a truism insofar as investing is concerned. On a medium term risk reward basis Elegant Hotels at the current price is in my view a convincing investment opportunity provided that the information presented by the Company is a fair and accurate description of the present situation. I would add that I have no reason to believe that this is not the case and hold a long position. Clearly Luke Johnson agrees as he would not have purchased a 10% holding without completely significant due diligence
In addition to the recent purchase by Luke Johnson, the list of institutional investors with sizeable holdings is impressive and includes Slater Management, Miton, Artemis, River and Mercantile and Schroders, which brings me back to where I came in....'follow the money'?
They could all of course be wrong, but a least if this ultimately proves to be the case there will be some solace in knowing that people much wiser than me have also messed up.
As always DYOR.
news just in (28th Oct) - serial leisure entrepreneur and investor Luke Johnson (and chums) have picked up over 10% of Elegant Hotels. Opinion can be split on LJ. I followed him into what was Eclectic Bars - it soon became Brighton Pier and significantly re-rated. It's a punt, I grant you. If the dividend holds though?
I spent a little bit of time looking at Elegant. There's an interesting slide in their 1H results presentation (http://www.eleganthotelsgroup.com/media/1123/elegant-hotels-h116-results-presentation-final.pdf). If you look at slide 16, it says that arrivals to the island are +7.4% but demand for luxury accommodation down 3.7%. They appear to have done a bit better. They maintained their REVPAR (revenue per available room) by increasing the rate but their occupancy dropped 2 pp. I think I read elsewhere that Airbnb was popular amongst some of the US visitors who appear to be behind some of the increased arrivals. Might explain why they don't seem to be able to capture any of the increasing number of visitors to the island.
They say that prudence suggests they should budget for flat revenues. I don't follow the company closely enough but how are they treating the acquisition of Waves in that statement? When was the refurb finished? Is the flat revenue on the 483 hotel rooms ex Waves or is it on the 483 + 70 rooms (including Waves)? If the latter, that's not a great outcome on a 70/483 uplift in room stock especially if Waves is open during the busy season this year when it wasn't (or wasn't owned) last year.
There was an interesting RNS from Telit Communications (LON:TCM) on Friday (which does not show up for some reason on Stokopedia news feed). This stock I believe is on Paul's bargepole list. The company has agreed $110 million of new committed 3 and 5 year bank facilities from HSBC ($75 million) and Bank Hapolim ($35 million). The obvious question is why is a company that has been stating how its FCF is going to improve dramatically over the next few years need such facilities? The RNS's reasoning is generic: to fund acquisitions and organic growth. While there is no reference as to commitment fees or covenants, Telit states that if all lines were fully drawn, it would be paying 2.2% - as it already has a series of highly subsidised loans from the Italian Govt, this implies that that HSBC is prepared to lend to Telit for 3 to 5 years at probably a bit above 3%, which is surpringly cheap to me - and would appear to be a vote of confidence. (I am currently long as a punt.)
What I noted about the Elegant Hotels (LON:EHG) trading statement was that the word 'Zika' did not appear once. It can't be ignored. Even without any currency concerns, health factors will be a determining factor in where they go for a fair proportion of people, especially if they have read this:
http://www.bbc.co.uk/news/health-37290700
Paul....Yes Zeus is a definite Red Flag for me...Not Honorable people..just after their own self interest.
With regards Elegant Hotels (LON:EHG) I spent 2 weeks on the west coast of Barbados this summer - lucky old me - and I know that part of the island very well having been there 25+ times in the last 30 years.
The TripAdvisor reviews are a pretty decent reflection of the companies estate. Tired in places but very smart in others. After a difficult 5 years or so, the west coast has really come back to life. A fair few mothballed hotels are now being completed and there are (lots) more being built. Things "feel" buoyant.
Paul's comment about whether people will actually be that bothered by the exchange rate at the top end are true. My folks are going to The Waves in February (I think) - they checked it out when we were there this summer and loved it - the exchange rate, whilst annoying, isn't the difference between them going or not going or booking Waves or somewhere cheaper. They just accept the fact that it's a bit more expensive. Lucky old them!
That won't be the case for some of the less pricey places though where I feel that at current exchange rate, there will be a tailing off of bookings and given the new hotel capacity come on stream and the need to fill those hotels up, I suspect there might be something of a price war at lower-mid levels in the next 18 - 24 months. Outside of the accommodation costs, Barbados is not a cheap island. I was surprised this summer at how expensive it has become, even in $US terms, let alone Global Petroleum (LON:GBP).
Like Paul and others, I think there's some wobbliness ahead for EHG but will keep a close eye as at some point it may well be a cracking investment. If only they'd implement a scheme whereby shareholders get a discount.....
JDW72
I have been a visitor to Barbados over the years, and it has a big British following. The island has an Atlantic Ocean side, which is wilder than the Carribean Sea side. The Carribean sea is the most popular and most populated, as you might expect.
Barbados has grown pretty expensive, and has a number of well known restaurants which have increased their prices to London style pricing, particularly the more upmarket ones.
The Colony Club is a favourite one of mine, though its been some years since I have been there. I cannot recall ever having a problem with mosquitos out there, though I know of one family group of my acquaintance who were due to visit with a pregnant member who cancelled on hearing the news. Why risk it?
I think the people who go there are well-heeled, and Christmas is peak booking time. If its poor this year then there is a problem.
.
Just another point to make on Elegant Hotels (LON:EHG) - I have been trawling through the TripAdvisor ratings for their hotels. I fully understand that reviews can be unreliable, in that some customers are unreasonable, or outliers - maybe they had something go wrong which was a one-off. However, one can adjust for this, when reading review sites, and get a general impression that is usually broadly correct I think.
This is my general impression of the TripAdvisor reviews of EHG's properties;
Crystal Cove - reviews generally good, but a regular mention was dated decor, and slow service.
Tamarind - generally good again, but some not happy - suggesting to me that there are some issues here.
Turtle Beach - Mostly good again, but decor needs updating was a point of feedback.
The House - most expensive (by far) of EHG's hotels. Excellent reviews. So if people are paying top whack, and are notoriously fussy, to post such great reviews, it must be terrific.
Waves Hotel & Spa - 5/5, but only 3 reviews. Recent refurb seems to have been well received.
Colony Club - excellent reviews.
So a recurring theme for some of Elegant Hotel's sites seems to be a requirement for upgrading facilities. Poor showers, tired decor, ineffective aircon, were mentioned by a few visitors.
Also, opinion seemed to be polarised about food - some positive, others quite negative.
Poor & slow service seemed to be mentioned by some people too. Although many more people mentioned charming & courteous staff, so who knows?
My overall impression from the reviews is that 3 of Elegant's Hotels (Crystal Cove, Tamarind, and Turtle Beach) sound like they need a refurb, in order to continue charging way more than other places in Barbados.
So quite a bit of capex needed, by the sounds of it.
Although I'm also reassured by how positive most reviews were. A hotel should delight its customers enough to ensure that most feel motivated to post good reviews.
What do other people think about the reviews for Elegant's hotels? Also, have any readers actually stayed in their hotels? If so, do please post a comment here.
Regards, Paul.
Hi Paul
I'm a regular visitor to Barbados and was considering an investment but thought there properties were in the main tired.
There was a thread here;
http://www.stockopedia.com/content/elegantly-lying-under-the-hot-barbados-sun-with-upside-149958/
I can see the obvious yield attraction but am sitting this one out for now as the freehold property assets are only normally valued on the return they generate so any downturn will impact the value as no alternate use is plausible so the comfort of a reasonable LTV is illusory
Have stayed at Crystal Cove many years ago. Generally a good experience but service at the watersports was poor - so laid back not very many guests got to do the water skiing - probably an unintended consequence of being all inclusive (no incentive to get more customers for the watersports). Dine around option with sister hotels was harder than it should have been to arrange. But I must emphasise that this was a very long time ago, so all could have changed now.
The thing I would be concerned about to some extent now is how badly have they been affected by the recent hurricane, which I think was the worst in 10 years.
Hurricane hArdly touched barbados thank god
I've been working on Elegant Hotels at the moment as well. If you have not already read it Hardman & Co has a good note here on the share which has some interesting information in it . The resilience argument is worth investigating.
Although an overseas AIM company needs extra due diligence I'm not as worried about EH as usual. The company was listed in the UK (as St James Beach Hotels in the 90's on the main market) before being bought by Credit Suisse and then by Vision Capital (with Goldman Sachs as the lead investor). Furthermore, the best options for listing were London or America. You can see trading reports for the BSE here. The liquidity is awful and EH would have been around 2% of the entire exchange capitalisation. Listing EH in London is not as unreasonable as listing a Greek or Chinese company here.
Although I'm pretty sure the company is trading below its intrinsic value; the risk of a profit warning is very clearly there. It's a tough one...
Hi Connor,
Sensible comments, thanks.
I agree with you, that whilst I am very wary of all overseas companies listing on AIM, I think Elegant Hotels (LON:EHG) is one that I would make an exception for, due to the follow factors;
So I think it's a share that is worth adding to my watch list, but not one that I'm going to buy just yet, as I suspect more bad news is likely.
Regards, Paul.
Unilever, P&G, Kelloggs and no doubt others seem to have created very successful trading models based on mega-blitz advertising and hoisting prices to give huge margins. Also they have largely managed so far to stifle discount brand competitors such as McBride which I held for a while. Why would supermarkets stock 'own label' products when their thin margins are far outweighed by those allowed them by the industry giants? Tesco have won this spat, but IMO the real war is being fought by Lidl and Aldi where shoppers are voting with their feet and wallets to avoid the high price suppliers in favour of their similar if not better substitutes. .
Replying to Rhomboid1 - (LON:CRL) - Thank you,
Yes I, believe they can go a long way.. The Mello Investor Presentation dated November 2015 first brought the company to my attention and I have retained a holding since then. They certainly are very illiquid - just three trades on Friday.
The Rankings are good and the Stockopedia comparison with Swallowfield (LON:SWL) highlights Creightons stregnths.
The Board of Byotrol plc ('Byotrol' or 'the Company'), the specialist anti-microbial technology company, announces that it has granted a total of 5,400,000 options over the Company's ordinary shares of 0.25 pence each ("Options" and "Ordinary Shares" respectively) representing 2.01 per cent of the issued share capital of the Company to two Directors and certain employees of the Company, upon the recommendation of the Company's Remuneration Committee. Details of the awards to the two Directors and the Company's Head of Finance, Denise Keenan (PDMR) are set out below:
Should they not have some targets before they get these??
CRL - What has happened to Creightons? Price has fallen 10% in two days. Is it just profit taking or is there some deeper reason?
Seems like a buying opportunity to me.
Michael.
I'm sure you know this but Creightons (LON:CRL) is tiny & thinly traded , as a result it is volatile in the extreme , I have a stake and am holding it close as they could be a very much larger entity in the years to come , if they run out of growth opportunities I'm expecting FCF to give generousl dividends.
I'm a holder of CRL and following it with interest. I'm not sure the reason for the recent pullback but note it's on low volume so it looks like profit taking to me. That said, I haven't been able to find any information for the reason for the fairly rapid rise from ~10p to 15.5p. I noticed lots of 100k shares being bought daily during that run up. One to keep an eye on imo.
Elegant Hotels (LON:EHG) That trading update aka as a profit warning is, in my opinion, merely the start of a series of forthcoming profit warnings. I used to own shares in EHG shortly after they listed and then sold the moment that they started to buy more property (Wave hotel) back in February.
The negatives that I see is not only the Zika virus but also currency risks. Furthermore the company is dead set on increasing debt to finance new property purchases with questionable pay-back periods, adding a lot of intangibles to the balance sheet and providing property valuations which are somewhat questionable given that the universe of buyers for a property like that in a location like that is small. The property prices are only as good as the hotel related revenue it can generate. Therefore i do not believe the tangible assets are of good quality.
The company was brought to market by Venture Capitalist who, if I recall correctly, have a 20% shareholding which is locked in for a certain period (end of this year?) so they will also, presumably, be wanting to dump their holding.
Overall though I'm just very suspicious of management and their quick land grab post IPO which I see putting the whole business at risk.
The dividend is ridiculously high given the share price and will almost certainly be uncovered next year; so expect a dividend cut and at some point a placing in the next 6-18 months.
But even a pile of poo is worth something but would want to wait for another 3-6 months to see how bad those future profit warnings are going to be. The upside will also be limited by the venture capitalists selling out. As things sit, I might be a buyer around 30-35p but otherwise continue to watch the story unravel... sorry I mean unfold...
Carcosa
I wouldn't touch them while the Zika virus remains a concern. Who would buy the hotels from them at the minute?
I laughed when I read Simon Thompson's last column on them. He said there had been some Zika cases on the island but none at EHG's top end properties. I guess the mosquitos know to stay away from four and five star guests.
Hi John,
Thanks for your comments on the Zika virus. I hadn't spotted that issue, so have included it in the main article now.
Regards, Paul.
It's not actually as silly as it sounds - mosquitos tend to behave in clusters and control methods rely on this (I live within spitting distance of a Zika cluster in another country outside of Barbados but not actually in the cluster and it's amazing how little 'travel' there is with these things with effective management). So the fact that their hotels have no cases IS in fact a sensible and relevant point and suggests they have no active Zika clusters near them and/or that control methods are proving effective for those zones. That's not to say that they will never get any cases of ZIka in future of course as these things are not by any means foolproof/watertight (and if they did the effect on that hotel might be severe), but it's not the case that infected mosquitoes are flying around randomly everywhere on the island and that guests of these hotels are just somehow lucky (or privileged by their 5 star status as you say) - it's more a case that the locations of the hotels and/or the mosquito control around them is so far proving an effective safety net and infected mosquitoes are not active in those locations on the island.
That's not to say people won't be put off anyway just by the risk alone of course (headlines are a powerful thing, and how many people will actually bother to look into mosquito behaviour/control to see how safe it is... probably next to none ... and in any case why not just go on holiday somewhere else with no Zika?!). Also longer term who knows how bad the Zika problems will get on the island so from an investment perspective this all a bit irrelevant and provides little comfort that this won't harm the business. If you were planning a holiday there this year then the comments should give you a degree of comfort regarding Zika risk during your stay, but shareholders should remain very wary ...
I think the price they paid for waves was too high, bearing mind the money they have also spent on the renovation.
Property prices generally have dropped considerably in price since 2009 so owning freeholds is great but reduced in value ( as much as 50%)
Zika is really not affecting Barbados ( I live here), chickengunya and dengue has been much worse in previous years.
Regular fogging has to greater extent taken care of mosquito problem here for now.
Barbados is so reliant on tourist trade , I would be very wary !!!!
We moved here from uk in 2009 and the recession followed us over and that season was dreadful for everybody so who knows what the exchange rate will do to next years season which kicks off in December.
The government here have also just added 2% tax to all imports , as if things are not already expensive enough here.
Carabbean is a place to be very very cautious !!! You have been warned.
People are not going to stop eating Marmite, nor putting Comfort in their wash. Buying jewellery is a very different matter. Not only that, there is no attack on the taste or quality of the Unilever products.
When the Unilever chairman starts denigrating the taste and ingredients of Marmite, then you can compare the situation to the Ratner moment. Until then, it's just me and a few others who are repulsed by the ingredients and the taste of the brown gunk.
Scm
Agreed, Tesco have made themselves the people's champion against Unilever. However didn't Lewis come from Unilever? Maybe it didn't hurt them either. Lots of free publicity for marmite, Lidl were giving jars away at some stores, expect a bump in sales of the yucky stuff !
Hi Kenobi,
I agree on the positive PR for Tesco - UK housewives' champion and all that.
For Unilever, I'm not so sure. Although the adage of "no such thing as bad publicity" may apply, given the generally rabid anti-EU/pro Brexit press we have, I suspect Unilever will be painted as the opportunistic, profiteering "bad guy" in the piece. We're already seeing the "33 out of 40 Unilever products are actually manufactured in the UK" type articles and I suspect more of the same will follow. Could this be their Ratners moment that comes back to haunt them?
Gus
Hardly anyone knows what products Unilever make or will go to the bother of a boycott if they do. I would say Unilever are showing that they have the pricing power, not Tesco or the other retailers and therefore Unilever is the better investment. It's the opposite of a Ratner moment - he said his product was crap, Unilever are saying theirs deserves a premium price.
I would expect some switching to own-brand products though if they get too far ahead of themselves on price. We tend to happily buy the Costco private label (Kirkland) these days as opposed to the Unilever or P&G branded stuff.
Hi John,
My reference to a Ratners moment was not so much to draw a direct parallel with Ratner's comment (as I recall it was something about his jewellery being c**p and having the longevity of a prawn sandwich) as make the more general point that this spat with Tesco could end up being a major PR gaffe for Unilever that makes them a bete noire of choice with the British tabloid press. Looking to raise prices for their premium household products on the pretext that £ devaluation makes them more expensive (even though they are mostly manufactured in the UK) coupled with analysts pointing out that Unilevers' margins are already much wider than the supermarkets' makes them an easy target. It might be surprising how damaging to brand values a feud with the likes of the Daily Mail might turn out to be.
As it is, it may well be that Unilever have already put the genie back in the bottle by settling so quickly with Tesco (albeit on undisclosed terms) such that Marmitegate is already last week's news.
Best,
Gus.
Unilever products easy to track down..plenty of substitutes available from likes of proctor&Gamble, Reckitt & Benckiser - more so former I think...
Some things seemingly no subsitutes. eg Marmite. Jif?
Food and beverages:
Alsa, Amino, Amora, Annapurna, Aromat, Becel, Ben & Jerry's, Best Foods, Bertolli, Blue Band, Bovril, Breyers, Brooke Bond, Bru, Brummel & Brown, Buavita, Bushell's, Calvé, Chicken Tonight, Choysa, Colman's, Conimex, Continental, Country Crock, Darko, Delma, Du Darfst, Elmlea, Fanacoa, Flora, Fruco, Fudgsicle, Grom, Heartbrand, Hellmann's, I Can't Believe It's Not Butter, Imperial Margarine, Jif, Joko, Kasia, Kecap Bango, Kissan, Klondike, Knorr, Lady's Choice, Lan-Choo, Lao Cai, Lipton, Lipton Ice Tea, Lizano Sauce, Lyons, Maille, Maizena, Marmite, McCollins, Motions, Mrs. Filbert's, Paddle pop, Pfanni, PG Tips, Phase, Planta, Popsicle, Pot Noodle, Promise, Rama, Rani, Red Rose Tea, Robertsons, Royco, Saga, Sana, Sariwangi, Scottish Blend, Sealtest, Slotts, Stork, Streets, Sunce, T2, Telma, Tortex, Tulipan, Turun sinappi, Unilever Food Solutions, Unox, Vaqueiro
Home and personal care:
All, Ala, Andrelon, Aviance Cosmetics, Axe, Ayush, Baba, Badedas, Biotex, Block & White, Breeze, Brilhante, Brisk, Brylcreem, Caress, Cif, Citra, Clear, Clinic, Close-Up, Coccolino, Comfort, Cream Silk, Degree, DERO, Dimension, Dollar Shave Club, Domestos, Dove, Dove Spa, Dusch Das, Elidor, Eskinol, Fair & Lovely, FDS, Gessy, Glorix, Good Morning, Impulse, Ioma, Lakmé, Lever 2000, Lifebuoy, Linic, Lux, Lynx, Lysoform, Master, Matey, Minerva, Mist, Neutral, Noxzema, Omo, Origins, Organics, Pears Transparent Soap, Pepsodent, Persil, Pond's, Prodent, Quix, Q-Tips, Radox, Rexona, Rinso, Robijn, Sedal, Shield, Signal, Simple, Skip, SR, St Ives, Suave, Sun, Sunlight, Sunsilk, Sure deodorant, Surf, Swan Soap, Thermasilk, Tholl, TIGI, Timotei, Toni & Guy, TRESemmé, Ultrex, Vaseline, Vibrance, Vim, Vinólia, Viso, Wheel, White Beauty, Williams, VO5, Xedex, zendium, Zhonghua, Zwitsal
http://www.dailymail.co.uk/news/article-3835034/Major-brands-axed-Tesco-shelves-row-supplier-Unilever-demanded-10-cent-price-rise-falling-pound.html
I think Lewis had to make a stand to establish himself as a Tesco man and not be seen as a Unilever plant who rolled over when the price increases came through. I think it was more about his personal PR than anything else.