Small Cap Value Report (15 Apr 2015) - SDY, DIA, CTH

Good morning!
Speedy Hire (LON:SDY)
Share price: 73p
No. shares: 521.9m
Market Cap: £381.0m
Trading update - for the year ended 31 Mar 2015, this all looks solidly on track;
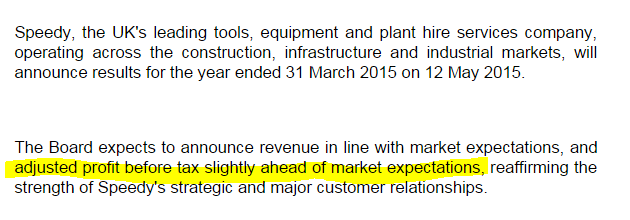
Various other details are given, including comments that the losses from their Middle East division have been stopped, with nearly all loss-making operations sold or closed down.
Valuation - based on current broker forecasts, the shares look very expensive to me (a PER of about 12 is the level that I would consider to be a sensible valuation);
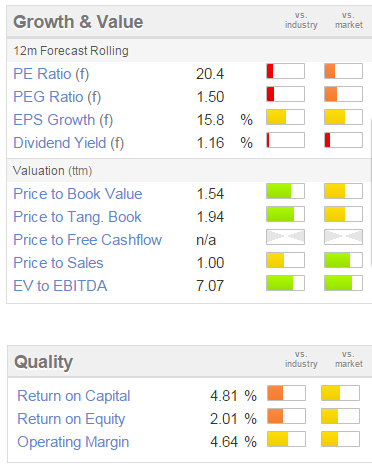
Of course broker forecasts are frequently wrong, so we shouldn't take them as gospel. However, to justify a PER of 20.4 for a business that has quite a bit of gearing, then you would have to assume quite a big out-performance against forecast is on the cards.
Maybe the turnaround measures have not yet been factored into broker forecasts? Although with a £381m market cap, one imagines the brokers have taken some time to make the numbers realistic.
My opinion - it looks over-priced to me. The dividend yield is lousy, at just over 1%, and a price to tangible book of nearly 2 also seems quite a stretch for an equipment hire business.
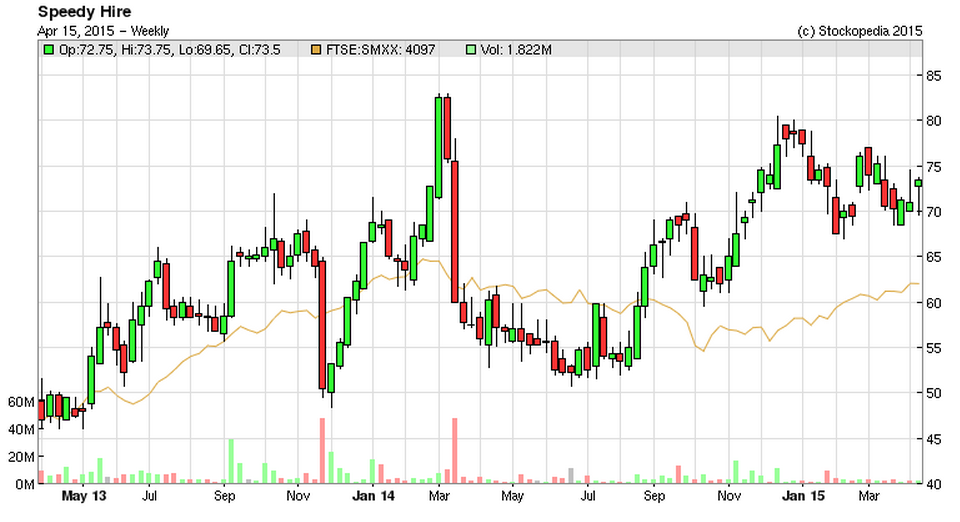
Note from the two year chart below the profit warning just over a year ago:
Dialight (LON:DIA)
Share price: 759p (down 3% today)
No. shares: 32.5m
Market Cap: £246.7m
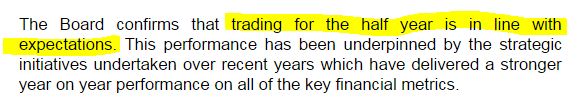
Trading update - for Q1 of the calendar year to date. The update begins positively on trading for Q1;
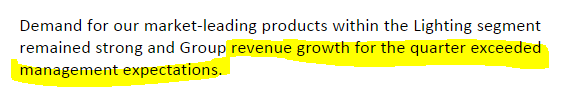
However, it then goes on to introduce significant doubts on a number of fronts. Firstly, it sounds as if production is inefficient;
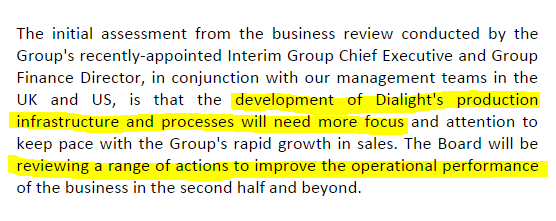
Comments of this nature usually mean site closures, redundancies, etc. So probably some restructuring provisions are in the pipeline. However, from a shareholder point of view, improving profitability is a good thing, providing the short term cash costs are not too onerous. There is also disruption to the business to take into account - restructuring doesn't always go smoothly.
Net debt at 31 Mar 2015 is reported at £8.9m, That's quite a bit worse than the net cash of £0.6m reported at 31 Dec 2014. Although the balance sheet overall is absolutely fine, no issues there, other than a small pension deficit.
H2 weighting - this is somewhat perplexing. If trading in Q1 has been good, why are they expecting the year to be H2-weighted? This suggests to me that current trading in Q2 must be poor. It's difficult to see any other explanation. So this could be a deferred profit warning, which is often the case when management say they are expecting a strong H2 bias to trading;
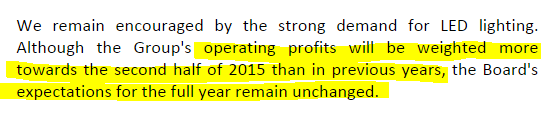
My opinion - I don't currently hold this share, but there are enough uncertainties and possible problems ahead flagged in today's update, that I would have probably sold first thing this morning. A forward PER of 17.1 doesn't allow any room for anything to go wrong.
Caretech Holdings (LON:CTH)
Share price: 242p
No. shares: 62.0m
Market Cap: £150.0m
Trading update - for the half year to 31 Mar 2015. This is my first review of Caretech in these reports. It provides out-sourced social care (e.g. facilities for disabled people, etc) for local authorities.
The key part of today's statement says;
Mention is made of a successful Placing of 10m shares at 210p in Feb 2015.
Dividends - the yield is about 3.5%, and has been growing at an average of about 11% p.a. in recent years.
My opinion - I narrowly averted a disaster a few years ago, when I realised late in the day that Southern Cross Healthcare was going to go bust, so I sold their shares in the nick of time. Southern Cross was a care home operator (for the elderly), so pretty similar to what Caretech does, in terms of business model.
What killed off Southern Cross was leases with automatic annual rent increases (of c.2.5% from memory), colliding with local authorities under severe cash pressure, flatly refusing to agree to increases in charges. Also, occupancy levels are key in this sector, since so many premises & staffing-related costs are fixed. If occupancy falls below a critical point, then profits vanish.
Looking at Caretech's figures, my main worry is that it is too profitable. Sooner or later the local authorities might catch on to this, and refuse any fee increases, or even demand fee reductions.
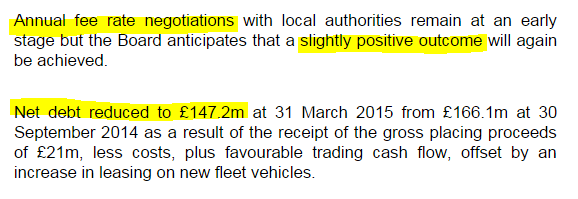
On the positive side, Caretech seems to have a substantial freehold property portfolio. Therefore it won't be subjected to rental increases on the freehold properties, since they are owned rather than rented. There is a lot of debt though, so unless hedging arrangements are in place, then it would be vulnerable to interest rate rises.
Overall, there's no denying this stock looks superficially cheap (on a PER basis). However, having had one very close shave in this sector before, I'm wary of going near it again. Social care budgets are being slashed by many councils, although on the other hand Govt policy of giving individual budgets to families, so they can choose their own care provisions, might work to Caretech's advantage possibly?
It's a bit of a minefield this sector, so careful research is definitely needed. You can never be sure that today's profits will continue in the future, due to changes in Govt & local authority policy & budgets.
I'll do a bit more this evening, but for now I have to return from London to Hove, and catch a few rays! Regards, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

9 comments
Paul,
Tracsis Interims out today and on the face of it results look reasonable with positive developments in USA, etc. and a solid balance sheet (despite significant intangibles relating to acquisitions as you have previously noted). Any thoughts on share price fall of c. 6% - profit taking after a good run perhaps or view that valuation is getting a bit rich?
Hello ACounsell
I hold Tracsis. They fell because the results failed to meet very high expectations. The forecast EPS for the year to end July 2015 was an increase of 34%. (That forecast will now fall) The results for the first half of that financial year were a very respectable increase in EPS of 19%. But the market was expecting better, so the shares fell. I think that they would have fallen further, but the update on progress in USA looks quite promising.
Paul,
standing your Caretech concerns do you think there is a "read across" risk in the context of PHP and AGR?
Hi Paul,
One of my pet hates is companies that grow the dividend at double digit rates, and then do placings and rights issues. This is not restricted to small cap, Standard Chartered was famous for paying out lots of dividends, then every 18 months coming back to investors and asking for more money "to fund growth".
Either a business is profitable enough to be self financing, in which case it pays dividends at a sustainable level. OR the business needs more capital to fund growth, in which case it shouldn't be growing the dividend at double digit growth rates. Hence I too will be avoiding Caretech.
Among the other updates today there is one from Private and Commercial Finance (LON:PCF) that seems to suggest good progress, and the market seems to agree this morning. I was interested this company after seeing them present at a ShareSoc meeting and was pleased that they had survived (and appeared to have learnt from) the financial recession.
With cheaper funding from their expected banking licence, solid growth in their main business and lower loss provisions they would appear to have good support for a P/E still under 10
Paul, if you have looked at it, II would be interested to know your thoughts on it, as a holder I may not be giving proper weight to the downside case.
I believe there is a trading update from Lavendon tomorrow -so you may well be vindicated. I agree with most of what you have written (-though a bit off topic). Certainly a good way to play mainland Europe.
Hi Paul,
It's interesting that similar companies can have such big differences in their respective valuations. I agree with you that Speedy Hire (LON:SDY) look overvalued compared to their peers such as Lavendon (LON:LVD), which is a company I rate highly (and hold). Their current PE is just 9.5 and brokers have been upgrading their forecasts recently. The share price has come down somewhat having hit £2.46 in March 2014 and it now trading at £1.70. It has a stockrank of 82 and is aligned to a recovery in Europe (Revenue in France £23m, Belgium £13m, Germany £41m) and maybe a good way to access European QE? £50m of its revenue comes from the middle east and £120m from the UK. The CEO, Donald Kenny bought just short of £180k worth of shares in March. Although i'm not a chartist, the price does seem to have found support at around the current price and will hopefully start to form a bowl...
Cheers,
Ben
Paul, its interesting reading your SCVR compared to twitter posts. All i saw on my feed was DIA beating expectations and no one mentioning the points you raise. Good job!
Hi Metier9,
Well, quite. In my experience 99% of people use Twitter & bulletin boards simply to ramp their own personal positions. So they only ever mention selectively points which support the bull case, and are mysteriously silent on bearish points! You hardly ever see intelligent/balanced views. There again, I suppose with Twitter there is the 140 character restriction, which limits points made to being very brief.
I just treat bulletin boards as being primarily for entertainment and amusement, but you do pick up the occasional useful snippet of info.
Regards, Paul.