Small Cap Value Report (15 Dec 2015) - UTW, TSTL, CFHL, PRES

Good morning!
A fairly short report today, as I've just had news that Mum is coming out of hospital this afternoon, so I've got lots of tidying up to do at her flat, to make it nice for her return.
Utilitywise (LON:UTW)
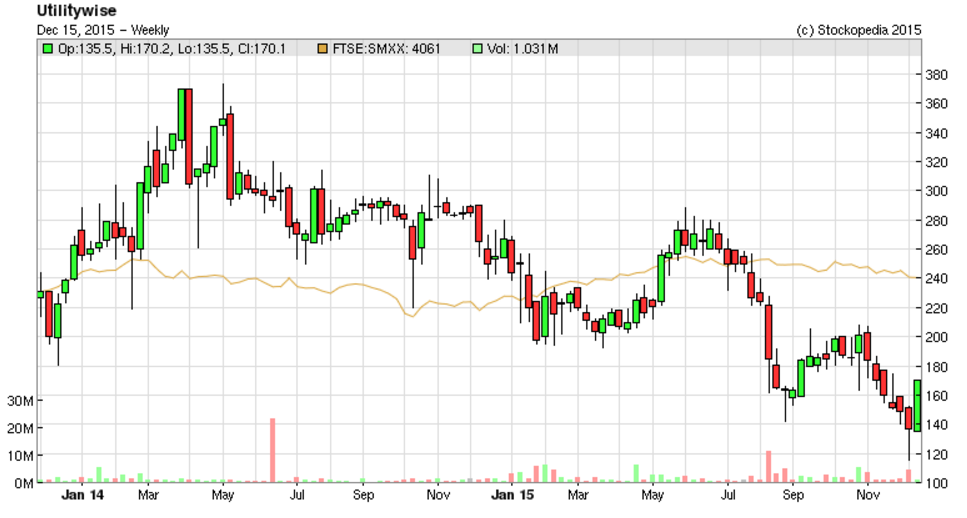
Share price: 168p (up 20% today)
No. shares: 77.2m
Market cap: £129.7m
AGM statement - the market really can't decide whether the glass is half full, or half empty with this share. Nor can I actually, as my last comments on the company were that the bull and bear case both seemed equally valid to me, hence the logical thing to do was sell up at 195p, and sit on the sidelines.
Today's update sounds reassuring, saying;
We are pleased to announce that the Group has made a solid start to the year, with trading during the period in line with expectations. The pace of recruitment is picking up and we anticipate our position continuing to improve, as per previous market guidance, as the year progresses.
Customer numbers as at 30 November 2015 were 28,507 and our secured future pipeline was £27.7m at the same date.
Broker consensus is for 19.3p EPS this year (ending 31 Jul 2016), so even after today's 20% rise to 168p, the PER is only 8.7, which looks good value. However, it's cashflow that is the big issue with this company. As has been discussed many times before, the company's aggressive accounting treatment means that it books profits often a long time before the cash comes in.
On 27 Oct 2015 the company announced that it had significantly improved cashflow, by renegotiating payment terms with one large utilities supplier. Today, another announcement says this has been extended to a second supplier. More are likely to follow, which should be a good catalyst for the shares to recover further, perhaps?
My opinion - the shares would have made a cracking buy when they recently plunged to about 120p. I was really tempted, but unfortunately didn't have the conviction to buy, as you always worry that a precipitous fall like that is because insiders are bailing out ahead of a profit warning.
To my mind, there are just too many uncertainties around the accounts for this company, and I'm not really keen on the business model of hard selling via call centres, and the obvious conflict of interest between recommending what's best for the customer or taking the highest commission on offer. So having considered it for a while, I've decided not to revisit this share - there are too many question marks.
Tristel (LON:TSTL)
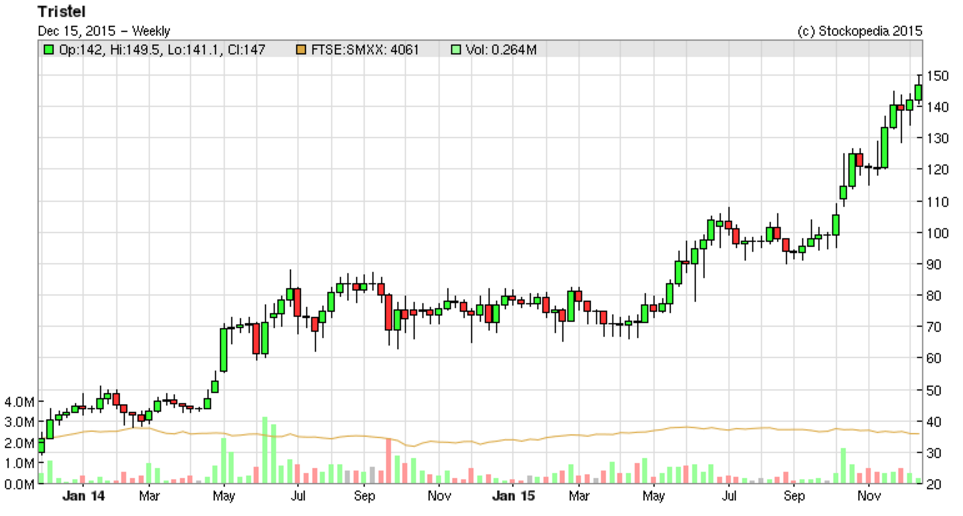
Share price: 146p (up 0.3% today)
No. shares: 42.1m
Market cap: £61.5m
AGM Statement - the company gives a nice clear explanation of what it does, being a;
manufacturer of infection prevention, contamination control and hygiene products
There is also an in line with market expectations update on trading, which again is useful in that it gives specific figures too;
"This is the sixth consecutive reporting period in which we will have achieved year-on-year profit growth.
We expect unaudited pre-tax profit for the first half to be no less than £1.4 million, compared to a pre-tax profit of £1.1 million for the same period last year - an increase of at least 27%. The full year profit for the year ended 30 June 2015 was £2.6 million. The Board believes that performance continues to be in line with market expectations.
Valuation - the shares have had an excellent year, rising strongly. The shares are barely changed today, despite a positive-sounding update, which tells me that the market has probably now priced-in all the good news for the time being.
Consensus forecast is 5.43p EPS for this year, so at 146p the shares are on a racy current year PER of 26.9. That strikes me as a fairly rich rating for a company that is delivering good, but not exceptional growth.
Outlook - the Directorspeak today refers to overseas growth opportunities, which is probably why investors seem happy to take the rating up to a much higher level than it had previously been on;
Growth is coming from all areas of the business and we are particularly pleased with our progress in China and Hong Kong.
We are satisfied with the progress that is being made on our United States regulatory approval programme."
My opinion - I like the company, but not at the current valuation, it's at least fully priced now, possibly a bit over-priced, in my view, so this looks like quite a good point to bank some profits, in my opinion.
CityFibre Infrastructure Holdings (LON:CFHL)
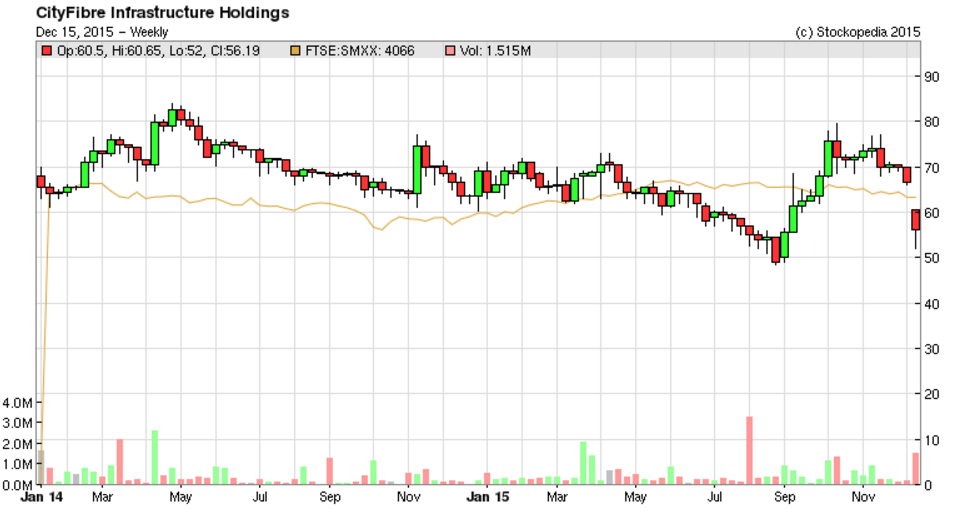
Share price: 56.5p (down 2.6% today)
No. shares: 105.7m
Market cap: £59.7m
Acquisition & Placing - I was wondering why this share started falling sharply. Now we know why - a large discounted Placing has been announced today, at 50p. Existing private shareholders must be furious, as 160m new shares are being issued - considerably more than doubling the number of shares in issue, but instead of offering them to existing shareholders (which is what's meant to happen, with pre-emption rights being a key principle of company law), the whole lot have been placed with institutions, at a discount.
It's such a large issue of shares that the market price will probably gravitate towards the placing price, so private investors who bought in the market at 70-80p with no knowledge of the fact that a massive discounted placing was being negotiated at 50p, have been absolutely shafted, and are now nursing a hefty loss, and to add insult to injury are not being allowed to participate in the 50p fundraising - there is no Open Offer element included, which is awful in my view. Very bad form.
Clearly news of the placing had leaked out, because the share price fell before this announcement was made. It's a totally unsatisfactory situation, where shares remain trading, despite probably hundreds, maybe even thousands of people knowing about price-sensitive information, and some of them probably broke the law, and engaged in insider dealing.
I feel a better system is needed, with a faster system for raising funds, and share should be suspended once that process begins, because the current system is terrible. You can't help feeling that private investors are seen by the City as cannon fodder, to get share prices up, ahead of discounted placings for the institutions.
There really should be an Open Offer added on to most Placings, to allow existing holders to participate on the same terms as new investors. I appreciate that the outcome of Open Offers is uncertain, and they can flop, but in this case the Placing was underwritten, so there's no reason at all why an underwritten Open Offer could not have formed part of this deal.
Anyway, the deal itself looks quite interesting. CityFibre is buying (for £90m) fibre-optic networks currently owned by KCOM (LON:KCOM) . This greatly increases the number of UK cities that CityFibre serves, and it says that buying existing assets in this was is c.45% cheaper than building them from scratch. Also it saves time.
So a transformational deal for the company, at the expense of its private shareholders, who have been excluded from the deal, and seen their investment sharply sell off as a result. Hopefully they will get their money back in the long run.
I think this is a good example of why capital-intensive, early stage companies are really not worth bothering with. The original investors will usually be diluted so badly by repeated Placings, that it's almost impossible to make a profit from the shares if you invest at the start. Better to wait for the company to disappoint, get the discounted placings out of the way, achieve scale, and then take a look, once it's clear how the business model is likely to pan out in reality.
Pressure Technologies (LON:PRES)
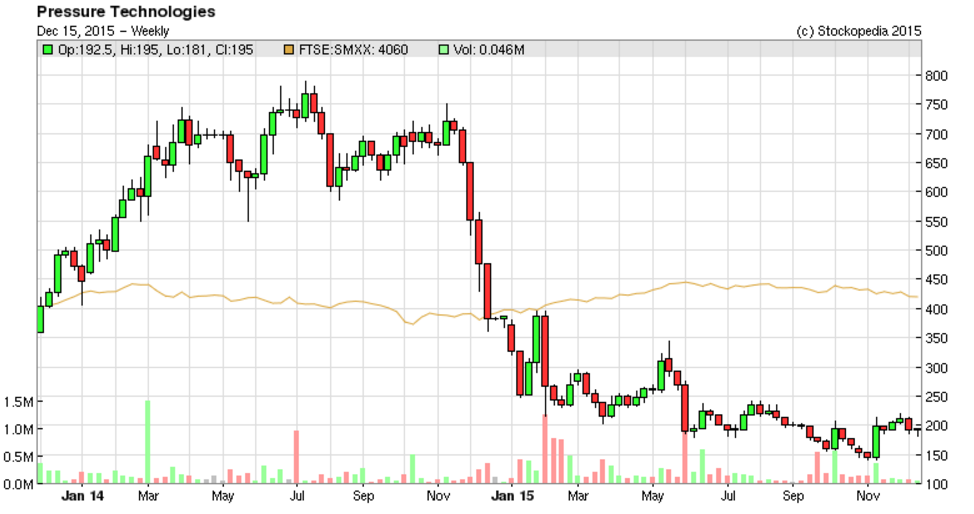
Share price: 192.5p (up 6.4% today)
No. shares: 14.4m
Market cap: £27.7m
Results, 53 wks to 3 Oct 2015 - after a quick scan through these numbers, they look quite reasonable to me. Obviously profit is down heavily, as you would expect from a group with high exposure to the oil & gas industry, but the figures are not a disaster by any means.
I like the introductory statement at the start of the RNS, giving a neat summary;
Pressure Technologies (AIM: PRES), the specialist engineering group, announces its preliminary results for the 53 weeks to 3 October 2015, which are slightly ahead of expectations and show strong cash conversion as the full year benefits of acquisitions come through.
Outlook - the summary and outlook comments have interesting read-across for other resources stocks, and it still feels as if there's no particular rush to get involved in the sector;
This was a tough year for the Group due to the downturn in the oil and gas market. Substantial progress has been made in restructuring to meet the challenges of reduced revenues. With continued pressure on the oil price due to a combination of over-supply and weak demand the Board is of the opinion that any major recovery in that market will not occur before the end of the 2016 financial year. That said, we are structured to expand rapidly to meet increases in demand.
The Precision Machined Components Division and Engineered Products Division have short order to delivery lead times of between two and four months and are therefore expected to benefit very quickly from an upturn.
The Cylinder Division is expected to see a much slower return to revenues from oil and gas as it is reliant on the building of drillships and semi-submersible oil rigs for its larger orders. In the short-term these divisions continue to seek out new markets, products and services whilst at the same time focusing on cost reduction and efficiency savings.
The Alternative Energy Division has a strong pipeline of potential orders as the demand for renewable energy grows worldwide. Development of the division is important to the near-term growth of the Group and we have the resources to achieve this.
Whilst current trading conditions for the majority of our businesses remain challenging, the Group is much more diverse and better balanced than in the previous low in the oil and gas market. The Board remains confident in the medium to long-term prospects for the Group.
So rather mixed there. I don't know the company well enough to draw any firm conclusions from this.
Valuation - it's very difficult to value this company, as with most O+G related companies, as we don't really know if or when profits are likely to improve. Adjusted EPS crashed from 44.9p last year, to 14.5p this year. It's anybody's guess what EPS will be in the new year (ending 27 Sep 2016). Brokers currently forecast 16.0p, but forecasts must be largely guesswork, given sector conditions. So I wouldn't want to value the company based on current year forecasts.
You might like to take a long-term view, and assume that profits might eventually recover to former levels, adding in extra for acquisitions. On that basis, a case could be argued that the shares might turn out to be good value for people patient enough to hold for several years.
Balance sheet - net assets of £36.3m is dominated by intangibles - which have grown considerably, due to more acquisitions. So NTAV is only £7.8m.
I'm a little concerned about the group having net debt. Whilst it doesn't look excessive at £7.1m, there is also £2.5m of deferred consideration (for acquisitions) in current creditors, and a further £3.5m in long term creditors, which should really be viewed as additional debt.
There was only £791k of land & buildings shown in the 2014 Annual Report. That might have increased this year with further acquisitions, but it doesn't look as if there's much asset backing from freehold property unfortunately.
My concern is that, if there is a further downturn in profitability, then the company could find itself in difficulties, breaching bank covenants, etc. It might all be fine, but there are risks.
My opinion - at some point this share might make a nice punt, but who knows when?
Have conditions now bottomed out, or could the company experience a further downturn in trade?
On balance, I feel that there is inadequate financial strength on the balance sheet to make it worth taking a risk on it, at the moment anyway.
All done for today.
Regards, Paul.
(of the companies mentioned today, I have no long or short positions. A fund management company with which I am associated may hold positions in companies mentioned.
NB. These reports are my personal opinions only, and are categorically NOT advice or recommendations. The ethos of this site is DYOR!)
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

21 comments
19 January 2015
Pressure Technologies plc
Property Acquisition
Pressure Technologies plc (the "Company") is pleased to announce that it has completed the acquisition of the freehold land and buildings at Meadowhall Road, Sheffield (the "Property") where the Company's subsidiary, Chesterfield Special Cylinders has been operating since July 2005 and where Chesterfield Biogas is also based. The Company has paid £3,360,000 for the Property, inclusive of £160,000 stamp duty which is funded from the Company's exisiting debt facilities.
Thank you for your comments above Paul, and yes, I am fuming!
Around July 2014 I attended a presentation by CFHL at FinnCap and listened to Greg Mesch presenting the company. I came away with the impression that he had a good track record, a good business plan for the mid/long term. I also felt the project would be beneficial to the community at large. I did not expect quick gains but felt confident there would eventually be a decent return and invested. Embarasingly I also encouraged my wife to buy some.
Then this - PI's have some 25% of their holdings confiscated and given to the institutional holders, who, for the most-part already had what they want and simply tipped the stock into the market. The pre-announcement price action also suggested some cosy insiders did not suffer the same fate as me. My attitude to the company has changed 180 degrees, and not for the better. Mr Mesch, you should be ashamed of yourself - might I suggest you make a meaningful apology and take a one off reduction in your remuneration this year of the same percentage - 25%
I don't know how much the investments of PI's is valued by such companies (at least enough to spend an evening at Finncap it seems) but unless the rules are changed to prevent this daylight robbery there will be no more such investments for me.
Pity the regulators don't seem interested in such abused - what ARE they for? (but this is for another rant). As far as I can see the only forum taking up this kind of issue is ShareSoc, and I will look to them to find out what I can do to lobby for a change.
No comments on PRES so far! I am very suspicious about the comments made by the senior management this company, especiually the Chairman. I was very impressed by the presentation at Derby last November and for some time PRS was one of my more profitable shares. I should have been more sensitive though to the reference in the later financials made by the Chairman that the company could feel some slight effect from the reducing oil price on their predominant cylinder business. The collapse that followed is well documented. I think that the other comments that Paul has made relating to the effects of takeovers on the balance sheet, the debt etc are very telling. I believe that it will be some consierable time for the oil price to recover significantly and we could be talking about 2018 or beyond before this company rises from the ashes. In the meantime, I think there are a lot of people hanging on every slightly positive word mafde by the ingenuous - dare I say misleading = senior management and the share price has risen accordingly. I for one will not be tempted by this one for a very long time, if at all.
Paul
Good to hear your Mother is on the mend.
I share your scepticism regarding Utilitywise (UTW). Although the market has reacted positively to today's figures, questions remain, regarding the long term viability of the business model and the companies overly aggressive accounting policy.
There are hundreds of independent energy consultants (B2B) dedicated to achieving best forward prices dealing directly with suppliers. Utilitywise enjoys no USP and I can only see their margins being squeezed harder and harder as competition grows more severe.
This one could unravel quite quickly in my opinion.
Paul - I think you do UTW an injustice re "business model of hard selling via call centres". This is not about 'I can get you a lower p /kWh. When you consider the complexities of the electricity market... with spot prices changing quite dramatically intraday. There was an event only a few weeks where - if you had the right partner - the price per kW from the National Grid went up 10X for a few minutes and the spiked down again. Also 'hard' selling in B2B markets unlikely to be successful. Disclosure - I have no position in UTW but have some understanding of the electricity industry. .
Paul, all the best with your mother; parents are a worry!
I went to the Tristel AGM today and I really like this company, although I got in much later than I should have done, having tracked it for ages and done nothing until a few months ago. Very annoying. I actually topped up materially again today after the meeting, which is clearly a big punt on further growth. It is expensive, but it could have some way to go.
I liked the responses from the board (CEO in particular) and the new info (via the Equity Development broker note that I read whilst waiting for the AGM to start) that the company is looking hard at the domestic cleaning market. The development costs linked with expansion also seem quite low. The next couple of years should be interesting.
Fundraisings/false markets: Better ask Sydney. Trading halts on the ASX are no big deal and are used for fundraises and secondary placings http://www.claytonutz.com/publications/news/201103/09/the_known_unknowns_trading_halts_made_easier_by_asx.page
The City will resist the regular easy pickings of course.
It seems odd that pre-emption rights are enshrined in company law yet it is allowed for companies to disapply pre-emption rights if their shareholders so vote and even more odd that companies routinely have these votes and that they are invariably passed. Perhaps it is something to do with the fact that the institutional shareholders control most of the votes and that they and their private clients can get in on the discounted placings.
If a client participates in a placing they can short sell shares (at the current price) and take up placing shares (at the discounted price). If someone did such a thing they would not even need to be (or even become) a shareholder to drive down the price in advance of a placing and guarantee a profit.
Totally agree on the need to change the way placings are conducted. In my opinion it would be significantly better if a company suspended it shares when it is looking to do a placing. This would stop PIs buying in what is effectively a false market and would also ensure the share price is stabilised for the fund raising rather than being forced down by less scrupulous holders selling whilst being "inside" on the deal.
If you look at the deal done by Benchmark this week where the shares were suspended whilst the raise was done the discount was small
Re shares not moving on a positive update, it could be more a market-wide thing than stock specific news being priced in. It seems consistent to me with current market mood where anything with a profit warning gets completely crushed... It seems value stock pickers are outnumbered at the moment.
I have noticed a lot with good news, shares either drop or don't move, then later usually the next day or so the price picks up. It seems unless the news is unexpectedly good some investors sell. There also seems to be a lot of selling in the days leading up to the results coming out.
Piedro, on the ad*fn board is worth reading on TSTL. Ignore the Tintin's comments on the future and China - it all depends on how many chicken entrails are stirred.
apad
Regarding Tristel, according to one report this morning the opportunities in the US and China represent an equivalent of another 100p added to the share price. As a 3 to 5 year long term hold one could do a lot worse than this company IMO. I only wish I'd got in earlier - but very tempted to add on any dips in the future.
I also echo the sentiments of others - good news about your mum Paul. My mum went into hospital for an op last week, thankfully everything went okay and now she home again, but it does definitely put everything else into perspective.
I hope your Mum continues her recovery. Have a good Xmas Paul.
Norcros. I am coming to the view that the sacking of the Finance Minister could be a big issue. There was some confidence in him and he seemed to do his job well. It was recently uncovered that Zuma has been having an affair with a senior woman at South African Airways which is struggling and Nene's unwillingness to fund further investment did not go down well. I am always nervous of conspiracy theories but there does seem to be some substance here. Zuma has done some strange things and appears a real egotist, not dissimilar to Mugabe all those years ago. Does this spell disaster for Norcros - unlikely, but it will hang over their share price and I am wondering if there are better returns to be made elsewhere for the forseeable.
TSTL:
Has some interesting products in the pipeline and some very encouraging technical reports on the efficacy of its products - made a big thing of it being a french report because the french only take notice of their own research :-)
Doesn't negate your view of the current valuation, but it is on my 'increase' list.
apad
Hi apad,
Indeed, I think if you take a long term view with a share like Tristel (LON:TSTL) and believe that the growth justifies the high rating, then that's a perfectly valid stance to take. Often to get the really big multi-baggers, you have to ignore an over-valuation, as it can keep rising, and earnings then rise, and grow into the valuation. So I perfectly understand, and respect your point of view.
Regards, Paul.
Just lost my reply as internet went down.
Anyway I do hold Tristel (LON:TSTL), long. Only a small holding, I will probably hold and if it falls then top up. Further looks promising if they can expand into new markets such as USA and China.
apad,
I'm in the same boat. Tristel is already profitable, has good management, already pays a 2% dividend (if you discount the special dividend), and has great products with excellent future growth potential. It's a core long term holding for me and at the top of my "buy on weakness" list. It does look expensive but I've resisted top slicing.
And, all of course thanks to one of Paul's investor interviews which brought the company to my attention. I owe Paul and said interviewee a pint or several!
Cheers, Si
Hi Paul -
Re. Utilitywise (LON:UTW) One discipline which I am sticking to no matter what is:
trying to catch a falling knife + Aim share = a big no-no
I have looked back over the past nine months and reviewed the stocks where I was tempted. A rough calculation showed that so far I would have notched up over 20% net loss.
Regards, Ram
Hi Paul,
Most importantly, fingers crossed for your mum and her safe return home today.
One observation on the morality or otherwise of the Utilitywise (LON:UTW) business model. While I agree there is inevitably a conflict of interest between commission based agents and a broker's responsibility to their customer to secure the best deal, is it not the case that their role is to present a customer with an alternative to their current arrangement which they can either accept or reject.
Presumably, and perhaps on the naive assumption that these agents have a duty not to misrepresent the products they sell, any transaction that UTW agents offer a client will only be accepted if it is better than the cleints' current position. These deals might not be the best available option in a world of perfect information flow, but are presumably at least better than the customer's existing deal?
Like you I prevaricated on this share. I took a small position which I extended slightly on the recent lows. Still not entirely comfortable .....
Gus.
Great to hear Paul, get some nice flowers in.
Chris
Hope things go well with you Mum.