Small Cap Value Report (15 May 2015) - TRB, BRAM, RST, TYMN, ENTU, EPWN, IDEA, RBN

Good morning!
London Value Investor Conference
This is the Rolls Royce of investor conferences, and I've been fortunate enough to attend for the last two years, and will be there again this year, next week in fact, Wed 20 May. There are only 6 tickets left! We've been given a special discount code: STOCKOPEDIA-LVIC which will get you £120 off.
There are some terrific speakers, as always, including Jonathan Ruffer, Charles Brandes, Richard Oldfield, Simon Denison-Smith, David Shapiro, and the last session is Q&A with Neil Woodford. The full schedule is here.
It's not cheap, but it's a real quality event in my view. I'll have my press hat on, so will be scribbling down some notes, and will publish a couple of articles here for talks which inspire me on the day. As it's a full day, that will mean unfortunately there won't be a SCVR here on Weds next week. Hopefully my reports from the LVIC will more than make up for that though.
Here is a link to my previous reports from the 2014 & 2013 LVIC, which are worth a recap. Jon Moulton's talk in particular was brilliant last year, and had a lot of relevance for those of us who like to meet management of companies in which we invest.
Anyway, on to what's happening today. It's quiet, so I'll circle back to a couple of announcements I overlooked yesterday from Ideagen (LON:IDEA) and Robinson (LON:RBN) at the end of today's report.
Tribal (LON:TRB)
Share price: 139p (down 8% today)
No. shares: 94.8m
Market Cap: £131.8m
AGM trading update - by the way, in case anyone doesn't realise this, the blue headers are clickable links to the relevant announcement. So if you right-click and select "open in new tab", then you can refer to the source document on investegate.co.uk .
Clearly this has been perceived as a mild profit warning, as the shares are down 8%, so let's have a rummage. Tribal is a "leading provider of software and services for education management" - a nice clear description of their activities in today's announcement.
Doesn't sound too bad at all;
So of course that actually means the outlook is slightly below. I guarantee to buy shares in the first company which uses the phrase "slightly below" instead of "broadly in line", as I think that would demonstrate refreshing clarity and openness.
Additional detail is given on divisional outlook, none of which seems significant. The word "stable" is used twice, which sounds reassuring, if unexciting.
Net debt - has risen to £25.7m at 30 Apr 2015 (prior year £13.4m) reflecting deferred consideration payments for an acquisition. "Seasonal working capital movements" is also given as a reason why debt is higher this year than the same point last year - how does that work then? Surely seasonal movements are eliminated when you compare the same date one year with the prior year?
Outlook - the dreaded 2nd half weighting comment appears, but this is tricky to interpret, as if that is the natural seasonality of the business, then it may not be anything to worry about;
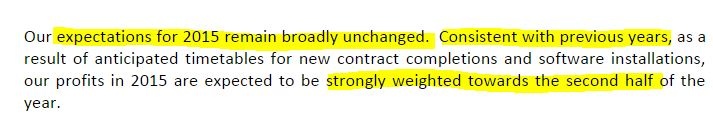
My opinion - looking back at last year's results, H1 produced an adj operating profit of £5.6m, and the full year was £14.5m, therefore H2 was £8.9m profit. Fair enough, that was a 39%:61% split of profits H1:H2, so there does seem merit in what the company says above.
However, it does introduce a degree of doubt.One broker has already reduced their profit forecast by 8% for both 2015 and 2016 this morning, on a precautionary basis, which seems sensible to me. Nobody likes H2-weighting being flagged, especially when combined with only "broadly in line" performance. That's code for - we're probably going to have to warn on profits again later this year, but we're not sure yet.
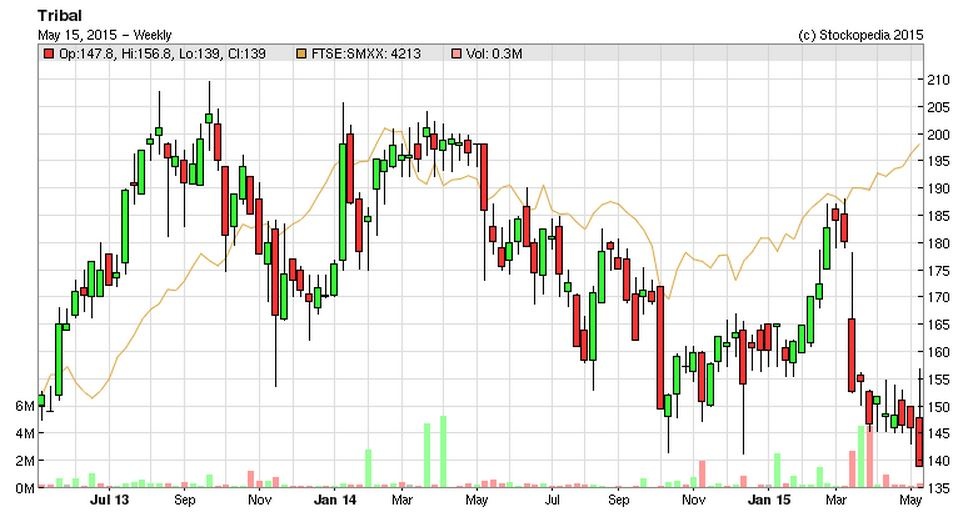
The shares have hit a new 12-month low this morning, but the valuation on a fwd PER basis is starting to look potentially attractive, at 10.3, as the 8% share price fall today offsets the forecast reduction of 8%.
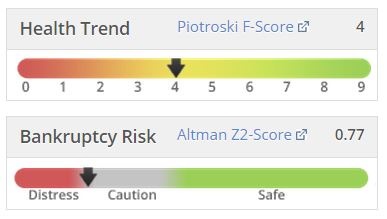 Set against that, the Balance Sheet is thin, and net debt creeping up to levels that are getting near the top end of reasonable, in my opinion.
Note that the Piotroski F-Score and the Altman Z-score are both flagging potential issues. I would never make any decisions solely based on these indicators, but they are worth glancing at, as they are telling me to dig a bit deeper in this case.
Overall - this is not the first time that Tribal has put out a hesitant trading statement, so I'm wary of getting involved here. If it had a bulletproof balance sheet with pots of net cash, then I'd be happier about having a punt on it, but with a weak balance sheet, personally I'm inclined to steer clear and wait to see what the interims look like when they are published in mid-August.
Small caps are generally so expensive at the moment that it's difficult to find many shares at a reasonable price, unless you take the plunge after a minor setback. That then opens up the risk that a minor setback is the thin end of the wedge for more serious problems.
Brammer (LON:BRAM)
Share price: 354p (down 12% today)
No. shares: 129.4m
Market Cap: £458.1m
I've decided to start reporting on some companies between £250-500m market cap, which I've previously ignored, and drop off some of the tiniest, most illiquid & speculative companies right at the bottom end - as I think this will be more useful to readers. After all, what's the point in being briefed about tiny companies that are too illiquid to buy or sell?
As I'm looking at these companies for the first time, please bear with me, and treat my comments as just a very quick scan, not in depth research.
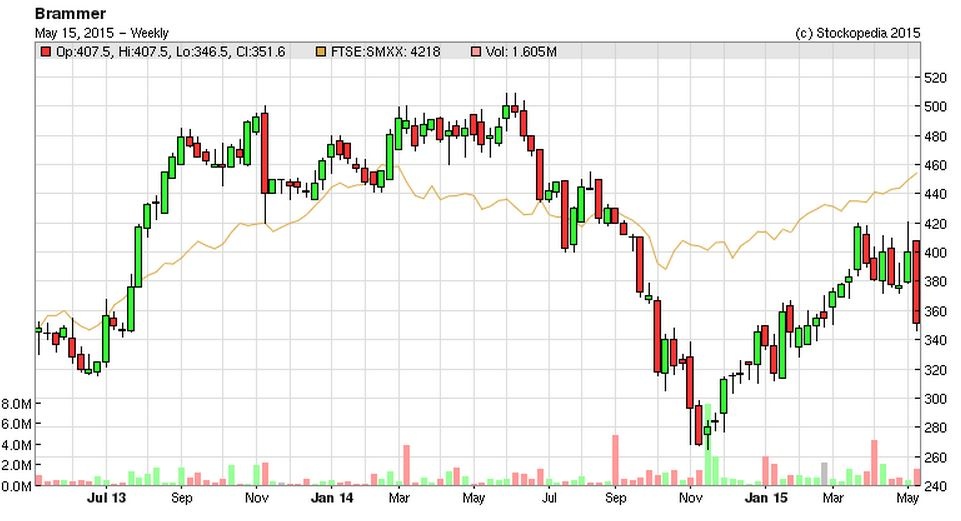
AGM trading update - shares in this "pan-European added value distributor of industrial maintenance, repair & overhaul products" have dropped 12% today, so it must be a profit warning. This has broken the previously strong up-trend since Nov 2014.
Today's update covers the first four months of this calendar year. There's lots of detail, but the key points seem to be these;
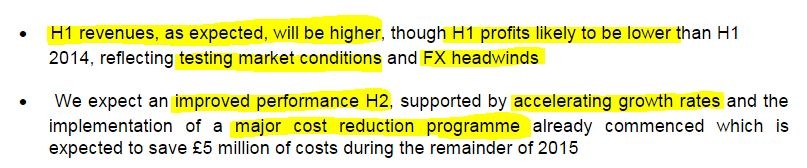
A new E120m debt facility has been agreed, but that was already announced on 30 Apr 2015.
Reading through the detail, the currency impact has been significant - and is helpfully quantified - each 1% movement in the Euro affects profit by £0.3m. Reduced demand from the oil & gas sector, especially in Nordic countries, is also mentioned as a factor for the weaker profits in H1 this year.
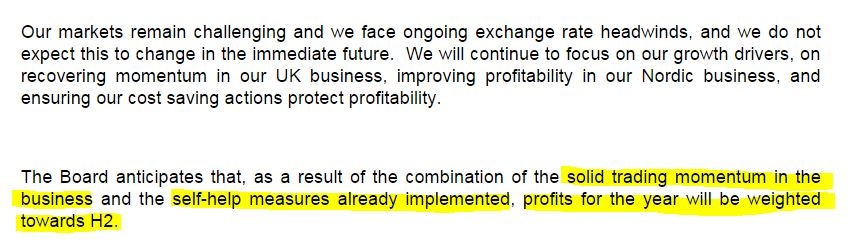
Outlook - this is a cop-out! They don't mention market expectations at all, unless I've missed it somewhere else in the announcement;
Valuation - the shares don't exactly look a bargain, given that they're facing various headwinds. But I suppose it all depends on what you think the future holds? Currency movements are swings & roundabouts in the long run, and European economies are maybe now recovering at long last?
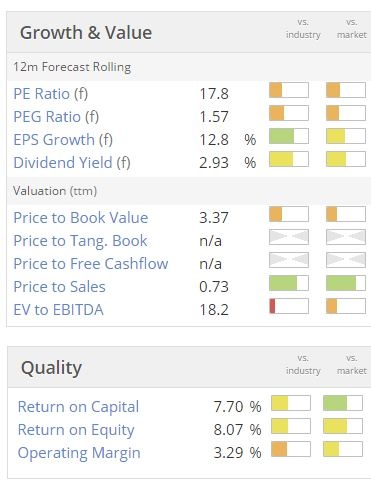
Balance Sheet - isn't great. Net assets of £155.7m reduce down to only £37.2 once you remove goodwill, and taking out other intangibles turns it slightly negative for NTAV, at -£2.8m. It's big enough & profitable enough for that arguably to not matter very much, but it needs to be factored into the valuation of the shares - i.e. I would want a lower PER than 17.8 to reflect the relatively thin balance sheet.
Note that there's a pension deficit too, shown at £38.6m on the most recent balance sheet - not necessarily a deal breaker, but I'd want to dig into the detail to assess the risk.
Dividends - not bad - the yield is about 3%, but I like the history of 14.5% p.a. compound increases in the divis in recent years, although the growth rate has slowed to about 5% recently.
My opinion - I don't know anything about the company, or its prospects, so cannot give an informed view. All I can say is that from reviewing these figures, and the "challenging markets" it operates in, it's difficult to see any immediate upside from 354p per share.
Longer term, who knows? It could benefit from a European recovery, and exchange rates might move in its favour.
Restore (LON:RST)
Share price: 270p (down 1.5% today)
No. shares: 82.2m
Market Cap: £221.9m
AGM trading update - more detail is given, but the key sentence says this;
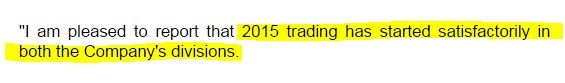
They are over a third of the way into the full year, so it's a bit more than "started"!
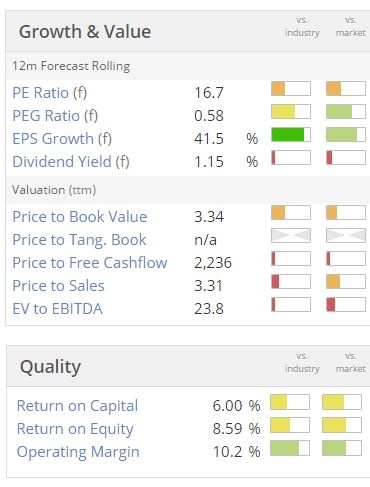
My opinion - this group is growing mainly by acquisition, and has issued a lot of new shares over the last few years - the share count was 9.33m in 2009, and has risen every year since, to 82.2m now.
Also, there's some debt involved - net debt was £30.9m when last reported, which is about 3 times pre-exceptional operating profit - which is getting a bit warm in my view.
I hear that management are very good, but it's difficult to see any reason to rush out to buy the shares at this valuation, which looks to me about right, or maybe a tad too high perhaps?
Tyman (LON:TYMN)
Share price: 306p (no change today)
No. shares: 169.6m
Market Cap: £519.0m
As part of my new push into small-mid caps, let's look at another one! I've never heard of Tyman before, but apparently it's a "leading international supplier of components to the door and window industry".
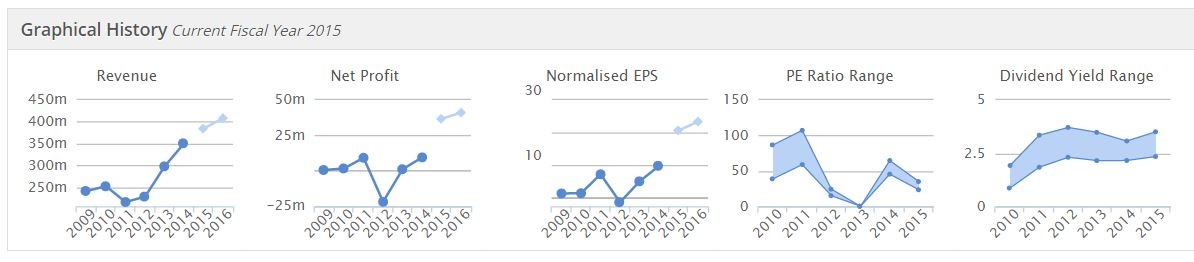
Looking at the historic performance graphs, the company doesn't seem to have made much profit between 2009 and 2014, but analyst forecasts are for a big increase in profitability this year and next, so I'd be interested to find out what has changed to make that likely?
AGM trading update - it's a calendar financial year, so this update covers 1 Jan to date, ie. most of H1. The main bit says;
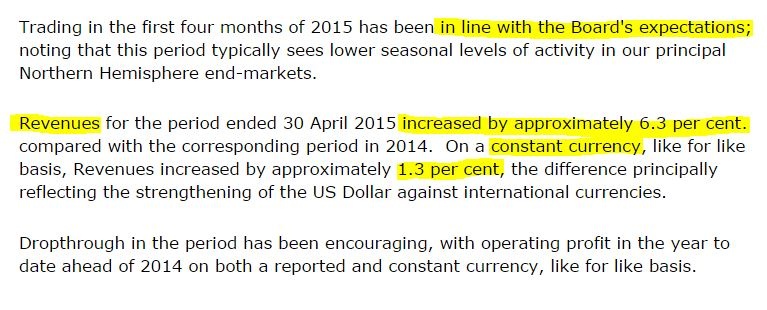
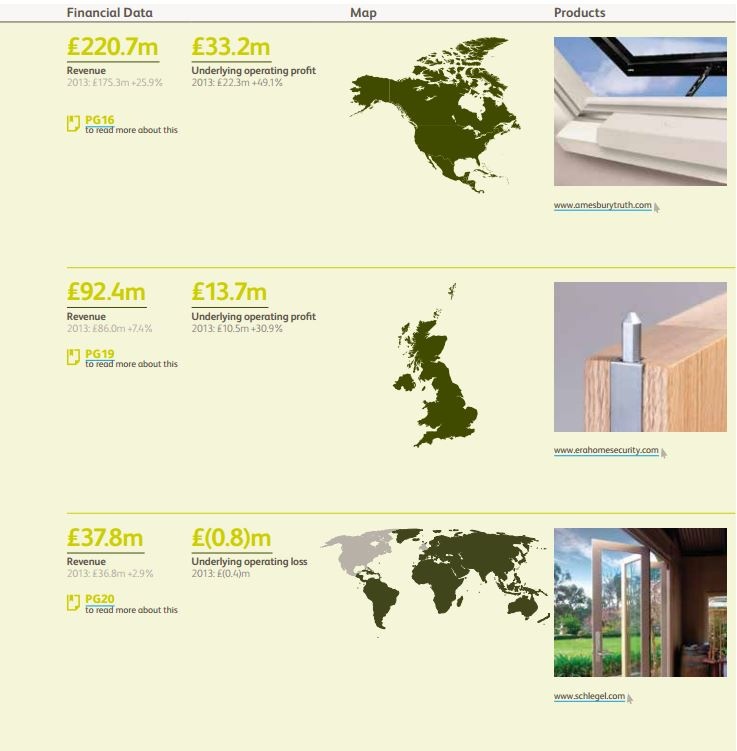
Note that they seem to have benefited from currency movements, unlike most companies reporting at the moment. I've noticed that happening lately at companies which mainly operate in the USA.
Having a look through their 2014 Annual Report, sure enough the largest subsidiary, AmesburyTruth, operates in North America.
Although note that there has been a big move in the other direction in the last month, with sterling having strengthened considerably against the dollar, from £1=$1.46 to £1=$1.575 at the time of writing.
It would probably make sense for Tyman to change their reporting currency to US dollars, as over half their business, and most of their profit seems to come from the USA & Canada.
Cost synergies of at least $8m are expected in 2015 from rationalising facilities.
ERA - this is the UK business, and these comments are interesting;
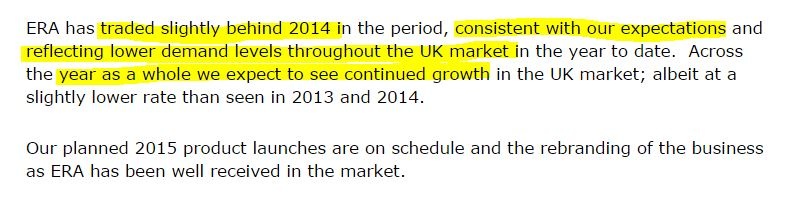
This is surprising, as the UK housing market is buoyant, and there have been update trading updates recently from both Entu (UK) (LON:ENTU) and Epwin (LON:EPWN) . Maybe they are eating some of ERA's lunch?
Balance Sheet - they say is strong, which always makes me suspicious, as companies which claim to be financially strong usually have weak balance sheets!
Well what do you know?! Sure enough, Tyman's balance sheet is stuffed full of intangibles. Net assets were last reported (at 31 Dec 2014) as £309.0m, but goodwill of £254.4m, and other intangibles of £101.3m, mean that net tangible assets are actually negative, at -£46.7m. It always pays to check these things.
The other intangibles of £101.3m is mainly "acquired brands" and "customer relationships", so those can safely be written down to nil.
The current ratio is strong, at 2.37, which includes £39.3m of cash. But long term creditors are large, at £176.2m, with the biggest item being £128.0m in borrowings. These borrowings are split about half and half between bank borrowings, and private placement notes (unsecured, with $55m due in 7 years, and $45m due in 10 years, with a coupon of 4.97% and 5.37% respectively).
I like that type of debt structure, as it reduces reliance on the whim of the bank manager.
The debt levels are quite high, but manageable by the looks of it.
Dividends - not bad, it's forecast yield is just under 3%, and has been rising strongly since divis began in 2010.
Outlook - sounds fairly upbeat;
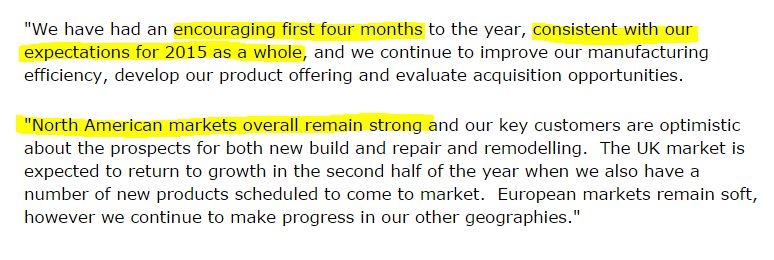
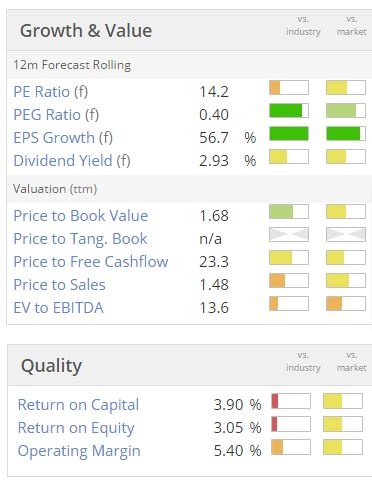 My opinion - this is an uninformed view really, as I've only just taken a fairly quick look at the company, but as I am an existing shareholder in Epwin (LON:EPWN) and Entu (UK) (LON:ENTU) which are smaller, UK companies in the same sector, then I can't help feeling Tyman looks a bit pricey in comparison. Also, the divis at Entu and Epwin are far more generous, and their balance sheets are ungeared, unlike Tyman.
On the other hand, Tyman is a bigger group of businesses, and has more geographic spread, which should reduce risk.
This sector is highly cyclical, and in a bad recession this type of company often comes close to, or actually does go bust. Note that the share price of Tyman in early 2009 bottomed out at only 8p, so clearly they were close to going bust at that point.
Will we see a recession as bad as 2008 any time soon? Probably not, but who knows?
Overall, I think Entu & Epwin look to be more attractive in both valuation & dividend yield terms.
Ideagen (LON:IDEA)
Share price: 38.5p
No. shares: 174.3m
Market Cap: £67.1m
Trading update - this was issued yesterday, and as promised I'm coming back to have a look at it, as it slipped through the net yesterday.
It's difficult to argue with this!
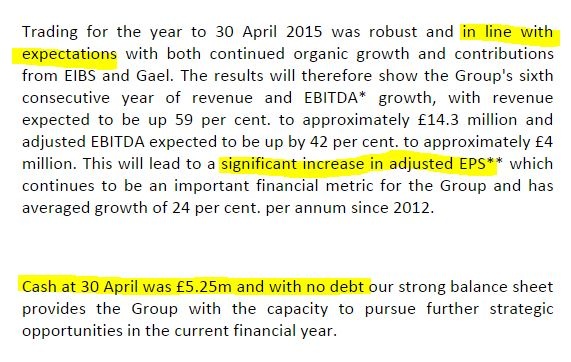
Valuation - broker consensus is for 2.08p EPS for y/e 30 Apr 2015, so that's a PER of 18.5, which looks rather high to me for a group of very small businesses (turnover is only forecast at £14.2m for the year just ended).
EPS is forecast to rise again to 2.73p in the current year that has just started, so a PER falling to 14.1 this year, if it performs in line. Even that sounds a bit toppy to me.
Outlook - this sounds very positive;
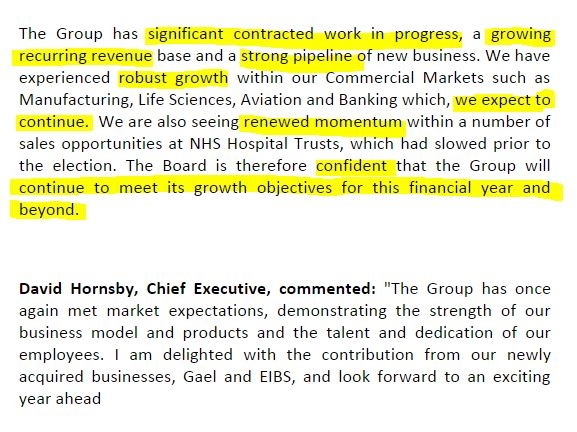
My opinion - I just can't get excited about this company. It's growing through repeated acquisitions, and doing that trick where you buy private companies cheaply, and then get a higher rating on the group. That somehow seems a bit artificial to me.
However, based on yesterday's update, it sounds as if things are going really well, so I look forward to having a good rummage through the full figures, when they are announced in mid to late July. Maybe there is more here than I realised?
Robinson (LON:RBN)
Share price: 152p
No. shares: 16.4m
Market Cap: £24.9m
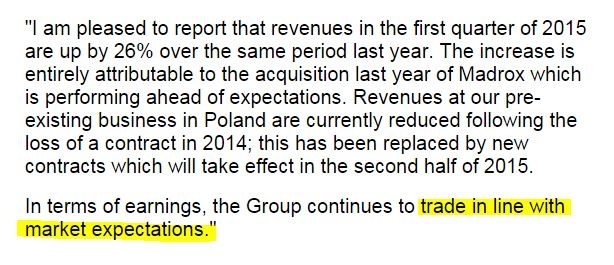
AGM trading update - they saved the reassuring bit until the last sentence!
Performance at this packaging group has been rather variable of late, reflected in broker consensus yoyoing up and down;
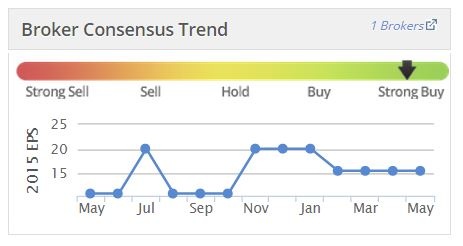
Big variations in estimates too - from 10p to 20p, and now about halfway.
My opinion - on current forecasts the PER is 10, and the divi yield is 3.37%. That looks about the right price to me, given that it's operating in a very competitive sector, supplying packaging for food products mainly.
The shares have been very illiquid when I've tried to deal in this one before, so I won't be revisiting it unless the price becomes so cheap that it's a total no-brainer. I don't think it's there at the moment.
That's me done for the day, and the week.
Wishing you a pleasant weekend.
Regards, Paul.
(as mentioned above, Paul has long positions in ENTU and EPWN, and no short positions. A fund management company with which Paul is associated may hold positions in companies mentioned)
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
20 comments
Hi Paul,
Wonder if you've had any reason to look at Tyman again recently since they came out with their (OK-ish) trading statement on November 10th? In your original commentary, you commented that they looked a potentially interesting play, albeit expensive compared to Epwin and Entu in the same sector. I note the Tyman share price is now c.240p compared to the 306p in your original report.
Given their significant US interests, this might be worth re-visiting given the US economy seems to be getting its growth act together and suggestions of further USD appreciation if interests rate start to tick up from December. Also, it looks as though there's been some institutional investor buying recently - not least BlackRock and the AXA Fram UK Smaller Cos fund which has been quite successful in the past couple of years.
All the best,
Gus 1065.
Paul
Surprised at your view of the value of Ideagen since they generate much of their revenue on a recurring nature at very high margins and now very well spread over several industries .
I did not like them much but feel now they are a more mature business with a good management structure ,decent management shareholdings ,and a verbal vow not to issue any more shares makes me much more confident .They are v. ambitious and in a fragmented market which they intend to consolidate which sounds reasonable so long as its earnings enhancing . Just a thought.
"I guarantee to buy shares in the first company which uses the phrase "slightly below" instead of "broadly in line", as I think that would demonstrate refreshing clarity and openness."
Hi Paul, more firms than you might imagine use the 'slightly below' wording in their updates - see the link... http://www.investegate.co.uk/Index.aspx?searchtype=1&words=slightly+below
One such mention I notice was Mitie (LON:MTO) in its 31-March Pre-close trading update - attendees at the recent UK Investor Show will remember the mention of Mitie in the Bear session / Short Ideas, from Evil and seconded by Matt Earl. My brief notes of Evil's pitch for this short were "safe short - Mitie. 1bn MCap, 7yrs cashflow negative. Lloyds just lent them 15-20m which keeps them going..." The thesis as I recall was that margins are wafer thin and they are coming under enormous competitive pressure, with a rising debt pile (approx. 1/4 of market cap).
The full year results are issued this Monday so we'll see how prescient they were!
Hi SM,
Interesting, but I note that only one small cap has used "slightly below" in the last month, from the list you supplied, and that was relating to turnover, not profit.
Whereas if you look at how often the word "broadly" is used (in nearly all cases to mean slightly below!), it's multiple times per day - link here. OK some of those are not related to trading, but plenty are.
Cheers, Paul.
Paul,
Tyman used to be Lupus Capital from which Greg Hutchings was ousted after huge losses but he got the company back. name change February 2013..
Hi Paul what about a comment on Powerflute which came to me on a Google Alert for "significantly ahead of the current expectations"?
http://www.lse.co.uk/AllNews.asp?code=k6x2dxcb&headline=Powerflute_To_Beat_Market_Expectations_On_Good_Start_To_2015
Funnymoney
Hi Funnymoney,
I've never really properly looked at Powerflute Oyj (LON:POWR) before, mainly because it's a Finnish company, listed on AIM, and also previous results didn't look very interesting.
However, there's no doubt today's update looks good, and they've done a big acquisition a few months ago too, so it might be worth a look.
Regards, Paul.
The important thing to emphasise about my Mello events are that they are essentially run by investors, with companies selected by investors, and for investors not traders !
Most of the company presentations are done at my Beckenham event and those are totally free to attend and you simply pay for your meal and drinks direct on the night. We have a huge potentially record breaking evening coming up this Monday with the new CEO of Crawshaws CRAW coming to present and telling us all what attracted him to the role. He was headhunted and previously the head of Lidl UK so an amazing catch for CRAW and the evening is titled 'from Lidl to large' We already have 54 investors booked in for the presentation.
The dedicated Beckenham Mello website is here.... mellomeeting.co.uk
If you want to know more about Mello and what it is all about https://vimeo.com/126247629
As investors we all need to help each other and not be in isolation or it will be really tough when things get tougher. Hopefully you can see Mello as a meeting place of mutual interest investors. There are some seriously talented investors who ask very searching questions at the events. Those who think directors of companies come to present just so they can get their share price up or get interest ahead of fundraisings or to find dumb money are wrong IMO and although some companies may do fundraisings at some point into the future it is good that our investors will have had the opportunity to get to meet management and see the quality of any investment much more in depth and of course had the chance to DYOR which is very important.
Hopefully we will see a few of you on Monday evening.
David
David
A little disappointed with Tribal's trading statement which seems a repeat of last May's so not surprised to see the initial mark down this morning or the subsequent buying interest at lower levels.
I think there is a quality business here trying to get out. In my view it won't need much good news on the contract front to get the share price moving. I think it is has built a good position in a long term growth area.
I bought a position last Monday, (should have waited until today!). I have posted my "diary entry" from Monday below:
www.tribalgroup.com
From its beginnings as a UK company it has in recent years expanded overseas and now has regional offices in Australia, New Zealand and the United States; in 2014 30% of revenue was generated overseas. Last year it entered the university market in southern Africa, complementing its leading position in the UK and Australia. It also continued to develop its presence on North America and the Middle East and made a number of bolt-on acquisitions which so that it can deliver additional capabilities in the Asia Pacific region.
Background
It had grown profits consistently between 2009 and 2013 before a hiccup in 2014 which caused the share price to drop, which I think has provided a good opportunity for me to gain exposure to a company which has good growth prospects and due to its business model one that should generate plenty of excess cash. Many of its contracts are multiyear and there is a significant and growing “software” component which delivers high margins and strong cash flow. So what went wrong in 2014? The first signs of potential trouble came in a trading statement last May when it said “As a result of anticipated timing of some important contract closures and software installations, our profits in 2014 will show a greater weighting towards the second half of the year than in 2013. We remain confident of the outturn for the full year.” In November it made a further announcement in which it expressed confidence in the full year but it was still clearly dependent on the timing of some new contracts. However, just before Christmas it issued the following: “Given the timing of a number of contracts, including those announced today, we now believe it unlikely that certain key milestones and completions will be achieved before our year end. As a result, we anticipate that our profits for 2014 will be below the Board’s previous expectations. The Board expects the benefit of these deferred contract milestones and completions will be recognised early next year, which will underpin our expectations for 2015.” This caused a drop in the share price to around the current levels before it staged a recovery up until the 2014 results which were published in March.
2014 results showed a 2% drop in revenue to £123.7m, an 8% fall in adjusted operating profits to £14.5m and adjusted earnings per share 10% lower at 11.3p. The good news, and what attracts to me this stock, was the strong cash generation, with cash conversion of 109% (cash conversion is calculated as operating cash flow from underlying operations before other cash flows and after capital expenditure, divided by adjusted operating profit.) The dividend was increased 13% to 1.8p per share. Net debt at 31st December was £11.7m compared to £14.5m at 30th June.
Why I have bought now
My argument for why it is a “buy” now is predicated on cheap valuation and the assumption that after a year of “delayed contracts” the company will return to growth in the current year. First on valuation, consensus forecasts value the shares at just 10.1x December 2015 earnings for 49.7% growth with a prospective dividend yield of 1.4% after a further 11% growth in the dividend. More importantly the shares are valued at just 10.5x free cash flow. (In 2014, despite at the earnings drop it generated operating cash flow per share of 21p, expensed 6.9p per share on capital expenditure, leaving free cash flow per share of 14.1p).
It is tempting to take the CEO’s outlook statement with a pinch of salt but I think the reasons for the slight shortfall in 2014 were genuine and that 2015 should show an improvement. “Our expectations for 2015 are unchanged. Whilst customer procurement timelines have extended, our pipeline of new customer contracts is good, including a number of expected contracts where we are preferred supplier. We also remain alert for opportunities to accelerate our progress. As a result, Tribal has good potential to make further progress this year and over the medium term.”
In his statement the CEO also set out clearly its strategy objectives and performance measures:
As our strategy evolves, it is appropriate that we also evolve our targets and performance measures to ensure they align with our ambitions. Going forward, alongside our existing financial measures which focus on profit margins, earnings per share growth and cash generation, our key performance indicators will include measures of the extent to which:
· Software and analytics-related revenues have become increasingly pervasive in our business (we are targeting at least 80% by 2017);
· We have a substantial and growing recurring software revenue base (we are targeting at least 30% of revenues to be recurring software revenues in nature by 2017);
· Performance improvement tools have penetrated our software customer base (we are targeting at least 20% by 2017); and
· We have a portfolio of international operations (we are targeting international revenues to be at least 50% of total revenues by 2017).
Earnings per share (EPS) will remain a core measure of our success in creating shareholder value. Whilst we fell short of our aspiration to double EPS over the three year period to 31 December 2014, we have grown EPS by over 200% since 2010. Our aspiration is to grow EPS by a further 50% over the next three years.
Shareholder list:
I am encouraged that over recent months some sensible investors have bought shares in Tribal; during March Henderson Global Investors and Majedie moved above 5% and Strategic Equity Capital above 3.0%. Strategic Equity Capital has an interesting approach; applying private equity investment techniques to public markets. They like to “buy good companies and sell when excellent” and look for an element of change in a business over a 5 year time horizon. I think I have spotted what has attracted them to this; strong cash flow, a growing software component and higher recurring revenues in what should be a long term growth market and due to last year’s hiccups, an opportunity to get in at a good valuation. (Could this become the EMIS of the education sector?)
I can also endorse David Stredder's Mello events. I went to the one in Peterborough and it was superb and affordable. The generosity in terms of sharing experience and expertise was brilliant.
The Share Society is also well worth joining.
Have a good day Paul and I look forward to your feedback.
Charles
LVIC for me is a once every few years treat.
As PP says the quality of the speakers are outstanding.
"...We've been given a special discount code: STOCKOPEDIA-LVIC which will get you £120 off..."
£120 off?
Cough! I had to smile at that bit. Makes you wonder what the full cost is then.
Hi Velo,
£699.00 + 20% = £838.80
£838?
Eight - hundred - and thirty eight???
Geezaloo!
Wished you'd let me finish coughing before posting that - now it's morphed into a choking fit.
Think I'll be sticking with my collection of investment books.
£838?
Eight - hundred - and thirty eight???
Geezaloo!
In terms of Quality and Value, I think it's fair to say that Carmensfella's events have a much higher StockRankTM :-)
Si
I have never been to a LVIC so cannot comment on the value for money or otherwise of an event I have never attended but I can definitely say that Carmensfella's Mello events are superb. I'd also recommend to Equity Development Investor Forums. The next one is on the 24th June:
http://equitydevelopment.co.uk/index.php?p=news
They are free as well.
Steve
Thanks Steve, that looks interesting both SAL and VLK on a single bill !
where are they usually ? is it an evening event ?
K
Hi kenobi,
SAL and VLK were at the March event, and very good it was too. The events are usually held at Fasken Martineau's offices near to Oxford Circus. They start at 5:30pm and finish at about 7:15pm followed by networking over drinks and canapés.
Steve
lol Velo! Yes, LVIC is very expensive, but on top of brilliant speakers you do get excellent coffee and a nice lunch. Does that help at all?!
Seriously though, it's aimed more at wealth managers & family offices, so the combined firepower of the people in the room probably runs to hundreds of billions, maybe even trillions!
I totally agree that David's Mello events are spectacularly good value for money, especially Peterborough - but all the speakers were happy to work for nothing, for the general good of the private investor community, and weren't selling anything either.
Regards, Paul.
I looked at the LVIC but just could not justify it based on cost (when added to all the other costs - Stockopedia, ADVFN (cancelled sub though as rubbish), magazines, FT etc) as a percentage of portfolio that I have. If that changes and for various reasons it may, I would hope to go in the future.
Have a good day and I look forward to hearing back from you.
Michael