Small Cap Value Report (15 Nov 2016) - LVD, SRT, AVAP, RCN

Good morning!
Sorry yesterday's report was late - here is the link. I looked at some unusual shares, including a speculative special situation at Johnston Press. Also a complete basket case in The Peoples Operator - almost certainly destined for the knacker's yard in my view. Plus I unravelled the complicated share structure at Dewhurst. Also a fleeting glance at results from Carr's and Castleton Technology, neither of which interest me at all.
Profit Warnings Webinar!
This is going to be great - I've already seen some of the data, but won't spoil it.
A team of analysts at Stockopedia HQ have spent months ploughing through last year's profit warnings, and drawing out statistical conclusions - e.g. should we buy after profit warnings? If so when? How do shares perform after profit warnings, and lots more.
The webinar is tomorrow starting at 12:30 - here is the sign-up link. It will be about 30 mins, with some Q&A after, I believe. There should also be a free eBook as well.
I strongly recommend readers join the webinar if you can, as this is such an interesting topic. I've lost so much money over the years by catching falling knives, that any guidance I can glean from this webinar will be very helpful.
Although of course our biggest winner here in the last 2 years was a stock I bought at 23p, straight after a big profit warning - Boohoo.Com (LON:BOO) - which has since 5-bagged!
So what to do, when, after a profit warning is a fascinating & controversial topic. Let's see what the big data at Stockopedia tells us.
Lavendon (LON:LVD)
Share price: 134.8p (up 2.9% today)
No. shares: 170.0m
Market cap: £229.2m
(at the time of writing, I hold a long position in this share)
Q3 trading update - up to 30 Sep 2016.
This generally reads quite well, and there's a fair bit of detail, mainly about revenues. A key point is that the group is benefiting from weaker sterling, as overseas earnings are translating into larger sterling amounts.
Overall performance sounds good, but this announcement is badly worded. Unnecessary confusion has been caused by the use of this phrase;
Board confident of delivering results for the full year marginally ahead of its original expectations
What original expectations? It doesn't say. This phrase is used again in the Directorspeak at the end of the announcement;
...The Board is encouraged by the trading performance to date, and as a consequence of the favorable translational impact on our overseas earnings from the continuing weakness of Sterling, we expect the Group's results to be marginally ahead of our original expectations for 2016."
What a daft phrase to use. Why would anyone be interested in what their original expectations for 2016 were? That could mean anything - do we need to refer back to late 2015, to find out what they were expecting then for 2016? Or earlier than that? Or more recently? Who knows, it's a totally confusing statement.
What they're saying is therefore that trading is going to be slightly ahead of an unknown figure that we're going to be vague about, so that nobody is sure what we mean! What use is that?!
What the company and its PR people should actually be telling us, is very simple, as it's what everyone else says in trading updates - i.e. how is the group performing against current market expectations? This is what matters, and I'm irritated that today's update has tried to be clever and somehow circumvent telling us clearly what the trading situation actually is.
As you can see from the handy Stockopedia graph on broker consensus EPS, the trend has been for a gradual improvement in forecasts in the last year;
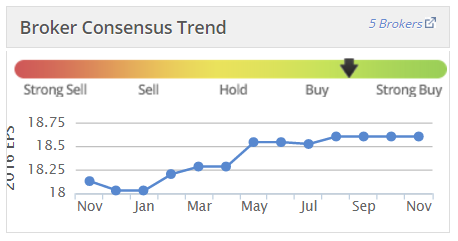
Valuation - given the confusion (and it's not just me, other investors have said the same thing this morning), I think it's best to just assume that 2016 profit is likely to come out somewhere close to consensus EPS of 18.6p.
With the share price currently at 134.8p, that makes the PER of 7.2 look very attractive.
Net debt - the fleet has been enlarged a fair bit this year, increasing debt, and also there's a negative translation effect on overseas debt. The net debt is £158m at 30 Sep 2016, of which £16m has been caused by the adverse currency impact.
That may sound a lot, but it's actually quite reasonable in the context of property, plant & equipment (mainly the hire fleet) with a net book value of £330m when last reported (H1 2016).
The company also points out today that net debt is still within their target of 1.75x EBITDA - a perfectly reasonable level in my view.
Interest rate risk - I've done some digging to find out what exposure Lavendon has to potentially rising interest rates. This is what is said in the 2015 Annual Report on this matter;
The Group’s debt facilities total c.£165 million and comprise revolving bank facilities of £50 million and €60 million maturing in June 2019, together with US Private Placements with a combined value of €95 million (being loan notes of €60 million, €17.5 million and €17.5 million maturing in July 2019, August 2021 and August 2024 respectively).
The available headroom within this financing package at 31 December 2015 was c.£35 million.
The bank facility has an interest rate margin, linked to the level of leverage of the Group, of between 150 basis points and 230 basis points above LIBOR or EURIBOR depending on the currency drawn.
The US Private Placements have fixed coupons of 4.89% for the €60 million note maturing in July 2019; 2.54% for the €17.5 million note maturing in August 2021; and 2.92% for the €17.5 million note maturing in August 2024.
These facilities provide the Group with a robust medium to long term diversified financing package that will support the growth plans of the Group in the coming years.
The Group has exposure to movements in interest rates on its borrowings. This exposure is managed by maintaining a mix of fixed and floating interest rate borrowings. This allows the Group to mitigate the impact of interest rate fluctuations, by allowing some benefit from rate reductions, while offering some protection against rate rises.
At the year end, the fixed rate element of borrowings was 55%, a marked decline over the previous year’s fixed rate element of 70% reflecting the utilisation of the Group’s banking facilities at variable interest rates to finance the Group’s increased investment during the year.
Based on the year end mix and quantum of borrowings, a movement in Euro interest base rates of 0.25% would increase or decrease the Group’s annual interest cost by approximately £20,000 while a similar 0.25% movement in £ Sterling base rates would also increase or decrease annual costs by £123,000.
(taken from pages 32-33 of 2015 Annual Report)
That all sounds sensible to me, so I'm not worried about the debt situation, it looks OK, and a lot better than some other hire companies (e.g. HSS).
Dividend yield - is currently forecast at around 4.6% - pretty decent.
My opinion - I really like it, because the valuation is so compelling. The group is dominant in a profitable niche, and seems to be performing well.
So why is the PER so low? The answer seems to be that some analysts are worried about a potential downturn in Lavendon's highly profitable operations in the Middle East. Also, payment terms are slow in that region, and there are concerns over pricing being eroded possibly? Plus the nightmare scenario of some major geopolitical trouble kicking off again in that region.
That said, these concerns seem to be weighing too heavily on the valuation, which looks strikingly cheap to me. The company keeps putting out decent trading updates, and the market keeps ignoring them & fixating on potential risks.
My feeling is that the mood seems to be changing, with Governments beginning to recognise that ultra-low interest rates alone are not enough to stimulate growth. Big infrastructure programmes are now being mooted to provide a conventional Keynesian type boost to economies. That seems to be the way Trump is indicating that he favours. Maybe Europe might eventually follow suit?
I'm only mentioning this, as I can foresee this changing mood perhaps being positive for Lavendon. If the market starts to see the glass half full, then it's not a big stretch of the imagination to see LVD shares re-rating, up to a share price maybe in the 200-250p range. That would still only be a PER in low double digits, which is hardly a stretch.
Time will tell, but for me, risk:reward looks quite good at c.135p per share.
EDIT: the company held a results webcast this morning apparently. There should be a recording up on its website later today, here is the link.
SRT Marine Systems (LON:SRT)
Share price: 38.3p (down 1.7% today)
No. shares: 127.6m
Market cap: £48.9m
Interim results, 6 months ended 30 Sep 2016 - this company describes itself as "a developer and supplier of maritime identification and tracking technologies".
H1 results today are in line with an update given on 6 Oct 2016, which I reported on here. So the figures themselves should not contain any surprises - we had already been told that H1 results were not much cop.
- Revenue of £2.7m in H1
- Loss before tax of £1.2m
- Cash of £1.8m
These are all exactly as indicated in the last trading update on 6 Oct.
Note that the cash figure quoted is gross. There is £1m in debt to subtract from that, to arrive at the net cash figure of £0.8m - looking a bit tight, in my view, if the company has another poor half year in H2.
The narrative seems subjectively less upbeat than usual. It also refers to delays in demand from projects which have gained official approval, unless enforcement action is taken;
The USCG AIS regulation, which requires a significant number of large commercial vessels in the USA to fit an AIS transceiver, came into effect in March 2015. However due to a lack of strict enforcement action by the relevant authorities, demand from this market has been minimal to date and is now considered likely to take a number of years to come through as enforcement is undertaken.
Outlook - the company feels more optimistic about H1, as it has said before;
I am pleased to report that during the Period we saw significant progress in a number of large VMS and MDM projects that we expect will result in the completion of significant deliverables during the second half as well as other projects moving towards contract phase from our validated sales opportunity pipeline.
The nature of these projects is that they are very lumpy with extended periods between deliverables and often change unexpectedly in terms of timing and scale.
However, we expect that SRT will soon have multiple projects underway which we hope will provide a natural hedge in regards to revenue timings across our reporting periods.
Most of our projects are considered to be of national strategic importance and thus SRT is subject to strict confidentiality which places significant restrictions on the details we can provide shareholders on the status of these projects.
My opinion - I don't think there is enough red meat in this RNS to justify a market cap of nearly £50m. I've no doubt that the company has good technology, and a potentially big pipeline. The trouble is, that the repeated, multi-year inability to demonstrate sustainable progress with sales makes me very nervous.
I certainly wouldn't be happy to hold at anything approaching the current valuation. The revenues (and hence profit/losses) just seem completely unpredictable here. That makes it very difficult to value the shares.
Even if big orders do translate into sales, it could just be a blip, with another disappointment around the corner once a lumpy order is delivered.
Avation (LON:AVAP)
Share price: 187.4p (up 2.4% today)
No. shares: 58.9m
Market cap: £110.4m
AGM statement (trading update) - this is quite a detailed update, and summary. There's not really much point in me regurgitating it all here, as you can just read the announcement yourself, which is all self-explanatory.
I've read it twice, and can't see any reference to trading as such. The most interesting bit concerns an update on the approach the company received from a third party wishing to buy its portfolio of 22 ATR turboprop aircraft. That has previously been announced here on 26 Oct 2016.
Today, the company says it's throwing the potential transaction open to other interested parties, obviously in an attempt to maximise the potential sale proceeds. Any profit on disposal over book value would (at least in part) be returned to shareholders, which sounds interesting.
This comment is intriguing;
"The Board observes that Avation PLC ordinary shares are presently trading at a discount to the net tangible assets. It is therefore appropriate and in the interests of shareholders to consider asset sales that generate a premium to book value as a way of delivering enhanced shareholder returns.
That makes complete sense to me.
My opinion - it seems that AVAP is now actively trading its aircraft, where it can generate decent profits against book value. Then redeploying the proceeds into buying new aircraft. Anything that creates profit for shareholders is very sensible, in my view.
This more active approach could well be a catalyst to eliminate the discount to NAV, which is positive for shareholder value. Looks interesting.
Redcentric (LON:RCN) - this is the company where the share price collapsed on 7 Nov following an RNS disclosing accounting misstatements. There's another update today. It doesn't really say a lot, other than that (expensive-sounding) accountants & lawyers (Deloitte & Nabarro, respectively) have been brought in to carry out "independent forensic examinations".
An interim CFO has also been recruited, following the old one being sent packing.
My opinion - no change to my article last week, which is here. As I mentioned at the time, the sell-off looked overdone. However, I'm wary of getting involved here, as in this type of situation the bad news often comes out piecemeal, over a period of time.
That will have to be it for today. I didn't get round to looking at Renold or Carclo - it takes a lot of time & effort to plough through each company's accounts, and you just run out of mental energy at a certain point. If it starts to feel a chore, then it's time to stop - because the commentary will be rubbish.
Regards, Paul.
(usual disclaimers apply)
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

32 comments
Lavendon (LON:LVD) share price is up but c.25p off the putative offer suggesting the market initial reaction is that (a) may not be another bidder; and (b) TVH won't go hostile (I.e. Will only proceed with a management recommendation which may or may not come depending on shareholder reaction). A gambling man might think it worth a punt to buy at the current 183p market offer if they thought either of the above don't apply.
Best,
Gus.
Would agree with you gus, but even at 183p its not expensive. At least we know what TVH are prepared to pay for it, so have a better handle on valuation. I think the broker target was 275p, so 205p looks cheap.
Not recommended by the company though... so lets see how much higher it may go?
Cash bid at 205p per share just announced for Lavendon (LON:LVD) . Here is the RNS link. Not sure it is quite the knock out blow recently seen for Avesco (LON:AVS) but company now in play.
http://www.investegate.co.uk/tvh-group/lvd/final-cash-offer-for-lavendon-group-plc/201611220700117677P/?fe=1&utm_source=FE%20Investegate%20Alerts&utm_medium=Email&utm_content=Announcement%20Alert%20Mail&utm_campaign=TVH%20Group%20Alert
Busy time on the M&A front.
Best,
Gus.
It is always worth reading the Chairman's statements at Samuel Heath and Sons (LON:HSM). Today's is no different, nor any less refreshing than normal. (The read across to Norcros (LON:NXR) is not particularly encouraging for the near future).
I thought you were going to do a write up of CAR? I guess you ran out of time...
...so, for those interested, CAR announced interims yesterday and a positive in-line trading update... although the price has softened after the initial rise, possibly due to the huge increase (more than doubled) in IAS 19 retirement benefit liability
For a more detailed view of the potential ATR fleet sale and its potential impact on the company, see http://www.lemonfool.co.uk/viewtopic.php?f=33&t=315
Carcosa
I've held AVAP for over a year and am sitting on a reasonable profit. Inclined to hang on. and see what becomes of the offer if any.
Re Avation,
I agree that disposal of the 22 ATR aircraft would release good shareholder value assuming the right price. It would also allow a beneficial rejig of the remaining fleet. Pipeline ATR orders would still be available to either retain or sell whilst probably more profitable but more expensive A320 series aircraft could be added to the fleet. Result a better balanced fleet with a wider end user profile with commensurate less risk. Seems positive to me.
Mark
TRCS
Listening again to the PS interview Nov. 15 and looking at the subsequent data it clearly didn't deliver on the tone of the interview and a lot of important holder's voted out.
However, with such a small cap it could be premature to judge harshly on a year's performance.
I expect some good news to be saved up for the results.
apad
TRCS
Will certainly be looking at organic growth compared to acquired growth in their annual report which is due tomorrow, I believe?
The business has several different divisions and these probably all have their own individual growth characteristics.It does pay a dividend, but is not a big yielder, so it does return some cash to shareholders. It is avowedly acquisitive, so always a balance between new targets and rewarding shareholders.
Some of these business have pretty high net margins (which they do not advertise) so if it is able to successfully cross-sell from acquired operations, or grow organically, it should materially benefit the bottom line. Of course cross-selling is easier said than done!
They do pick and chose their acquisition targets to match certain published criteria (referred to on their website). So no desperation there for a fundamentally cash generative company. The problem may be that it may have picked up all the 'cheaper' acquisition deals, and new deals may get more expensive, and use more of the cash generation.
I am holder, albeit given the decent multiple they are on, a little nervous.
TRCS “Look and Feel”.
8th January, John McArthur, Chief Executive, disposed of 120,000 ordinary shares of 0.4p each ("Ordinary Shares") in the Company, at an average price of 515.9p per Ordinary Share.
10 Mar 2016
IP Group plc (LSE: IPO) (“IP Group” or “the Group” or “the Company”), the developer of intellectual property-based businesses, is pleased to announce that it has realised its entire holding in portfolio company Tracsis plc.
The Group received net cash proceeds of £13.1m from the sale.
Sean Lippell, Non-Executive Director and former corporate law partner, has departed with immediate effect. He has been removed from the website.
Friday 8 April, John Nelson, Non-Executive Director, disposed of 130,000 ordinary shares of 0.4p each ("Ordinary Shares") in the Company, at a price of 500p per Ordinary Share.
19 April 2016Uni Leeds sells 500,000
1,000,000 left.
25 April Leeds Uni disposal less than 4% left.
No large framework order.
US order small, could still take years - what is their driver.
Acquisitions look bitty. Missed a big one, but “it wasn’t good enough for us.”
Doesn’t return cash to shareholders.
Only 8 solid job vacancies.
So, on the whole, looks to be ex-growth to me.
We'll see what Tracsis (LON:TRCS) reports on 17 Nov. The stampede towards driverless cars seems irresistable: Ford, Uber and others say it's five years away, the academic researchers say the technology needs some research breakthroughs which will take between 10 and 35 years, and the politicians want to capture the revenues, jobs and innovation. Meanwhile, any company with technology that might offer an edge seems to attract a premium valuation. This isn't going to end well, but there's money to be made on the way.
Avation is essentially a finance company so the debt level is normal. But by buying aircraft that they then attach an earning stream to they considerably enhance those assets.
Their statement is that over an average lease period of 6.3 years "in excess of $305 million" will be received by a buyer, at the end of which they will have a re-leasable fleet of 22 aircraft, mostly under 10 years old.
This should realize enough to make the remaining Avation fleet of 17 mostly young jets carry a very much reduced debt. I would expect them to use this as a springboard to load up more debt and accelerate their jet acquisitions
Questions for TRCS interview, Paul. Where and when?
apad
Hi apad,
I'm doing my traditional annual interview with John McArthur next week, on 23 Nov.
I thought that would give readers time to digest the results (out tomorrow morning) and come up with some good questions.
I'll put up a form on QSC in the next few days, to ask for your questions.
Regards, Paul.
P.S. I'm not charging a fee, and don't hold TRCS myself, so it's completely independent.
Excellent, Paul.
apad
ps
Do you have an easy way of checking the rate of change of shares in issue, their most common rns is about printing more shares!
Avation (LON:AVAP) has a lot of debt. Therefore, taking Stockopedia's numbers, it may be trading at a 20% discount to net book value - Its enterprise value will only be a small % discount to its gross asset value. Clearly, given the leverage, if it can sell its planes at at premium to book, there could be significant upside in the share price - but the leverage also means that there is not that much room for slippage.
Paul
Did you publish your thoughts after recent chat with STAF ...
Thanks
Justin
Hi Staverly,
Did you publish your thoughts after recent chat with STAF
Yes, I published my audio interview with STAF's CEO here last week: http://qualitysmallcaps.co.uk/ceo-or-fd-interviews...
Regards, Paul.
Paul
Your views on Hayward Tyler (LON:HAYT) interims today would be welcome. They have given a lot of detail of recent sales and the pipeline.
Regards
Agree with the thrust of this article - be even better if they ranged their current expectations as some companies do
Paul,
RE: Lavendon (LON:LVD). To be fair, they always use reference to their own internal expectations in trading updates. Only in the full year update do they refer to market expectations. It doesn't make it right but at least they are consistent. Don't shoot the messenger, I'm just pointing out this is nothing new and so does not indicate any intentional vagueness in today's update which others may infer.
All the best, Si
Si,
I haven't got any problem with companies referring to "management expectations" or "Board expectations" during the year, instead of "market expectations". That's OK, because those phrases are usually used because the market doesn't actually have forecasts for part-year results, but only for full year results.
So that's not what I'm objecting to. My problem is with Lavendon using the words "original expectations". What does that mean? To me it implies that they're talking about forecasts maybe a year ago. Who knows? It simply isn't clear.
What they should be telling us, is whether current performance is in line with management or market's current expectations. That's all that matters. It's what everyone else does, so why is Lavendon using its own, vague, form of wording? They need to sort this out, as it's a stupid own-goal in my view. Trading updates need to be completely clear, and unambiguous. This one isn't.
Regards, Paul.
HI Paul,
I agree. All I was saying is that their own "original" expectations were never made public to my knowledge, so there is no reference to work from in absolute terms. It is not satisfactory but I would assume their own original and current expectations are reflected in the forecasts of the house broker, Peel Hunt.
All the best, Si
Hi Si,
Yes I note that Peel Hunt have upped their 2016 EPS forecast today by 3%, to 19.1p.
I should probably put that in the main article as an edit.
Regards, Paul.
Paul
I see that LVD's operating cash flow for the last year was negative, largely due to investment in renewing the rental fleet. If I’m reading the reports correctly they invested £91m in 2015 and a further £55m in H1 2016. Presumably there will come a point in the fairly near future when such substantial fleet investment will no longer be necessary and operating cash flow will revert to being positive, as it was consistently from 2010 to 2014. Any thoughts on when this might be?
Generally I wondered what you thought about Stockopedia's DCF tool. I know it's there 'for educational purposes only' etc. However, over the last few months I've been recording the 'crude' values it spits out in a spreadsheet for a number of companies; then (1) dividing given DCF value by price at time X and (2) dividing price now by price at time X. The correlation between the values for (1) and (2) has come out at nearly 0.8, way higher than the correlation of 0.1 between Stockopedia ranks at time X and (2).
Regards, David
Part of the Lavendon (LON:LVD) picture is they've got a persistent overage debtor position in Saudi which is hitting cashflow , it's going to turn into cash or bad debt, company says cash but I sold when they didn't respond to my email asking for a few more details to get me comfortable that it wasn't a problem.
Aside from that it looks very cheap .
(1) dividing given DCF value by price at time X and (2) dividing price now by price at time X. The correlation between the values for (1) and (2) has come out at nearly 0.8, way higher than the correlation of 0.1 between Stockopedia ranks at time X and (2).
You need to divide successive (e.g. daily, weekly or monthly) values for DCF by the previous value and compare that with the same calculation based on price, before you calculate the correlation. If you don't do that, you will have what is called a unit root in your data which will overstate the amount of correlation.
Re. Lavendon (LON:LVD) I think you are right to take the management to task in putting out loose, ambiguous statements.
Looking at the historical progression of eps chart, the expectation has gone up since Nov. last, so if they mean "ahead of original expectations" then it could well be that we are now into "equals current expectations".
It could all be avoided by a little more care in "saying what you mean".
Paul, I noticed in the Lavendon statement that they mentioned that in the Middle East 'the level of free cash generated from the region is increasing significantly in 2016'. I think the late payment practice in that region had been putting some off.
Also I notice that the German business is now profitable following the reorganisation. I take the statement as being overall positive and agree with you, it is cheap and has a decent dividend.
Steve.
On Lavendon (LON:LVD) Within the Middle East, the apparent increase in business outside Saudi and the comparative decline in Saudi should help the average days outstanding on the trade receivables (as well as lead to lower margins). Significant improvement in trade receivables would lead to a rerating of the shares IMO.
However, although the Q3 updates states that the Gulf had generated singificant cash - this does not yet seem to have fed through to the net debt figure At end Sep, this is £158 million versus an end-June level of £149.7 million, with end-year forecast (at the time of the H1 results) of a similar amount, if fx rates are unchanged. While sterling has weakened since June, most of the weakening obviously happened right at the end of June.