Small Cap Value Report (15 Oct 2014) - CNCT, VTU, ANCR

Good morning! I attended ShareSoc's seminar on improving shareholder rights last night, and must say what a fantastic event it was - ShareSoc is really pulling out all the stops on this, and organised a highly professional meeting with some big name speakers such as Lord John Lee, Michael Kempe of Capita, Professor John Kay (of the Kay Review), and four others. Everyone made good points, and it seems to me that we now have the ear of policy-makers (a lady from the Govt BIS Dept was there too) and everyone is pulling in the same direction - i.e. it is recognised that the nominee a/c system currently disenfranchises small shareholders, and that an electronic system is long overdue, which will allow us all to be directly listed on the shareholder register - thus no more hassle with letters of representation for AGMs, but most importantly shareholders will now be able to stop errant management in their tracks by sacking them more easily, voting down excessive remuneration packages, etc.
Some people say, well we can do that already, or I don't invest in companies where management abuse their positions, etc. However, in my view some company management get away with murder because there is nothing to stop them - they know that a large part of the shareholder list can't or won't vote. As I said yesterday, an absentee shareholder base that is disenfranchised has created a greedy, self-serving management class. I am really looking forward to changes in the rules that will give shareholders teeth again. Sadly, we will have to wait years for these changes, I think 2025 was mentioned. Surely reform can happen more quickly?
To view ShareSoc's proposals on shareholder democracy, please see their publication here. Also there is a petition for signature here.
Connect (LON:CNCT)
Share price: 162p
No. shares: 189.3m
Market Cap: £306.7m
Preliminary results - for the year ended 31 Aug 2014 are out today. They look quite good. This is a distributor of newspapers & magazines, that has also branched out into other areas.
Turnover and profit are both flat against last year, at £1.8bn and £50m respectively.
What they call underlying EPS is up 2.8% at 21.7p.
Valuation - it looks attractively priced on a PER basis, which is a PER of only 7.5.
However, on digging a bit deeper, the valuation is low due to the company having a weak Balance Sheet.
Balance Sheet - net debt is too high in my view, at £93.0m. Also, if you write off intangibles, the Balance Sheet net equity is heavily negative at £107.8m! That's really not a prudent financial position at all. Moreover, working capital is negative, with the current ratio being a worrisome 0.72, which is far below what I would consider to be an acceptable level.
This may not matter when times are good, but what happens if the company runs into trouble of some kind? It would then be completely reliant on the support of its bank. That would scare me too much to invest here.
Dividends - The company is paying an attractive divi of 9.7p, for a yield of 6.0%. Personally I don't like financially weak companies paying big divis. They should cut the divi and rebuild the Balance Sheet in my view.
Outlook - sounds fine;
Recent trading is in line with current management expectations and we remain in a good position to build on the progress made this year.
My opinion - I can see the attraction, if you like a low PER and a good dividend yield, and are not too bothered by a weak Balance Sheet.
Vertu Motors (LON:VTU)
Share price: 57.2p
No. shares: 340.3m
Market Cap: £194.7m
Interim results - for the six months to 31 Aug 2014 are out today, and look impressive to me.
Revenue is up 29.5% to £1,084m, helped by acquisitions. Profit before tax is up 49% to £12.8m. Not bad going.
Balance Sheet - this looks solid, with £34.4m in net cash, and lots of freehold property.
Valuation - looks reasonable, on a current year PER of about 11, although the dividend yield is not great at only 1.8%.
My opinion - the listed car dealers all look priced about the same level, and there's not much to choose between them in my view. Whether there is any more upside on the new car market is the big question, after several years of strong growth?
Animalcare (LON:ANCR)
Share price: 136p
No. shares: 21.0m
Market Cap: £28.6m
Full year results - for the year ended 30 Jun 2014 are published today. They look OK - revenue up 6.3% to £12.9m, and underlying profit up 4.4% to £2.8m, so a strong profit margin there.
Underlying EPS is up a little to 10.8p, so that means the shares are valued at a PER of 12.6, which is probably about right.
I like the strong Balance Sheet with net cash of £3.8m.
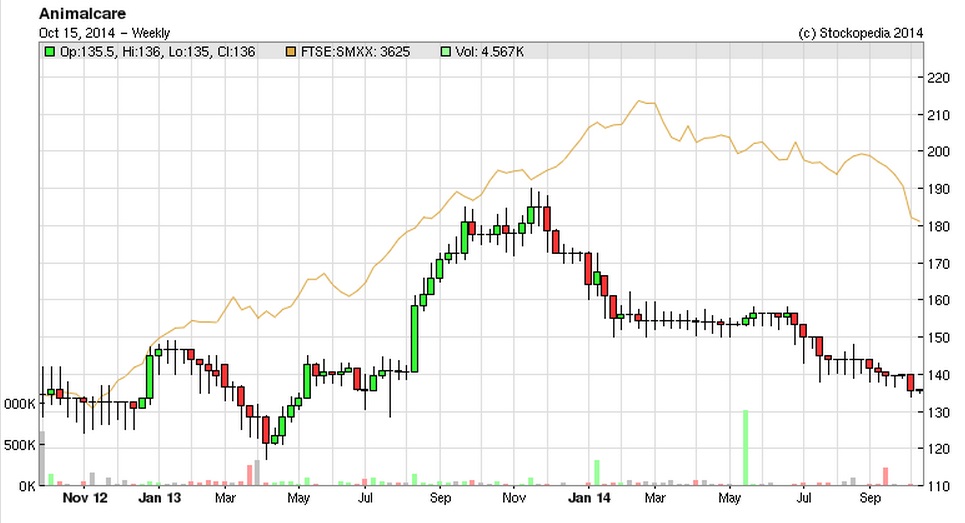
As with most small caps, it's just drifting down in price, as everyone sits on the sidelines waiting for prices to bottom out. So there should be some strong rebounds when confidence returns, as a lot of people will pile in at the same time.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

9 comments
I see the incoming chairman at VTU has bought another 500,000 shares - now owns 1m. Good to see such confidence.
I hold BTW.
Tough day indeed. Here is how I handle times like this.
If you are worried about the situation and the market tanking, you are holding too many positions - sell some! When you are not worried whether the market goes up or down, then you are in equilibrium. On the one hand, you will not lose too much cash if the market continues to fall - on the other hand if it rises, you have cash to buy in at lower prices.
Market continues to fall - you get worried again and you see your capital reducing - sell more positions. When market recovers (and watch you don't buy too early!).... then buy back in.
Most important - sleep easy at night whilst preserving your capital whatever the market does!
Thanks Paul for your comments on the Sharesoc meeting. I need to say that I have no issues with the current nominee system and Barclays my on line broker always provides me poa's efficiently in the rare cases they are needed.
To me honest far more important IMJ is the issue you highlighted in your Tuesday report of the way that news on placings are leaked to the market and a review if shares should be suspended.
I acknowledge the energy you, Sharesoc and indeed UKSA are putting into all of this.
Thanks Paul for the report. This is a very interesting time, as it becomes easier to find bargains by the day.
You say that "the listed car dealers all look priced about the same level, and there's not much to choose between them in my view." Actually, I think there is one which is strikngly cheaper that its peers, and its Caffyns (LON:CFYN) : at 485p, it is only priced at 6.4 times last year's earnings, which are set to grow this year, judging by the last trading statements. it gets even better than this, as the shares are on a 25% discount to net asset value, before taking into account a 6m surplus of freehold properties over book values (not included in the balance sheet) and a 860k cash property sale this month (i.e. post balance sheet).
This is a family-owned company, with share arrangements that are favourable to the family, and takeovers are very unlikely. However, I think the discount is excessive, even after taking that into account. The 18p dividend for the last year (up 50% on the previous year, and a 3.7% yield at the current share price) couldn't hurt either!
Disclosure: I am long on Caffyns (LON:CFYN)
Ooof, what a day. My portfolio was holding up reasonably well in recent weeks but now even the quality companies are being sold off. I'm finding it quite hard to hold my nerve and have to keep checking the fundamentals to reassure myself. Interested in your comments on Vertu, Paul. Am I right in thinking that you no longer hold Cambria? If so, did you have a particular reason for selling?
Best wishes, and many thanks for these brilliant updates.
Paul (another one)
You can say that again.. Nothing is immune to the sell off. The market has been very brutal over the past month and my portfolio is a sea of red. There has to be a turning point at some stage. Perhaps the ECB will unleash some quantitative easing in the near future. My watch list is getting larger by the day and there are some good quality companies on the radar, which look interesting. I'm steering clear of small caps for the time being and concentrating on mid/large caps with a combination of value and quality (and a decent yield). For example I have just purchased some Catlin (LON:CGL), which has a forward PE of 9.2 and a forward yield of 6.9%. I also like Home Retail (LON:HOME), GlaxoSmithKline (LON:GSK), Old Mutual (LON:OML), 3i (LON:III), Royal Mail (LON:RMG), Kingfisher (LON:KGF) etc.
Connect claim FCF of £37.2m, and yet according to my calculation it is £13.5m.
Net cash from op activities 47.4
Plus Int/Divi received 0.2
Less PPE incl Tangibles 10.3
Less Int/Divi paid 23.8
Result = 13.5
Have I missed something?
Dividend paid was £17.7m. Add it back: 13.5+17.7 = 31.2. We're not at £37.2m, but we're getting closer.
Dividends are distributions to shareholders from company funds, so you exclude them from the calculations. "Free cash flow (FCF) is the amount of cash that a company has left over after it has paid all of its expenses, including net capital expenditures. Net capital expenditures are what a company needs to spend annually to acquire or upgrade physical assets such as buildings and machinery to keep operating."
Note 3 within the results details how they have calculated FCF of £37.2m:
(3) Free cash flow is cash flow excluding the following: payment of the dividend, acquisitions and disposals, the proceeds on the disposal of freehold properties, repayments of obligations under finance leases, the repayment of bank loans, EBT share purchase, and cash flows relating to non-recurring and other items.
Personally I think there calculations of FCF are rather aggressive. I would have calculated FCF the way you have detailed, but I'm by no means an accounting expert!