Small Cap Value Report (16 Sep 2014) - PTCM, CRW, THAL

Good morning! Busy day for me today, as I have to get this report written, and then meet management of Spaceandpeople (LON:SAL) for lunch, to discuss in more detail what's gone wrong, and what they are doing to fix it.
Porta Communications (LON:PTCM)
Share price: 9.0p
No. shares: 229.7m
Market Cap: £20.7m
Interim results are published today, which look pretty good to me, although you have to be a bit sceptical with this company, as they've heavily over-egged results announcements before - which presented an overly optimistic view of performance in the past, in my view. This was most in evidence with stripping out "start up costs", which looked ridiculous, being defined as the first two years' losses!
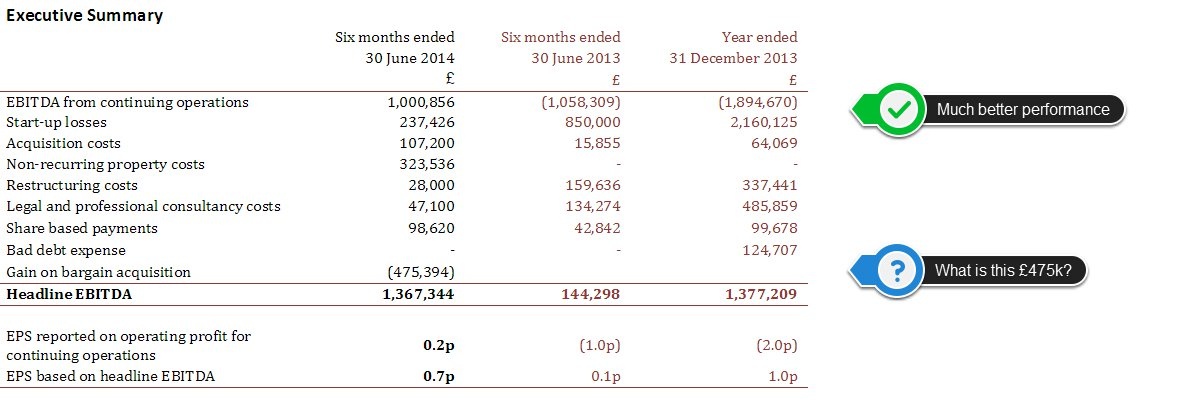
Profitability - I'm pleased to see in these interims that headline EBITDA of £1.37m benefits by only £237k by stripping out start-up losses, versus £850k start up losses in H1 last year. This suggests that all individual parts of the group are either profitable or close to profitable.
So it looks as if Porta is now a viable business, with a whisker over £1m in positive EBITDA in H1 of calendar 2014. That's a good turnaround from last year, as the following table from today's results shows;
There were some early buys first thing, as you would expect when much improved results are announced, but a big seller seems to be whacking the price at the moment (08:48), so I am pondering whether to buy some more? Although before pushing the buy button I'm trawling through the figures & narrative again, to ensure I haven't missed something that the big seller has spotted.
It looks as if the £1.0m continuing operations EBITDA figure has benefitted from the £475k "Gain on bargain acquisition", whatever that is? So altogether a rather confusing array of adjustments - what should we treat as bona fide, and what should be stripped out as genuinely one-off? It's difficult to decide, but at least it's clear that the company is trading a lot better than last year.
Ah, I've found a brief comment on the £475k credit to the P&L, which the company describes;
The acquisition of the WSM Digital business resulted in an estimated gain of £475,394 which has been included in the Income Statement in accordance with IFRS accounting requirements.
So I think that needs to be reversed out to ascertain proper underlying EBITDA, so we're looking at about £526k on that measure, for six months, so just over a million pounds in a full year. Note 6 in today's figures explains that this gain came from negative goodwill, by what looks like an arbitrary creation of an intangible asset for £510k for "brand and customer relationships", which as far as I am concerned is effectively fictitious profit. Hence the £475k credit definitely needs to be disregarded.
I'm relaxed about them using EBITDA in this case, as I've checked that nothing untoward is happening in terms of capitalising costs, and there was only £16k of costs capitalised into intangibles in H1, for software & websites. That's fine. There was a £405k amortisation of intangibles charged to the P&L in H1, which I am happy to disregard as the intangibles are mostly notional figures that the company has created for goodwill, customer relationships, brands, etc, all of which I regard as being best written down to zero.
Outlook - There are two sections in today's results with forward-looking remarks, as follows;
The Group continues to show rapid growth in both revenue and gross profit (fee income) reflecting the integrated product mix and the growing maturity of the start-up ventures together with the success of the expanding international capability. Organic growth is expected to be strong in the second half while the management team are looking to build critical mass in all the operational areas by selective quality acquisitions.
Given the improvement expected on the advertising side together with continuing strong organic growth in the public relations businesses both in the UK and overseas, the Board remain optimistic about the Group's future prospects.
So just a generic optimistic remark at the end, but note that strong organic growth is mentioned twice. That sounds encouraging, especially when combined with figures showing that the company is now in profit.
Balance Sheet - This is just about OK in my view. Net assets of £14.9m drops to just £0.4m when you write off the intangibles. The working capital position is just about OK, although WIP and Debtors look a little high to me, but not alarmingly so.
Net debt has reduced from £3.1m to £1.9m in the last six months, due to fresh equity being raised. The company seems well supported by big shareholders such as Hargreave Hale, who took part in Placings. That gives me comfort that growth has been achieved without excessive debt being taken on, and that possibly more Placings could be done if suitable acquisitions are identified. As long as they don't take the mickey with the discount on any future Placings, then I can live with that.
My opinion - The strategy here was to rapidly build an international advertising & PR group, and it seems to be going reasonably well. Today's figures are the first time the company appears to be making proper profit, i.e. not relying on accounting trickery to generate fake profits, which is what I feel they've done in the past.
You always have to be very careful with the accounts of PR companies, as it's their job to create positive things out of thin air for their clients, hence that approach will usually be taken with their own accounts too!
Overall though, this company is starting to deliver the goods in my opinion, and I'm encouraged by the move into positive EBITDA, and the outlook for H2 indicating strong organic growth. Therefore I'm happy to continue holding for another year. Note that there was a decent chunk of Director buying ££165k in total between 10-11p per share) in June 2014, so it will be interesting to see if the Directors dip into their pockets again now the share price is lower?
Note that the Directors are old hands in the PR sector, which is one of the key reasons I'm invested here - they've built a decent sized PR business before, so they already know how it's done.
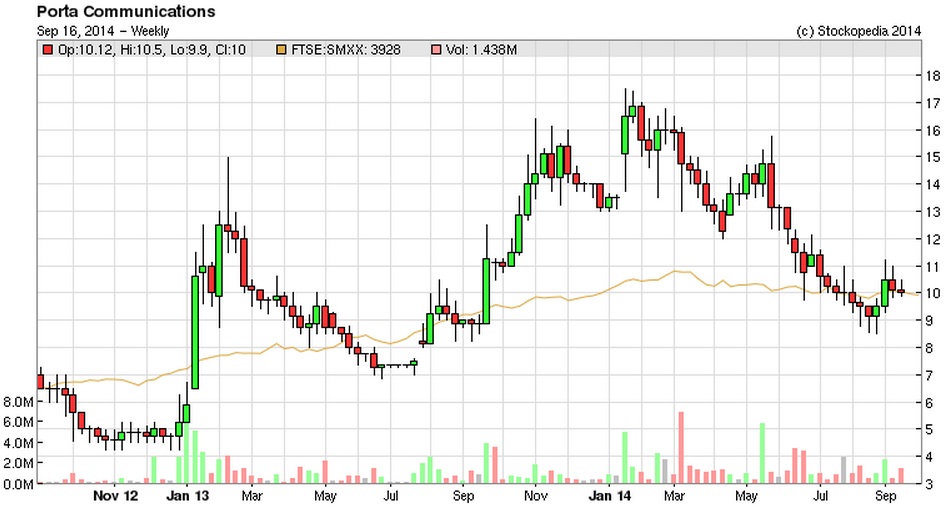
It's been a rollercoaster for shareholders, see the two year chart below. My simplistic view of charts suggests that another wave up might be on the cards now, given that's what has happened in the past after a wave down:
Craneware (LON:CRW)
Share price: 528p
No. shares: 26.8m
Market Cap: £141.5m
This is a software company, based in Edinburgh, which supplies revenue collecting software to a quarter of the hospitals in the USA. That's a pretty jaw-dropping achievement, and this company must have significant strategic value to an acquirer. Hence I'm tempted to buy some just for the takeover potential. Imagine the cross-selling potential if you are embedded into a quarter of the hospitals in the USA with software that one imagines must be critical to those hospitals day-to-day operation?
It's also a decently profitable business, making an excellent profit margin - see the green "quality" scores on the Stockopedia graphics below.
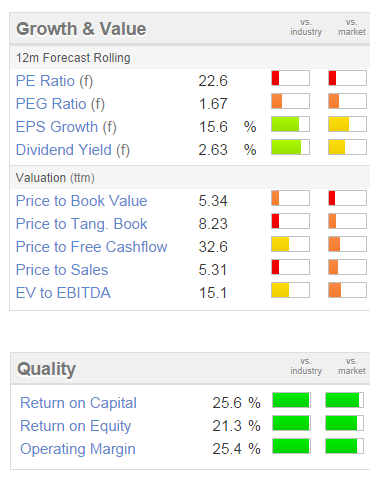
The trouble is, it's expensive on a PER basis, especially considering there doesn't seem to be much growth coming through, looking at today's results for the year ended 30 Jun 2014.
Turnover is up only 2.7% to $42.6m (NB. reporting in US dollars), and operating profit is up from $10.5m to $11.2m. That pedestrian growth is rather hard to reconcile with a PER over 20.
Outlook - sounds reasonable;
Investments in the business mean we have the people and the expertise in place to take us through the next stage of growth, building on our record sales performance. We have had a strong start to the current year, carrying on the momentum from the previous year and are confident we have the platform to deliver ongoing increased stakeholder value.
Balance Sheet - very strong, with plenty of cash.
Dividends - reasonable, with a yield of about 2.6%.
My opinion - if there was stronger growth reported, then I would buy some. I'm intrigued by the obvious strategic value of the business, so it might be one to pay a high price for, with the eventual outcome being possibly a highly priced takeover bid? Interesting.
Thalassa Hldg (LON:THAL) - the shares have plunged another 27% to 130p this morning on publication of lacklustre interim results. Disclosure of problems with some Russian contracts sounds like the trigger for the further move down, which looks serious - $10m of budgeted turnover for H2 won't happen. Given that H1 saw total turnover of $9.3m, then that's a massive chunk of H2 turnover now not happening. The reason is the sanctions imposed on Russia due to its activities in Crimea & Ukraine.
This all sounds a bit of a mess. However, I'm wondering if value might be appearing here, given the very strong asset backing, including plenty of cash.
I've not got time to look into it right now, but it's something I might return to when time permits, and ask around in my network to see what people with a better understanding of this sector think about the situation here.
Just thought I'd flag it to readers as something potentially interesting to have a look at, if you have the time & inclination. Your comments are as always, most welcome in the comments section below.
Got to dash, for this meeting with Spaceandpeople (LON:SAL). I shall report back my thoughts later, or maybe tomorrow?
Mello2014
Regulars will know that I am a keen supporter of David Stredder's "Mello" investor evenings, which he arranges for investors to meet many interesting company managements, and to network amongst ourselves. David has single-handedly built a wonderful network of investors, which has greatly enriched my life both through swapping investing ideas, but also making some terrific friends.
Anyway, David has decided to reinvent the market for investor shows, by launching his own one - where the companies presenting are interesting value & growth companies, not the usual collection of blue sky resource stocks.
The event is being held in Derby, over 3 days in Nov 2014, so not long now. Tickets have just gone on sale, and I am sure will sell out. Derby is only 1h 25m from London by train, and of course is much more accessible to all the investors in the North, who are normally frustrated by such events usually being held in London.
Stockopedia & myself will be there too, plus loads of superb speakers - not the usual culprits, but highly successful fund managers & millionaire self-made investors, hand-picked by David to share their wisdom with us all.
The event website has just gone live,and is here. It's the first such event (as far as I know) that has been organised for investors by a highly successful investor, rather than being done for commercial gain. So it's going to be fantastic. Hope to see you there.
Running late, got to dash.
Regards, Paul.
(of the companies mentioned today, Paul has a long position in PTCM.
A fund management company to which Paul provides small cap research ideas, has long positions in PTCM & THAL)
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

12 comments
Hi Gray
Just had a quick search for that.
This article:
http://www.investegate.co.uk/thalassa-holdings/rns/share-dealings/201401081515022171X/
Says that:
"... the THAL Discretionary Trust ... holds the shares for the benefit of the Company's employees, directors and consultants."
There's more info at the link above.
Regards Thalassa (£THAL), I just had a look over their accounts. Everything looked good until I got to their current assets. There, it states that they have now loaned over $7m to an entity named the Thalassa Discretionary fund. In the notes, it is written 'The THAL Discretionary Trust is a trust, independent of Thalassa, established for the benefit of individuals or parties to whom the Trustees wish to make awards at their discretion.'
In the last three interim periods (18 months), loans to this entity have risen from $0.7m to $1.8m, to now over $7m. In the notes, they state that:
On January 8 2014, the Trust acquired:
• 1,000,000 ordinary shares in the Company at £2.70 per share,
• 1,078,667 ordinary shares in the Company at £0.264 per share.
The average price of these purchases is about 145p, which means they are now loss making. But in reality, that doesn't matter. The question is, what the heck is the purpose of this fund, and why has it now been loaned $7m? For a company Thalassa's size, it seems beyond belief. They set up a fund, loan it near on $5m (just this year) to purchase shares in themselves? Are they going to continue doing this, and if so, why? Baffling times. Though, just to note, I've only just given the results a quick glance over, so I may be missing something obvious...
Hi Paul,
How did your lunch go?
Kind regards
Guy
Hi Paul,
I‘m regular reader of the small caps report but probably this is my first poste here.
Before I start, I would like to point out Thalassa Hldg (LON:THAL) is another of Simon Thompsons from IC tips...
I had a brief look at the company it does look fairly attractive on the surface but when you delve more into what is reported no longer so sure about it. First of all there is uncertainty of what will H2 will look like, also in worst case scenario there could be $4.1m hit in H2 if they cannot recover receivables from Russian partner and repatriation costs for equipment.
However, my biggest concern is that P&L does not reflect actual director pay, according to Directors report, pay received by directors is very minimal and is passed as consultancy cost, so Thal is avoiding employer NI but this is tiny worry, especially considering that directors have set up trust to top up their income. There is asset of $7.3m in P&L related to loan to the trust at 3% interest per annum. Although accounting treatment might be correct but, in effect this is Directors pay which bypasses P&L. I don’t think this money will ever be recovered by the company and P&L will be continue to be flattered by the non-existing interest income although it is immaterial in grand scheme of things, so I would write this off completely.
In H1 Thal contributed almost $5.4m to the trust, in FY 2013 $1.9m was contributed to the trust. In addition 1m shares were sold to the trust from treasury at 26.4p when share price at the time was well north of £2.
So overall I don’t think shareholders interest is top of the priority of existing directors. I might be too far too cautious but given outlook for oil and on going situation with Russia, company is not investable for me at this level. Perhaps at less than £1 I would consider a put.
Thalassa Hldg (LON:THAL) - in line with comments in the interims the house broker has lopped $10.3m off the full year forecast revenue to give $26.3m (H2 is generally stronger). They're predicting that'll deliver a PBT of $4.5m. THALs market cap at 132p is $54m, about 1.1 x tNAV which includes $21m of cash. This is a profitable, well capitalised business encountering some short term turbulence due to the situation in Russia but the long term growth case remains in place (IMO obviously).
Paul,
A general comment and a question. I am impressed by the speed with which you analyse news and I enjoy your honest comments so I can be more lazy and ignore most companies on which you make negative comments and look into those which are positive. The question is that you make comments on news which is not yet on Stockopedia so where do you get breaking news?
David
PS It is a lonely business being a private investor so I also appreciate your leads into ShareSoc, Mello etc. Keep it up.
Hi Paul,
Ref $CRW, found myself drawn to this one prior to reading your review, what intrested me was the reference to contracts signed over longer periods, (7 & 9 years) and 84% increase in contracts signed, with revenue expected to benefit future years.
So hopefully a company with a .number of potential routes upwards, if your thoughts on a potential takeover target are included.
many thanks for your reviews David
With respect to both comments above, yes I agree that the cashflow at Porta Communications (LON:PTCM) is negative - it's bound to be, as they are growing rapidly (some of their companies were start-ups remember), which inevitably will cause Debtors & WIP to rise considerable.
Turnover is annualising at about £32m, and the Debtors will include VAT remember, so that grosses up to £38.4m. Therefore £8.0m Debtors is 0.2083333 of turnover grossed up to include VAT. Multiply by 365, and you get Debtor Days of 76 days. A little higher than I would like (60 days is normal), but not horrendous by any means.
If you invest in a company which has the stated aim of rapid organic growth, then you expect working capital to increase, surely?
Regards, Paul.
Hi Paul on the basis of the recent Porta results I picked up a small holding. The price has continued to fall since. I can't see anything greatly wrong with the accounts but seems not to have pleased the market. Any further thoughts since your last review. Also to note this sale yesterday http://www.investegate.co.uk/porta-communications--ptcm-/rns/holding-s--in-company/201409301654450689T/. Cheers.
Hi Paul, interested in your view on what happened with THAL today, if you can squeeze it in.
Hi Paul - Re. PTCM. I liked the results this morning and took a small holding. But with the price dropping I re-examined the accounts in more detail. The only red flag I found this time was (as you point out) , net tangible assets are near zero. Otherwise looks fine.
However there is a large entry of -£3.5m , decrease in trade and other payables, which is pushing the net operating cash flow to -£2.3m. Looking at the balance sheet, under current liabilities, the 'trade and other payables' has hardly moved from 31/12/13 to 30/6/14.
Question: does it mean a decrease in operational activity such as reduced customer demand for their services? or is there an accruals element that is distorting the picture?
Thanks, Ram
Hi Paul,
Thanks for the comments. My concern is with cash flow which remains firmly negative. I know they have spent on acquisitions but that isn't going to stop! It looks to me that unless their organic growth is massive, the cash will continue to diminish and a fresh placing may be required. Any downturn in business will obviously exacerbate this.
UI've had my finger on the top up button all morning but the cash flow is pulling it back.
M.