Small Cap Value Report (17 Aug 2015) - SSTY, UBI

Good morning!
Not a great start to the week - my main PC has presented me with the blue screen of death again this morning, so there will be a long wait for that to gird its loins and actually start working. Luckily I have a backup PC.
There are a few things which have caught my eye this morning;
Safestay (LON:SSTY)
Share price: 61.4p
No. shares: 19.2m + 15.1m Placing = 34.3m (+ up to 1.6m in Open Offer)
Market cap: £11.8m pre-Placing, £21.1m post-Placing (but pre-OO)
(at the time of writing, I hold shares in this company)
Placing, acquisition & restoration on AIM - shares in this growing hostel company were suspended on 22 Jul 2015, when an announcement was made indicating that the company was seeking to raise £15m in equity (thus more than doubling its market cap), and a new £8.5m loan, in order to buy a hostel in Milan (£6.3m) and Edinburgh (£14.9m).
The shares have come back from suspension this morning, so can be traded again. Details of the fundraising are given, as follows;
Placing of 15,071,452 shares at 62p (a discount of about 7p, or about 10% from the price when they were suspended) to raise £9.34m gross, and £8.24m after expenses. What?! They've paid £1.1m in expenses - that's crazy - that's a ridiculously high 11.8% of the money raised which has gone already - to advisers. Nice work if you can get it, but a lousy deal for the investors who put the money in, and a lousy deal for existing shareholders, as it effectively means we're being diluted at 54.7p, not 62p.
If the company is going to do more fundraisings, it urgently needs to find a cheaper way of doing them, by e.g. making a list of people what want to invest in the next Placing, and getting a cheaper adviser to contact them direct next time. I can't see why the costs would be more than £0.1m, let alone £1.1m, just to arrange a few meetings, and draw up some documents, which is basically all that a Placing involves. It's meant to be a quick & simple (and cheap) way to raise money, so it would be interesting to find out what's gone wrong here, that management have allowed such staggering adviser costs to accrue. It signals to me that management here are not very shrewd, which is worrying for a property company.
Open Offer (1 for 12) - I'm very pleased to see that existing shareholders are being offered a chance to participate in the fundraising too, with 1.6m shares being offered in this way, on the basis of 1 new share for every 12 already held.
Given the high level of dilution from the Placing, a 1 for 12 Open Offer looks a bit stingy, but I suppose shareholders can buy more in the market if they wish, as the share price has fallen down to the Placing price. Therefore take-up in the Open Offer might be quite limited, although it does enable medium sized shareholders to top up their holdings, who might otherwise struggle to buy in size in the market, as the shares are illiquid.
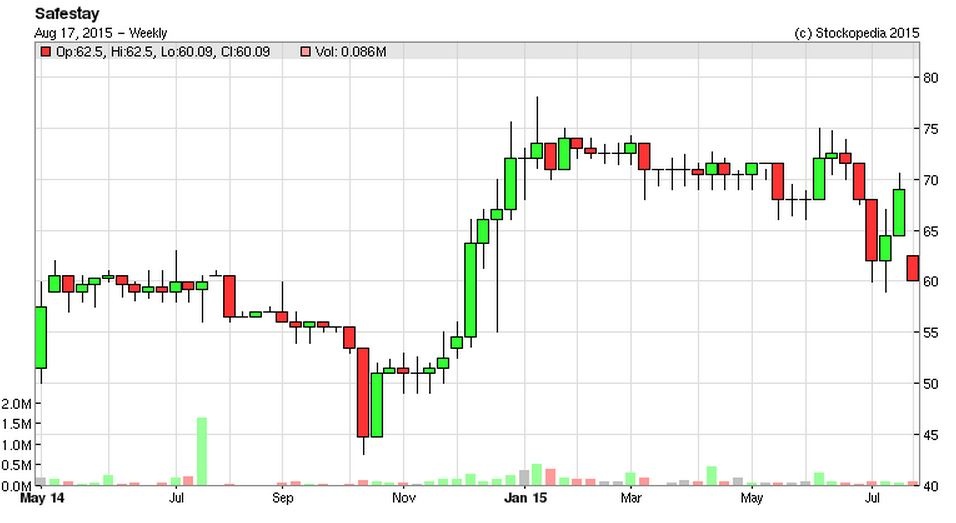
See how the latest fundraising has taken the share price back to where it was a year ago:
Milan hostel - this proposed purchase has been dropped, as investors didn't like the idea. That seems sensible to me - much better that Safestay remains UK focused whilst it's small. Europe can be tackled later, once the brand is widely established in the UK. Also, Italy would not have been a good choice, due to difficulties in managing it remotely, and the structural problems & low growth in Italy.
Edinburgh hostel - this is going ahead still, and is a big property, with 132 rooms and up to 615 beds. It has a 12 year contract with Edinburgh University to provide student accommodation in term time, and then those rooms become additional hostel rooms in the student vacations. That sounds a good business model, although I imagine maintenance capex would be quite high, with the pummeling that student parties will give to the fixtures & fittings!
This hostel generated turnover of £2.7m and EBITDA of £1.0m in calendar 2014, which to my mind puts a question mark over the wisdom of paying £14.9m for it. Once capex is taken into account, and the costs/hassle of managing it, I'm dubious whether this transaction is good for shareholders. If trading improves substantially once it has been re-branded & refreshed, then fine, but on the existing performance I'd say it looks a marginal decision.
Trading update - details on current trading are given in note 10 of today's announcement.
The company has added extra management, and warns that this will impact profit in calendar 2015. However, it started charging for breakfast in Jun 2015 at existing sites, which will have a positive impact on profit. These effects are not quantified.
Elephant & Castle is trading well, with EBITDA up 20% on turnover up 5.5%.
York is still trading behind expectations, so the general manager is being replaced, and more sales & marketing resource is being made available.
Holland Park is due to open shortly. Initial enquiries are encouraging. This looks a lovely building, and I might try it out myself at some point.
Head Office - further additions to staff are planned for H2 of 2015.
My opinion - my finger is hovering over the sell button, for the small amount of shares I currently hold in this company. It's a terrific concept - stylish & comfortable hostel accommodation, but my worry is the central costs seem to be escalating as more hostels are added, thus diluting or negating the operational gearing of more sites.
That said, once the brand is more established in multiple locations, it may add value to each site that is bought.
Growth is proving highly dilutive for existing shareholders, and inevitably more shares will need to be issued for additional sites, so it's difficult to see how the shares can gain much traction, when up against a headwind of repeated discounted Placings.
My other worry about the hotels sector generally is that AirBnB is becoming much more widely used. I've asked a few people in my network, and a lot of people are using it, very successfully, to find affordable accommodation anywhere in the world, often at a fraction of the price of hotel accommodation. So that's bound to be an increasing headwind for hotels - maybe not significant at the moment, but I could see it building to something very large, in time.
Hostels are different, in that they are often large groups, e.g. school trips, so AirBnB would not be appropriate for them, so SafeStay has a good niche, and I like the branding & design of their hostels. So on balance, I'll probably sit tight with my SafeStay shares, and see how things progress over the next year.
Ubisense (LON:UBI)
Share price: 107.1p (down 3.5% today)
No. shares: 36.3m
Market cap: £38.9m
Interim results to 30 Jun 2015 - this company warned on profits on 30 Apr 2015, and again on 3 Jul 2015 (my report is here) so poor figures were expected for H1, hence why the share price is only down 3.5%.
However, there's no disguising the fact that these are dreadful results. Turnover has dropped heavily, from £17.3m in H1 last time, to £10.4m this time, and an operating loss of £2.0m last time in H1 has become a huge loss of £7.3m this time.
A somewhat better picture can be painted if you start stripping out costs that you are happy to ignore, e.g. £1.9m in non-recurring costs (mainly restructuring costs, and exiting from Korea & Philippines). So adjusted EBITDA is negative, at -£3.65m.
Balance sheet - Net assets has barely changed, at £21.0m (£21.1m a year ago), but in that time the company has increased share capital by £9.6m, so it's actually burning a lot of cash, and I wonder if investors will be prepared to keep pouring money into this company?
Ubisense still has bank debt. A loss-making company should not have bank debt - it makes things too risky. At the moment cash balances exceed bank debt, but continued cash burn is likely to erode that safety margin.
Debtors looks high, at £10.1m, which is almost the entire turnover for H1. I'd want to know what has caused that, so for the moment it's a red flag.
Restructuring - this has reduced the cost base by £2m p.a., which based on these numbers doesn't look enough.
Contract slippage is blamed for the disappointing H1 results.
Sales pipeline sounds encouraging, but with such poor H1 results, I'm not sure how much reliance should be placed on this optimism?
The good pipeline of Solutions opportunities to be closed in the second half, including contracts that have slipped from the first half, together with a strategic focus on accelerating partner channel development to expand business scale and reach, give confidence on the full year outturn
Outlook - at this stage, the company is making reassuring noises, but they have to really, don't they?
Ubisense has started the second half of 2015 with a lower cost base and a refreshed market focus through the RTLS and Geospatial business lines, and a commitment to complete the market exits outlined. The Group has entirely assessed its order pipeline, including the Solutions contracts which slipped from the first half, and is comfortable with the level and deliverability of this pipeline. This together with the decisive action taken on costs, the benefit of which will be felt in the second half, means that the Group is confident it is on track to deliver full year results in line with the Board's expectations, notwithstanding the disappointing first half performance.
My opinion - I don't share management's confidence that they will deliver the full year results, given the poor track record. I think the market should brace itself for the possibility of another profit warning in the autumn, which would then probably mean another cash call in 2016.
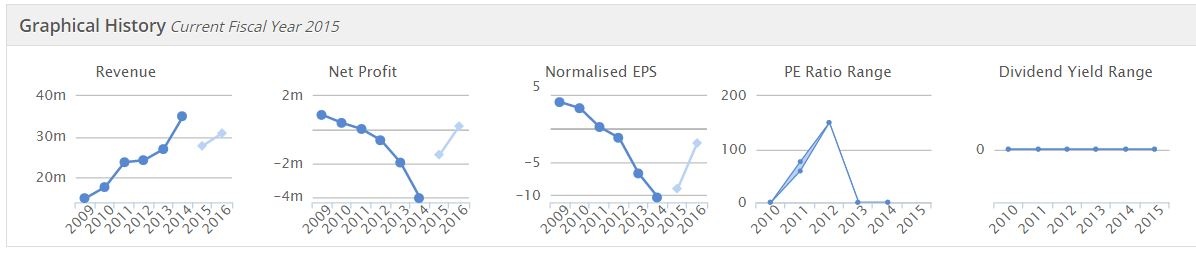
Overall then, I wish them well, and hope they succeed, but it's not something I want to risk my money punting on. Forecasts show a recovery, but look at the historic track record of constantly declining profits (into losses) and worsening EPS - see the Stockopedia graphics below.
With dreadful interim results in the bag now, it looks a tall order to expect even half-decent full year results.
I think this share could be a disaster waiting to happen, so needs to be viewed as extremely high risk in my opinion.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

17 comments
https://www.safestay.com/admission-document-and-circulars.html
I've skimmed the circular for this SSTY deal.
Seems as if the university is liable for repairs for the student rooms. Capex at least for the last 3 years has been small. The university deal also increases with RPI every year. The property valuation report reckons underlying sales at the Edinburgh site should be £2.85m and produce an operating profit of £1.1m. Margins at 38% are in line with the Elephant & Castle site. With such high margins though, I am not sure where and how any extra economies of scale can accrue. The new CEO was a director of the firm that used to run the Edinburgh site, so he should know what he is getting into. The extra central costs will include his £120k wage.
Downside for me with SSTY is that with new sites involving large sums and placings, a rollout could be slow and dilutive, and self-funding could take some time to occur.
Hi TMFMayn,
Good work, much appreciated!
I've decided to hold onto my Safestay (LON:SSTY) shares (in my long-term portfolio, and only a very small position), but I agree with your conclusion that this roll-out is proving both slow & dilutive. Hmmm, maybe I should sell then? Drat, I'm back to square one lol!
Regards, Paul.
Hi bobo,
I don't know about the investment case for SSTY, but as a side topic I must take issue with your comments on Milan!
As a global tourist and business destination, Milan is huge compared to both Edinburgh and York
If Stockopedia launched a travel website, 'trip-dyor' perhaps (the name might need more work) Milan would be on all the screens.
http://blog.euromonitor.com/2015/01/top-100-city-destinations-ranking.html
Milan was 24th most visited City in the world last year, nestling between Las Vegas and Barcelona :)
"Milan, hardly a third level tourist attraction let alone in line with London, Edinburgh or even York.
Looks like they've been taken for a ride by their advisors and the people selling them places. The trick about hotels or hostels is position and then occupancy. How will Milan satisfy that?"
http://blog.euromonitor.com/2015/01/top-100-city-destinations-ranking.html
I spoke to some friends running a hostel. The main threat is not AirBnB, but a couple of years ago there was a worry about the rise of couchsurfing.com
Hostels are all about location and good management, then recruiting the right staff with a good attitude and keeping them. Then guests write up good reviews and give them good rankings on hostelworld.com (the booking.com of hostels). But most of the managements I have spoken to who run hostels don't think the business model can scale across cities. People are trying it "St Christophers" and "Wombats" are in several european cities, but my mates who run The Circus are skeptical that hostels scale, and instead are expanding vertically into hotels and serviced apartments.
https://www.circus-berlin.de/
I sold SSTY a few months ago as it levelled off and aspirations seemed to high. Now dividing their time across two countries is nonsense at this stage of development, good thing they were talked out of it; casts a few queries about management & their plans; may be someone there is Italian and wanted expense paid trips home.
Thanks for your detailed response Paul.
Good point about the insurance float.
I'll stay out for now.
Milan, hardly a third level tourist attraction let alone in line with London, Edinburgh or even York.
Looks like they've been taken for a ride by their advisors and the people selling them places. The trick about hotels or hostels is position and then occupancy. How will Milan satisfy that?
I find AirBnb a mixed blessing as a guest, dealing with amateurs is not so fun when anything goes wrong, and the platform couldn't care less.
For hosts, I've heard of some predictable stories of people enticed by the gross takings discovering after a while that running a 1-unit hotel with no economies of scale, accelerated wear and tear, dealing with the rare but painful problem guests, possible tensions with neighbours not amused by careless tourists (who don't have reputations to uphold) misbehaving, etc is not worth the hassle, or worth it at a price closer to the organised competition.
I have had a very good experience with AirBnB as well, but i think they are aimed at a different set of travelers.
Mainly singles or couples, Safestay is good for all group sizes and the costs are about a third lower(or more) per person. Based on the rates for the Elephant and Castle site and an AirBnB flat for 2 in the same area.
A lot of AirBnB places also ask for a security deposit which many hostel travelers may not have.
I don't think they will encroach each other, I see them as two different styles of accommodation.
PaulB
Paul, I'm surprised that the Edinburgh property seems to have students apparently sharing rooms, four or five to a room. I can't see much work getting done if that is the case. The revenue (2.7m / 615) seems to work out at about 4,500 pounds per student, assuming 100% occupancy, which is not that much less than student accommodation in individual rooms that I'm aware of in English universities, although there ought also to be some revenues from events such as the Edinburgh Festival. Although I'm not au fait with the situation in Edinburgh, this one puzzles me as I know it is far more usual to have at least an individual bedroom. Here's an example of individual student accommodation in Edinburgh, slightly more expensive but better for study, almost certainly
https://www.student.com/uk/edinburgh/potterrow
There may be perhaps a shortage of student accommodation in Edinburgh but I'd expect students to want individual rooms or for this to become a requirement. If this comes about, would this property be a viable investment since it would then presumably have to become a year-round hostel? As it is, it already looks marginal, I agree with you.
As for AirBnB, my experience has also been very positive and I can see this as squeezing Safestay's business model.
Hi Jane,
To clarify, from today's annoucement from Safestay (LON:SSTY)
"The Edinburgh Hostel, which was converted in 2001 and extended in 2007, is a 132 room/615 bed hostel and student accommodation scheme in a prime location in the heart of the Old Town, close to the Royal Mile. It has 272 beds available for hostel use throughout the year. In addition, 81 en-suite bedrooms, which are leased to the University of Edinburgh for 39 weeks of the year (September-May), are available over the peak tourist period of the summer months for hostel use, providing an additional 343 beds, giving a maximum capacity as a hostel of 615 beds. The lease to Edinburgh University has 12 years left to run and generates £312,000 per year in rent. The property, which comprises 8 floors, has a bar and lounge with an outside courtyard and split level terrace. In July 2015, the Edinburgh Hostel was independently valued at £14.8 million."
I think AirBnB is likely to have less impact on SafeStay than on hotels, because a lot of SafeStay's business is school trips - where there are too many individual people to be able to book a suitable AirBnB site. Although AirBnB is likely to take some of the other customers away.
SafeStay is very cheap too. So I think overall AirBnB is more of a threat to budget hotels, rather than hostels. Arguably the market is so huge, that there's probably plenty of room for both, and cheaper accommodation stimulates more demand from people who would otherwise not visit.
Regards, Paul.
AirBnb is a website driven accommodation finder. You register with them if you have accommodation and they market your property for you, handle the payment and pass the balance (payment less around 3%) to you as the landlord. Alternatively people looking for accommodation look on the site to find a place to stay and when booking pay a fee plus rent to AirBnb who pass it on as above. Works well for holiday accommodation not convinced it runs for longer term tenants. Very useful to landlords with short stay because handles marketing and admin cost and they can leave references on tenants so useful check. So they take both sides. As a user I love it.
Hi Paul
Came across Safeland (SAF) last Thurs thinking it was the co you wrote about some time back, but I couldn't find your article. Now I know why!
Anyways, opened a position as it ticked enough boxes fundamentally, borrowing is a bit on the high side but hopefully will improve.
Comparing the 2 companies I felt SAF more investable, any comments?
Ady.............the guy across the table at the Peterbro dinner
My other worry about the hotels sector generally is ... AirBnB ...
imo, in the short term, AirBnB will have a fairly big negative impact on hotels.
in the long term, once a few bad experiences have been had, AirBnB rooms will be regulated like hotel rooms (all the insurance, fire safety, inspections regulations etc hotels have to have)
Otherwise lots of hotels will become AirBnB rooms in bulk.
Hi Paul,
For the exceptionally thick - please explain AirBnB.
thanks
John
Hi Paul,
Have you ever considered Gable Holdings (GAH)?
Small cap insurer that has fallen into value territory this year.
Trading update out today.
Many thanks.
Hi joeydisco (great username by the way!),
I don't cover the insurance sector, as there are only so many companies I can personally cover, and so I exclude particular sectors where I have little sector knowledge, and where I've failed to make money in the past - e.g. resources, financials, insurance, pharmaceuticals, biotech, etc.
I also usually exclude most property companies, as they take too long to research properly.
Excluding those sectors, and setting a minimum market cap level of about £10m (although I will go below if a company looks interesting, on an ad hoc basis), results in around 500 companies for me to report on, which is more than enough!
Good luck with Gable Holdings Inc (LON:GAH). Looking at its StockReport, the market clearly doesn't believe the forecasts, as the fwd PER if only 2.66! Also I note that the broker forecasts have been continuously downgraded in the last year, falling from c.10p EPS to c.5p EPS.
Having a look at today's announcement, it sounds positive - good growth, and claims experience in line with expectations. Also confirms that it won't be raising more equity. Sounds promising, so might be worth doing some further research on this one.
Having a quick look at the 2014 & 2013 results, it seems to have lurched from a profit into a loss.
Also the admin costs look very high in relation to the premiums written.
Only £27.3m net equity. I can't see where the insurance float is being invested - that's where insurance companies are meant to make their profits - on the investment gains from the float.
All the float seems to be in debtors & cash, which seems odd.
With profit so volatile, how do you value it?
Might be a nice speculation, but it's not for me. The mkt cap does look low though, could be a good punt at 20p, who knows?
Regards, Paul.