Small Cap Value Report (17 Nov 2016) - CRE, NXR, AVS

Good morning!
I put on a late surge yesterday evening, and wrote several more sections, so here is the link for yesterday's full report. Please note in particular the link for attending a presentation being given by an excellent growth company Ab Dynamics (LON:ABDP) .
Profit warnings webinar
If you missed Ed's brilliant webinar yesterday, on profit warnings, here is the video link, and the eBook link.
This project has definitely made me think hard about avoiding falling knives in the future, so many thanks to the team at Stockopedia HQ that did all the hard work for us.
Creston (LON:CRE)
Recommended cash offer - the largest shareholder (28%) in this marketing group has launched a bid to take it private. The offer is 125p per share in cash + 1.42p dividend. This looks opportunistic to me, and is far from generous. It represents a multiple of only about 10 times earnings. The premium is about 35%, which is in the standard ballpark for many takeover bids.
Quite good interim results are also announced today.
Overall I think shareholders might understandably feel rather disappointed that the company is being pinched from them at a lowly valuation. On the other hand, it is a 35% uplift in price, which might have taken a while to be achieved without a takeover bid. So a bird in the hand, and all that.
Shareholders will also lose the nice flow of future dividends, as this share came with an attractive & growing dividend yield, which was about 5% as of last night. Although as stated in the bid announcement, market conditions are uncertain for marketing companies at the moment.
Norcros (LON:NXR)
Share price: 147p (down 0.5% today)
No. shares: 61.3m
Market cap: £90.1m
(at the time of writing, I hold a long position in this share)
Interim results, 6 months to 30 Sep 2016 - as you can see below, the financial highlights look pleasing;

Outlook comments are also positive;
With our strong brands, leading market positions and continued self-help initiatives focused on market share gain the Group is well positioned to make further progress.
Given the encouraging performance in the first half of the year, the Board remains confident that the Group will achieve underlying operating profit in line with its expectations for the year to 31 March 2017.
Pension deficit - as expected, the pension deficit has ballooned due to historically low interest rates on bonds. Norcros is burdened with a huge pension scheme, which we discussed at length in my report, and the subsequent very interesting reader comments here on 11 Oct 2016.
This is what Norcros says today about its pension deficit;
The gross deficit relating to our UK defined benefit pension scheme as calculated under IAS 19R has increased from £55.7m at 31 March 2016 to £97.8m at 30 September 2016.
This increase was principally a result of a 1.3% reduction in the discount rate to 2.25% (31 March 2016: 3.55%) reflecting lower bond yields following the outcome of the EU referendum.
The calculation of the deficit is particularly sensitive to the movement in bond yields which are at historic low levels.
It is estimated that a 0.1% increase in bond yields would reduce the deficit by circa £6.0m.
Whilst the increase in the deficit has been significant it has not impacted the ultimate holding company, Norcros plc, which has a strong balance sheet and significant distributable reserves, in excess of £100m at 31 March 2016.
Following completion of the 2015 triennial actuarial valuation and the subsequent agreement with the Trustee of the recovery plan, the Company continues to pay £2.5m per annum plus CPI into the scheme.
On paper it's a huge problem, but in cashflow terms, it's fine (at the moment), with overpayments of £2.5m p.a. being easily affordable. The company is paying generous divis yielding 5%, plus surplus cashflow (supplemented with debt) for acquisitions.
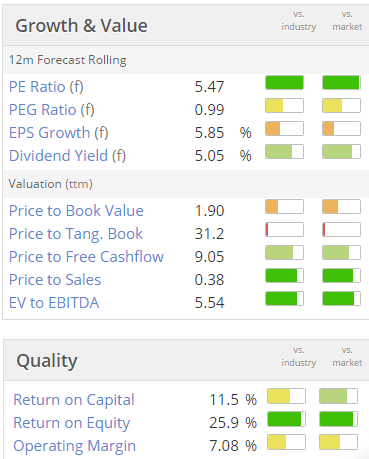
As a reader pointed out in October, the risk is that the pension fund trustees might require a significant increase in overpayments next time it's up for negotiation. My view is that it's already in the share price in spades - a PER of about 5.5 is over-compensating in my view for what is a manageable problem.
Even in a downside scenario, overpayments might rise to say £5m p.a., which again the company could easily afford. So to me it's not a deal breaker. Others may not share my sanguine view though.
The other thing to consider is that bond yields have risen sharply in the last few weeks (post the 30 Sep 2016 period end). I spoke to one company last week who told me that their pension deficit had shrunk dramatically in October, due to rising bond yields.
So if you think we're entering a period of higher interest rates, then Norcros shares could be in a good position to benefit, as its pension deficit should end up rapidly declining as bond yields rise.
Dividends - the interim divi is up 9.1% to 2.4p. In the past the final divi has been twice the interim divi, which implies 7.2p full year divis - which is an attractive yield of 4.9%.
Balance sheet - is obviously dominated by the pension deficit. Apart from that, it looks fine to me, with a sound working capital position. There's some debt, but at a manageable level relative to cashflow/profits, in my view.
My opinion - as mentioned before, I'm happy to sit tight and collect in the generous divis.
I feel the market is ignoring the successful buy & build which is taking place here, with good acquisitions having been made so far. The pension deficit is clearly a big issue, but it's manageable. In my view the share price over-discounts the pension issue, but that's just one person's opinion, so please feel free to disagree.
I've chickened out from buying any more as yet, but my finger is hovering over the buy button. I might wait a few weeks, to see if the share sells off again, as it sometimes does.
Here's are the valuation & quality graphics;
Avesco (LON:AVS)
Agreed takeover bid at 650p per share - this is a blockbuster deal - at a whopping 125% premium to yesterday's closing share price.
As regulars here know, this is one of my favourite shares, and has been for several years - my original purchases being around the 100p level.
I won't regurgitate all the reasons for why I like this share again, but here's a link to the archive of SCVRs which mention Avesco, increasingly positively over time.
It's great to read the comments section below, and hear that some readers have also benefited from this outstanding result. Happy days!
Noteworthy too that Avesco has had a very high StockRank (currently 97) for quite a while. It was a bit of an overlooked gem for a long time. Anyway, well done everyone who holds! It looks a done deal, so personally I'll be holding out for the full 650p.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

67 comments
There's a factual error in the Norcros comments. The payments to the pension scheme are not a flat £2.5m pa but £2.5m indexed with the CPI inflation index. This may not materially influence the analysis, but 5% CPI would mean the payment was £2.625m, not £2.5m.
(Almost certainly there will be a 0% floor on the indexation too, so the payments can only be higher than £2.5m, not lower).
The recent sharp decline in Topps Tiles (LON:TPT) (which I am long) is probably not a great read across to Norcros (LON:NXR) 's UK business (ex SA). admittedly, there are real differences with Nocros doing a lot of manufacturing, having a wider product range and selling into new builds - but there still should be considerable end market similarities. Topps seems to have passed the April to Sep period with reasonable like for like growth but the market seems worried about the outlook and the fx impact for 2017. Full year results for Topps Tiles (LON:TPT) come out on 29 Nov - while this year's results have been effectively pre-announced - the focus will be on current trading and outlook. £NXR's UK business, if I understand correctly, had actually a 5% decline in LFL sales (April to Sep), with poor performance at Triton and Johnson Tiles. Headline UK revenues only grew because of acquisitions (Croydex and Abode).
Over the moon.
Many thanks to the team for bringing this stock (£AVS) to my attention.
Double thumbs up to Paul as well.
I've been fortunate to have had two stocks subject to takeovers in the last few months, AVS and PFL. Thank you Paul for bringing AVS to my attention. But a cautionary note to AVS holders: I sold my PFL stake on the original takeover announcement at 164p but 6 weeks later there was another bidder at 184 and the shares then rose to 194. Its possible the AVS is a done deal but its also possible that another bidder may emerge.
Hi fwyburd,
I was also in Premier Farnell (LON:PFL) (as well as Avesco (LON:AVS) ). It's been quite a good year for M&A activity as I've also seen portfolio held takeovers of Home Retail (LON:HOME) , Cable & Wireless Communications (LON:CWC) , Journey (LON:JNY) , Hydro International (LON:HYD) , ARM Holdings (LON:ARM) £BPI , SkyePharma (LON:SKP) and Lifeline Scientific Inc (LON:LSI) .I suspect this is the result of cash burning a hole in the pockets of profitable companies, very cheap long term debt for those with the capacity to borrow and favourable currency movements (i.e. £ devaluation) that is making UK Plc relatively cheaper, especially where the target company has substantial overseas revenues in strong foreign currencies.
On the specifics of the Premier Farnell bid, this came following a profit warning the previous year and disposal of a chunky subsidiary making it a cheap and clean acquisition with a strong market position. At the time of the first bid, I recall the share price went up to and above the bid suggesting the market thought a second bid might come along (and then went above the second bid anticipating an even higher counter offer). In this case, the 650p offer seems to be at a knock out 125%+ premium such that a second offer seems unlikely. I think this is borne out by the market bid for Avesco (LON:AVS) being at the 630p level. This said, you never know what might come along ...
Best,
Gus.
No I didn't invest in Avesco (LON:AVS) but hearty congrats to the fortunate bunch who did !!! Well done.
Paul,
Can I add my thanks re AVS? One point worth noting: congrats to the advisers, partic finnCap, as there appears to have been no pre-deal leakage. The price just went ballistic yesterday.
G5
iwright7
one angle might be to look at other AIM companies (i focus on AIM) that do a lot or most of their business in the US, have a strong niche or are a market leader, and where a US company might wish to buy it. SOM is one example in my view.
It is approx 17% cheaper for US companies to buy UK listed companies due to the current USD/GBP rate and debt is still very cheap of course if needed to fund the purchase.
for the record, I'm a holder in SOM and like the company, its niche market and management a great deal!
good luck!
regards
dom
dom,
Yes Somero Enterprises Inc (LON:SOM) is my now my 3rd biggest holding and I see its up again this morning - Still too cheap I think. I need another pick though - Too many eggs in one basket and all that. Ian
Many thanks Paul, I'm not sure words can express how happy I was when I woke up this morning and logged into my brokerage account to see a 195% profit on AVS.
I will sell my Avesco (LON:AVS) today after 9.30am when the markets are in full swing. It does seem that AVS was a bit of a special situation: cheap, good momentum and quality. The other special part was the CT division which almost certainly would have be worth a lot more as a standalone operation, rather than as part of a bigger group.
So I now thinking, "Where do I invest the AVS cash?" and are there other AVS type, high scoring SR companies whose share price has been held back by one or 2 poorer performing divisions? Ideas please? Ian
is the general consensus here that it's a done deal and a competitor bid is unlikely? I'm considering selling into the market now but would appreciate comments either way. I'm a 'bird in the hand type of guy' by the way. I've never been in a takeover situation so this is all new to me.
approx when would we likely see the payment if all goes through ok and one holds unti lthe end?
Thanks in advance for any assitance here.
Regards
Dom
For anyone wondering you can sell all you like at 6.36 in the market which strikes me as very reasonable value
Paul,
Many thanks for bring Avesco (LON:AVS) to my attention and more broadly for your excellent daily reports and also creating a lively, intelligent and engaged discussion forum. The thought and detail that goes into your reports continues to amaze and impress me. Thanks!
James
P.S. The SCVR social is a great idea, but not sure you'll be in a fit state for a week or so after with all the drinks delighted readers will be buying you! :) A risk worth taking perhaps!
P.P.S. Congratulations on your Fantasy Portfolio (Beam Me Up Scotty) delivering just over 100% gains in under 2 years!
Great work on AVS - my first purchase using the system, and what a result!! The next one now please? Happy days
Paul
I would like to add my own thanks on AVS - it was your post Brexit article on potential shares that flagged this one up to me. Your conviction ("this one should double", or along those lines), the Stockopedia rating and then Roland Head's analysis kept me from completely selling my holding after an already good gain before this event.
Is there a list of your other conviction shares? I know this is fraught with the danger in getting unwarranted brickbats, but what will I do with my AVS proceeds?
One other question, how does the share sale work in practice; will I find one day my shares have gone and I have cash in it's place?
Thanks again Paul (also for BOO and Globo-not)
I'm delighted with AVS & would like to kid myself that I'd have found It using the finally tuned nose of a truffle pig & my inmate Benjamin Graham like capacity for spotting value. In truth I read the Fountain Rd disposal RNS, clicked onto Stockopedia and SCVR and the result was already a great performer BEFORE the takeover RNS!!
So Paul many thanks you de man ..etc !
Many thanks Paul, you and one other blog sparked my interest in this share in the summer when I transferred my pension into a SIPP. I then did more research on the company, added several times after my original purchase as well as very recently on the significant dip. My portfolio went up over 10% yesterday!!!
PAUL, if you ever plan to come to beautiful Bali in Indonesia please get in touch as you have free accommodation!!
Best wishes
Dom
Doh! I nearly bought AVS at 205p a few months ago, but was dissauded due to the illiquidity of the shares and breadth of the spread. Actually I allowed my (execution only) broker to influence me. That was a five-figure mistake. I then resolved to buy on Monday this week and never got around to it. Well done all holders for being bothered to follow your instincts. Life is getting in the way of my investing at the moment!
Oh well
B2V
Reading through the comments on pensions I would make three points:
1) The interest rate debate focuses on the income side of the pension fund. But there is also an issue on the liabilities side - the amounts the fund will have to pay out in future is not fixed. Most final salary schemes have a built in inflation increase (admittedly usually with a limit - my pension is CPI capped at 2.5%). If inflation takes off next year as many are predicting that would be a double whammy for pension schemes - investment income going down and pension payments going up.
2) Pension schemes would normally try to match the life of the bonds they own with expected cash outflows so that most bonds would be held to redemption. If there is a perfect match (which I accept there never will be, but could be close) market yield changes would have no effect since the cash flows from a bond held to redemption is known (except in default).
3) On the plus side, pension schemes could have 30, 40 or more years to run, even after a scheme is closed and existing members ave reached retirement age, so any material favourable change (higher interest rates and lower inflation) could lead to wiping out the deficits, or even result in a surplus which could be payable back to the company at some point in the future. We may have to wait a ,long time!
Even if you have all the information about the pension scheme, there is still a huge amount of uncertainty in the macro-environment to make sensible financial analysis in the long term impossible. For me, any company that has a large DB pension scheme, even if it does not currently have a significant deficit, carries too much risk to invest in at the present time. I would not be surprised if we hear stories of some companies being unable to fund their pensions and their pension funds being unable to meet pension liabilities before too long. Just my tuppence worth.
Paul
At the risk of sounding like a broken record, I would like to add my tuppence worth in thanking you and the team at
Stockopedia for drawing my attention to Avesco. My first purchase was in June 2015 since when I have added a small number of shares to my holding on several occasions encouraged by the sea of green on the stock report, positive news flow and your commentary
As far as I can tell from the RNS it looks like a done deal. On the assumption it goes through the challenge for those fortunate enough to hold AVS is to re-invest the proceeds wisely.
Best wishes to all at Stockopedia
Joining the we love Paul day, nice one as they say. Dale is of course correct re norcros. It's a way off, couple of years, but the recent FT article about RR and the change in accounting standards coming with a new one on revenue may hit soem shares. RR are down nearly 10% this week just due to a revenue recognition change coming in two years time. Interested if anybody as sad as me and has any views on this?
Hi Paul
I just wanted to add my thanks re Avesco (LON:AVS), you were the spark! I bought in June, September and early October. Unfortunately (or fortunately!) I don't have the time to analyse the s@&t out of stocks and looking back at my notes I was simply attracted by the ROA etc figures, the divi growth and the fact that it on Stockopedia figures it was trading below book. That was enough for me.
Sitting here I contemplating the possibility that today I have had the best day in my short investing life but maybe also the best day I will ever have with my portfolio up 8.1% today. I never believed I would have a day like this. It is a great feeling, thank you Paul and Stockopedia so much.
Paul,"
To echo many others thanks for your work on AVS and your suggestion of a AVS / BOO p$%^ up sounds great.
Thanks again,
Peter
Want to echo everyone's thanks on Avesco - thanks so much Paul for bringing this to my attention! I bought in a couple of months ago and topped up on Tuesday - talk about well timed! Looking through my trading diary that's the single biggest portfolio rise in 1 day I've ever made so absolutely chuffed!
3 cheers for Mr Scott and Stockopedia!
I've only been a subscriber since September, with AVS being the first of a few purchases from Stockopedia's system (stockreports + discussion boards), and topped up this week, so this is great. This has paid for over a century of Stockopedia subscriptions !
As the bid looks 99+% definite to go ahead, I am currently weighing up whether to buy many more at the offer price (631 in the last half hour, looking at the trades ?). The 2% or so upside probably won't interest many, but this would be achieved in a short space of time (scheme expected to be in force by end of December). I was happy with the result last year when doing this in the takeover of the insurer Amlin, which I had held for 10 years.
Anyway, my thanks go to Paul Scott (SCVRs) and Roland Head (SIF article) for their analysis.
Regards
Geoff
I was taking a nap earlier, and my phone kept buzzing. So eventually I checked it, and it took me at least 5 minutes to take in the fantastic news of a 650p agreed cash bid for Avesco (LON:AVS) . That's a stunning result, and I'm thrilled that many readers have also gained from this announcement.
I think we should arrange a SCVR social at some point, and have a jolly old p@##-up in London, to celebrate BOO & AVS!
Regards, Paul.
That's a great idea! My Avesco profit is worth raising a glass to and I would never have bought them without reading your reports which have turned out to be absolutely spot on. I don't think you will be allowed to buy many of your own drinks that evening! Many thanks.
Paul
Just checking my portfolio at the end of the day Avesco (LON:AVS) ... holy #!#£!. That p@## is going to be messy :-) . Many thanks to you and the rest of Stocko team for the fantastic service.
John
Paul
Do you have any thoughts on the Tracsis (TRCS) results and in particular on the highlighting of adjusted results? I know you have reviewed TRCS before and interviewed the management.
Also can I make a general request for your CEO / CFO interviews. For any companies that use similar tactics to massage their results, could you ask them why and point out the negative impact on investors who may be misled or at least feel that they are being misled.
Thanks
Re: Tracsis (TRCS)
The thing that annoys me the most is that TRCS present only the impressive adjusted results at the top of the page. To find the statutory results and the reconciliation between the adjusted and the statutory results you need to scroll down several pages to the Consolidated Statement of Comprehensive Income. It does feel as if they are trying to pull the wool over our eyes - present the good stuff at the top and hope that many of the readers won't have the patience or the financial acumen to dig deeper.
There can be good reasons for highlighting adjusted results but always next to the statutory results and with a full explanation of the differences. And, as has already been said by someone else today, depreciation, share amortisation of intangible assets and depreciation are regular costs to the business. Share-based payment charges are just another form of salary payment.
When someone is trying to pull the wool over our eyes, that's the time to start questioning.
I'll echo all of this. It was the high StockRank (100, at one point, I believe) combined with Paul's analysis (he recently described it as the perfect share and flagged up the possibility of a buy out). I bought, and then kept adding. My portfolio has just leapt 10% in value. Many many thanks.
I concur. I found Avesco (LON:AVS) via a Stockopedia screen and found Paul Scott's write-ups a great addition to my own research, along with various other posts on this site. I had the added benefit of buying more earlier this week which is just extremely lucky timing, having decided to bring the cash I have been holding since pre-Brexit back into the market.
Thank you to all who have contributed to this success, especially Paul, Roland and Stockopedia!
Thank you super Pauly Scott for your great insight into Avesco!!!!
I can't fathom how pension scheme deficits can be so sensitive to bond yields. take nxr, even if we assume all the assets are in bonds, if bond rates fall .1% what does that really mean ? surely that means that the bonds they are holding have gone up in value, giving them a new higher value which means the rate on that price is a bit lower. Well yes, but you could sell those bonds at a higher price and invest in something else couldn't you ?
And we're all waiting for bond rates to rise, to eliminate the deficit, well I see how higher bond rates would make a start up pension fund cheaper to start , but if you're holding 100''s m in bonds, surely this means that the value of that asset is falling ? Sorry to be dim, I clearly don't understand this stuff.
You're focusing on the pension scheme's assets, but you also need to look at the other side of the balance sheet, namely the scheme's liabilities in the form of future payments to pensioners. The discount rate is used to calculate the present value of those liabilities, which in the case of Norcros were £501.5m at the end of September (note 12b of today's RNS). That's a massive figure in the context of Norcros' business activities, and that's why such small changes in bond yields (on which the discount rate is based) can produce such big swings in the deficit.
Paul,
Great Avesco (LON:AVS) call being undervalued. I took note and agreed and brought in @ 5% of my portfolio, so very pleasing. The best single day's gain I have ever had, so very many thanks. Several rounds of drinks due if we ever meet. Ian
Paul, thanks so much for your work on Avesco -- very grateful that you share such insightful work, for free!
Many thanks for championing AVS Paul. You were the one who first alerted me to the "hidden value" & I am pleased to say that I now have a sizeable holding.
In relation to the pension scheme deficit at Norcros, I think what is important is the discount rate which reflects the likely return on assets. This drives the value of the surplus / deficit reported in the accounts. Norcros has stated that each 0.1% increase in the discount will reduce the deficit by approximately £6m. Therefore a 1% increase in the discount rate will knock £60m off the deficit. the discount rate is driven by bond yields. Given that these are very low at the moment and unlikely to go much lower, I am expecting pension scheme deficits to reduce significantly in the future and in fact go into surplus at some point.
I am happy to hold Norcros as I personally do not feel the deficit can get much worse than it has been reported today
Yes good news about Avesco (LON:AVS) pleased I held on. 2nd takeover this week, the other one is Dee Valley (LON:DVW).
Was going to purchase AVS tomorrow after recent falls. Typical!!
As a by the way GRRRH.
got the free 2 week offer from stockopedia at weekend and decided to ook at and buy Avesco (LON:AVS).
Just seen the agreed massive premium offer
needless to say I not actioned my thoughts yet!!!!!!
As I said
GRRRH
Wow, now that's what I call a decent offer. Thanks to Paul & Stockopedia, the high stockrank combined with Paul's positive write ups convinced me to invest in AVS, feeling pretty happy today.
Wow, now that's what I call a decent offer. Thanks to Paul & Stockopedia, the high stockrank combined with Paul's positive write ups convinced me to invest in AVS, feeling pretty happy today.
What he said.
Thanks Paul.
Well done Paul re AVS
Bid crazy today - one just announced for Avesco (LON:AVS), 125% of current price.
Hi Lion Tamer -
Let's see if I can help you with this.
Yes, if a scheme is closed to new entrants, then the average age of the scheme members will go up each year. So for example depending on the mix of female pensioners to male pensioners, you might get a global life expectancy of say 83. Which means roughly the scheme will wind down totally in (83-77) 6 years time. All statistically speaking of course and based on a lots of assumptions.
Now as the scheme liabilities decrease each year (because you have less and less members alive) so do the scheme assets. Because you use the assets to pay for the pensions due. Theoretically if your assets are totally matched to your liabilities, then there will be no surplus or deficit in 6 years time, and everyone is happy. Of course life isn't like that.
This is an oversimplification which doesn't take account of the impact of longevity, interest rate changes, inflation, type of assets held, level of mismatching, etc, etc. and the assumptions made by the pension actuaries in modelling the future course of the scheme.
"Even in a downside scenario, overpayments might rise to say £5m p.a., which again the company could easily afford. So to me it's not a deal breaker. Others may not share my sanguine view though.."
The problem I see is that NXR's pension scheme has assets of £366m to fund annual benefits to scheme members of £24m with the help of cash contributions of less than £3m.
Compared to other schemes, the contributions are far too modest given the level of assets and benefits to be paid. Nearer £10m p.a. may be more like it. More here:
http://www.stockopedia.com/content/small-cap-value...
EDIT:
NXR's presentation on page 11:http://www.norcros.com/files/3314/7937/3221/Norcro...
A very useful chart of predicted future cash flows from the scheme. It suggests benefits to be paid will remain above £20m until about 2035.
If the company is responsible for making up the pension deficit, then is the company also in line to benefit from any surplus when the scheme finally finishes (all members deceased)?
If so, I'd be inclined to make the following quick and dirty observations:
Scheme assets £366m
Scheme annual benefits £24m and declining (slowly as noted above)
Norcros (LON:NXR) pre-contribution cashflow £16m
£366m assets should generate £8m yield pa. (2%) whilst maintaining asset value against inflation, giving company + pension scheme cashflow of £24m.
So even if all cashflow went into the pension, then essentially a £90m mkt cap company is eventually sitting on £366m of assets, assuming company cashflow is constant or growing.
Or is this over-simplistic?
EDIT: I should note that I have a small long position in Norcros (LON:NXR) (1 month SIPP contribution). I would consider adding if I could understand the pension issue more clearly.
With DB pension schemes that are part of LGPS schemes (local authorities and suchlike) any pension surplus is unlikely to be refundable to the contributor like Norcros (LON:NXR) on termination. However not knowing much about the type of scheme Norcros (LON:NXR) runs I am sure more knowledgeable among us can help here
Long on £nxr
Thanks for the Norcros (LON:NXR) write-up Paul. BRR media published a short video with the Norcros CEO this am covering the results. Thought this may be of interest to any holders of the stock: https://www.brrmedia.co.uk/broadcasts/582c8aa1210694df22704936/norcros-half-year-results
Regards,
Imran.
Thanks for the link Imran.
Does anyone understand pensions enough to help me with this ...
One point I missed in the RNS that was covered in the video was the average age of pension scheme members is 77, so I assume the pension scheme liabilities will be closing down a little each year from now on. I'm not sure if this information changes the outlook regarding the pension scheme liabilities, as I'd have assumed the actuaries would have factored this in?
Thanks
Re the Norcros pension scheme, what has been said before ( and repeated in the video) is that the average age of Pensioners in 77 but not the average age of the pension Scheme members which may make a difference to the view
In fact, I take the view that the shorter the life of the scheme, the more worrying a deficit is. There is a shorter time before the theoretical deficit becomes an actuality. If the scheme assets are stuffed with bonds ( as PF's are required to do in order to match assets and liabilities ) then an increase in interest rates reduces the value of the assets. So something that reduces the theoretical future liability actually increases the actual liabilities of a short life scheme. I think this is a follow on from Ramridge and TMFMayn above.
Of course I may be in error here and no doubt I will be quickly corrected
Still a long Norcros though !
Thanks Ramridge, thanks Housemartin2, also TMFMayn
I'm not sure I'm yet 100% comfortable that I fully know how the Norcros actuaries account for the age of the membership, although it makes sense that there is some matching of liabilities. Nevertheless I'm going to hold, firstly to keep interested while I see how this plays out and therefore learn what happens to a pension scheme as it starts to age, and secondly as I suspect in the Brexit/Trump era bond yields will sooner or later start to revert to norm (or at least partly to revert to norm).
Modest long position on NXR, (and AVS)
Another acquisition for Keywords Studios (LON:KWS) - up 3.6% and I've added a few more to my portfolio.
http://www.investegate.co.uk/keywords-studios-plc/rns/acquisition/201611170700124012P/
I metioned this yesterday, but it is worth doing it again. Anyone thinking about the potential impact of a pension deficit should read this:
http://www.investegate.co.uk/heath-samuel----38--sons--hsm-/rns/half-year-report/201611160800032636P/
Check out the last paragraph.
Most amusing narrative but in reality is also showing up his own ignorance
That deficit exists - it has to be paid - it could have been dealt with in the past
But let's ignore that - like we did before the accounting standards made us face up to the facts
Hi Beginner,
Many thanks for the link to Samuel Heath (post no. 3 above), it makes very interesting reading.
It's a great point that you've raised - namely that companies can only legally pay dividends out of distributable reserves. So if the pension deficit grows to a point where it turns distributable reserves negative, then no more divis can be paid until that situation has reversed.
With Norcros, the latest big rise in the pension deficit has reduced the retained profits part of the balance sheet (which is its distributable reserve) from £45.1m a year ago, to £15.3m as at 30 Sep 2016. So actually, it's capacity to pay dividends doesn't leave a lot of headroom now, given the size of the pension fund.
So there's a possibility, if bond yields go even lower than they were at 30 Sept, that there could be a hiccup in it not being able to pay divis until the situation returned to normal.
Great point, thanks for flagging it.
Regards, Paul.
Alhough Norcros group balance sheet shows only £15m distributable profits, this does NOT imply only £15m legal capacity to pay dividends. The actual capacity is over £100m.
The legal capacity to pay dividends is determined by the parent company balance sheet (s831 of Companies Act 2006).
At Norcros the parent holding company is not the sponsor of the scheme (the subsidiary, which has most of the employees, is the sponsor). The deficit therefore does not appear on the parent company balance sheet. The parent company had £127m of distributable reserves at 31/3/16 (p108 of annual accounts - note no trace of pension deficit here).
Norcros specifically cover this in the results today (possibly as a result of a recent discussion I had with them):
"Whilst the increase in the deficit has been significant it has not impacted the ultimate holding company, Norcros plc, which has a strong balance sheet and significant distributable reserves, in excess of £100m at 31 March 2016."
Note that at another company, the parent might employ most of the employees, and therefore be the scheme sponsor, and therefore have the pension deficit on its balance sheet. Eg Communisis, which had a problem with this recently. You have to look at the parent balance sheet in each case. A nuisance, but there it is.
Hi Dale,
Thanks for correcting me on that point, appreciated.
Regards, Paul.
I'm a bit disappointed in Tracsis (LON:TRCS) results on first glance.
They look fine on the face of it, but when you strip out the contribution by acquisitions they don't look so good for a company on a growth rating. Especially if you don't add back the £1m of share based payments.
I think management probably are quality but I'm afraid I think they're getting a bit much of the pie.
doug2500 - Yes I agree Tracsis (LON:TRCS) 's results are not as good as they appear on first sight. Couple of comments.
- An early sentence says : " ...which is ahead of original market expectations" . Oh dear. If we took to task a company a few days back for using such loose, ambiguous words, then to be fair we ought to complain about this to Mr McArthur.
- like you, I found the share based payments a bit rich to swallow. They are really payments into the long term incentive plan for employees. For all intent and purpose these are salary payments which should be expensed.
£1.1m out of a total adjusted net profit of £6.4m (statutory np £3.5m) is proportionally large. If you strip it out of the adjusted profit, the eps comes down to around 18p and not 22.4p.
Best, Ram
I agree about Tracis - and would add that there is very little trangable information regarding the outlook, just a lot of growth type hyperbole. Have sold my holding as now looking expensive. Ian
Unbelievable. I sold out of Tracsis after results and was going to redeploy my money at lunchtime but never bothered in the end.
Top of my list for a purchase was Avesco.
Gutted - but well done all holders. Delighted for you.
(I'll try to make it positive for me and use it as a lesson learned)
DTG ?
Re: Dart (DTG)
I would be interested in your views on DTG. Or are they too big? DTG had a stock rank of 99 for ages and performed as well as the stock rank would suggest. However, unlike in the last few years, they are undergoing significant changes which will make them more difficult to assess:
* starting to fly from two new airports - Stansted and I can't remember where
* a huge order for new jets to deliver these new services
* the impact that the fall in the pound may have on customers willingness to book overseas holidays.
Having said all of that, management seem to be very sound and they are very cash rich. I continue to hold.