Small Cap Value Report (17 Oct) - GBG, GBO, PFO, MTEC, MBH, SDY

Good morning! The US political debt crisis seems to have been resolved for the time being, so that's good news, although markets correctly anticipated that a deal would happen. So my Put Options look as if they will be expiring worthless, but as they were purely a Hedge, I'm fine with that - they served their purpose, in enabling me to sleep at night when a major uncertainty overhung the market, and also meant that I was protected if the market had crashed. Although as a colleague pointed out to me, by the time you think about hedging a specific risk, it's too late, it's the things that you don't yet know about that move markets, which is a good point.
Overall, I remain of the view that many small to mid caps are looking pricey right now, although digging around I'm still finding bargains, and the beauty of small caps is that due to liquidity, there will always be the odd clumsy seller, who knocks a price sharply down. So if you're prepared (both in terms of having done your research, and being able to move fast in hitting the buy button when cheap stock becomes available) then there are still plenty of opportunities around. As mentioned yesterday, Spaceandpeople (LON:SAL) was a good example, where I was able to pick up more stock this week at what I think is an excellent price of 107p. That has locked in a growing dividend yield of over 4%, so it always pays to keep some powder dry for unexpected opportunities like that.
I'm also keeping some cash on the sidelines, and in my main account am roughly 70% invested, with no gearing. That seems to me a sensible level, given that we're probably in the late stages of a 5-year bull market. With things like the Royal Mail float happening, and other IPOs, I think we are also beginning to see a lot more interest in the Stock Market from the general public - which again is a classic sign of being not far from the end of a bull market.
Also, I'm finding that many people I talk to in the investing world are suddenly talking about "story stocks" these days - bragging about the multi-baggers they've had, even though the companies are often very poor quality, even insolvent on conventional bases, but nobody's interested because the shares have doubled/tripled. Stuff like that makes me really nervous, as it means people are chasing stories irrespective of value - again, all late stage bull market stuff. So I'm keeping my eyes firmly on the exit, although happy to run with good value stocks, and the odd story stock too, providing the valuation isn't too high.
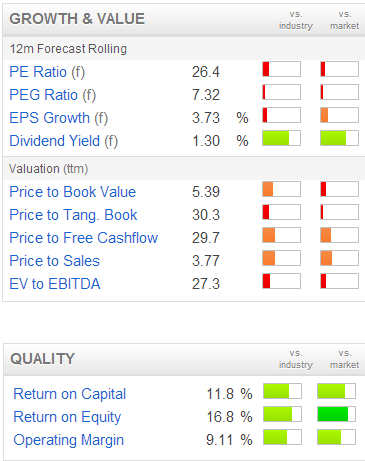
Identity specialist, GB (LON:GBG) has put out a positive trading update, for the six months to 30 Sep 2013. I thought the shares looked expensive at around a quid, but they're now 135p, for a market cap of a whopping £149m. That looks a very racy valuation to me.
Here is the Stockopedia growth & value graphic, where you can see how the valuation (on forecast profit) is scoring very poorly (i.e. the shares are expensive). So it's not of any interest to me, even though they have reported this morning that H1 adjusted profits are expected to be up over 50% at "not less than £2.3m".
The outlook statement says;
"We enter the second half with confidence and momentum."
So it sounds good for the time being, but what if something goes wrong, or even if future results fall short of expectations? Then you're looking potentially at a big drop in the share price. I don't see how this one stacks up on a risk/reward basis, at this price.
Another point to bear in mind, is that even when the market overall is pricey, you can still find bargains because more boring, safe sectors tend to become unfashionable, and hence cheap. I recall back in 1998-2000 in the TMT* boom, you could pick up housebuilders and good quality small to medium retailers on PERs as low as 4. The reason was that, even though the market overall was booming, people were chasing story stocks & raising the money to buy often complete rubbish, by selling down their holdings in good quality, but boring companies. (* TMT = Technology, Media & Telecoms).
I think we might well see the same happening again now, on a smaller scale, as people speculate more on story stocks, and turn a blind eye to value. That's fine by me, as I'm happy to pick up the unfashionable stuff on the cheap, as well as picking up the odd story stock at the right price, before the hoardes have descended on them. My story stock picks currently are Clean Air Power (LON:CAP) and Seeing Machines (LON:SEE). Although in both cases, they have a real product that is selling, and neither is making heavy losses (Edit: a reader has kindly pointed out that SEE recently moved into profit), so they're more early stage growth companies, rather than story stocks as such.
Paradoxically, it's often easier for blue sky companies to get a higher valuation, especially if they are zero turnover companies, because people can let their imagination run riot over the future potential, whereas if you do actually have turnover, people will forecast the future based on the existing figures, which tend to make those forecasts more grounded.
The other key thing is not to fall in love with the story or the stock. We've all done it before, and need to make sure we don't do it again this time - this is my third major bull market, so one really should be wise to this kind of stuff by now, and it's amazing how the mood of Mr Market can change very quickly from euphoric to depressed - the money needs to be in the Bank before that happens.
Anyway, late stage bull markets become a game of pass the parcel, where everyone knows the stocks they're holding are over-priced, but are all gambling that they won't be the one holding when the music stops. Unless you're a very shrewd trader, I think that's a mug's game, so I'll stick to value and GARP, which should mean that if/when the market does correct downwards, the impact should be small & I'll have cash to pick up the bargains from forced sellers. Remember that a lot of people are in this market using gearing, and we regularly see fashionable stocks plunge as waves of forced sellers are closed out by the SB companies.
Not a great deal of trading statements this morning, hence why I decided to do a more general, strategic bit of commentary this morning. However, let's now return to some more company news.
Regulars will know that one of my least favourite companies (due to very aggressive accounting, inability to generate cash, and excessive hype) is Globo (LON:GBO). They have done another fund-raising, this time a Placing at 71p, to raise £24m before costs. It seems very odd to me that such a highly profitable company has to repeatedly raise cash from the market. Probably because the profits end up in debtors on the Balance Sheet, hence one has to question how real they are?
I might turn out to be wrong on this company, but there are enough red flags in their accounts to make the outcome irrelevant for me - the risk is too high, so it's uninvestable as far as I'm concerned. The key items of concern being that debtors are far too stretched (usually a sign of write-offs to come), and that EBITDA is highlighted as the key performance measure, even though it ignores a large amount of their operating costs (which are capitalised).
Interesting to see that Directors didn't buy any Placing stock, but instead used it as an opportunity to offload 1m shares of their own - another red flag. I'm sure that bulletin board rampers will be taking my name in vain over this, but I just speak as I find, and have no position in the company.
The danger of De-Listings has receded somewhat, as we're in a bull market for small caps, so companies can perhaps see more value in maintaining a Listing once their share price comes alive again. Also, a point that has been made to me several times this year by Directors of small Listed companies, is that there can be major benefits from being Stock Market Listed - primarily in terms of how the company is perceived by customers & suppliers. So it definitely helps some small companies punch well above their weight, and enables them to win contracts that would have been out of reach had they not been Listed. A Listing does therefore give considerable credibliity to a company.
On the other hand, there comes a point where the costs outweigh the benefits, and whenever companies announce their intention to De-List, it's a pretty much instant 50%+ loss for investors. So a massive risk. It's therefore worth checking what type of companies announce an intention to De-List, and avoid other similar companies.
The latest one to announce an intention to De-List is Prime Focus London (LON:PFO). It's market cap is only £1.8m, which is too small to be Listed really. Also, it has a poor track record of mostly being loss-making, and clearly has problem levels of debt. Their largest shareholder holds almost 60%, so another red flag there. Hence overall, there are 4 clear red flags there (too small, loss-making, high debt, and too big major shareholder) which satisfy me that I would never hold shares in anything like this. So no need to adjust any of my usual risk parameters.
Investors outside of London often complain that they can't get to meetings that are nearly always in London. So it's good to see an event being arranged in Manchester (Mon 21 Oct, at the MalMaison Hotel, 1-3 Piccadilly, Manchester) - it's a Private Investor meeting with the Directors of Matchtech (LON:MTEC), a recruitment company. Equity Development are organising it, please email Hannah@equitydevelopment.co.uk if you would like to attend.
Michelmersh Brick Holdings (LON:MBH) announce the completion of their land sale, 15 acres in Telford, for £4.6m, with £3m of that deferred. the last paragraph of their statement today sounds encouraging (my bolding):
"We are, however, principally a brick manufacturer and we continue to compete strongly in a market that is showing signs of price recovery. The upturn in demand we have seen over the past few months is encouraging us to invest in our existing plants to increase capacity and efficiency, which will, in due course, increase Group revenue."
Companies like Speedy Hire (LON:SDY) are interesting to look at, as they can be a good barometer of the economy overall, or at least the construction sector. Their trading update today is surprisingly downbeat. We've been hearing a lot of positive news about economic recovery, but Speedy Hire say:
Whilst we are yet to see any material improvement in construction work ...
The UK market "remains challenging", they say, so perhaps we ought not to get too excited about pricing in too much economic recovery into shares just yet?
That's it for today. There's a good lively debate in the comments section below, which almost got out of hand, but didn't thankfully! So do please feel free to join in - all views are welcomed, providing they are evidence-based, and reasonably courteous.
A lot of people don't seem to realise this, but you can sign up for Stockopedia completely free (not the free trial, but a completely free account), but the link is very small, buried in the Plans page. That enables basic features, and allows you to comment after articles, and create your own threads on the Discussion pages here. Obviously it helps the guys to develop the site further if people take out paid subscriptions, but a free account is a good way to start.
OK, that's me done for today. See you from 8 am again tomorrow morning!
Regards, Paul.
(of the companies mentioned today, Paul has long positions in SAL, SEE, and CAP, and no short positions
A Small Caps Fund to which Paul provides research services also has a long position in SAL)
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

66 comments
Both GB & the brick company MBH are on my hit list They both look good to me.SDY does not fit my criteria although I have held it in the past ,still good but not quite ticking all the boxes for me.
Cheers from Lightningtiger
A 'tongue in cheek' article (or is it?): If they use these words, don’t buy their shares
http://www.telegraph.co.uk/finance/personalfinance/investing/10386450/Terry-Smith-Words-that-should-be-banned-from-finance.html
>Besides 11 years of investing is kindergarten stuff.
Can you tell me which kindergarten that is so I can get my partner's grandchildren in?
Goodbye !!
Smartphones are here to stay. In my book GBO has an excellent track record of both profits and revenue. They may have problems with accounts, that is their problem,but you cant dispute there is a good market out there for it. Everybody is using mobile phones & a lot will want the latest gismos like this. I am holding GBO simply for growth. The tech gismos will continue because people are always looking for the new tech gadgets. At the end of the day we have a choice to buy or leave it & invest in something else. Do not get all worked up about it. Order please. Cheers fromLightningtiger
Actually it was an addendum to my previous reply to your factually incorrect post.
I will repeat the first part again.
I am really not sure what you are on about, Globo's recent customer wins include the likes of First Data, Coral, Dixons, Estee Lauder, European Reliance and Mercedes Benz. The recent acquisition of Notify brings additional customers such as Oracle Corporation, Novell Inc., Securitas, True Value Company, Trinity Health, and The U.S. Equal Employment Opportunity Commission (EEOC). Notify are also licensing their technology to Novell and it will be interesting to see whether this is a model that Globo can use across it's product range
I see rather large multinational companies.
Therefore your statement that any FTSE 350 co would not touch this with a barge pole apppears way off the mark.
Oh whatever,I am not interested in joining some secret sect club with hidden agendas.
It is clear to me that all is not what it seems on here.
Besides 11 years of investing is kindergarten stuff.
I see - you are j777j on ADVFN !
Certainly - at your exit haha !! youre just a little bit too insulting for this site laddie - be off with you.
I was replying to another completely left field comment from someone who has clearly done no research at all.
"Their BYOD offering, Go!Enterprise, is really for the SME (small to medium enterprises) market. No FTSE 350 company would touch it with a barge pole. Lots of reasons and issues: strong IT departments, security issues, Data Protection Act, IP theft, loss of sensitive data. So the market they can address realistically is the SMEs "
This is balderdash! Utter claptrap.
Anyway plenty of comment across the boards today about your "Dear leader."
Should we all be clapping in slow unison?
Jam7
"This is balderdash! Utter claptrap."
If that's all you have to offer by way of reply, then maybe this Board is not for you. Have you tried advfn?
As I understand it the idea behind GO!Enterprise BYOD is that the employee can use their own phone be it Apple, Samsung, Blackberry, Sony, HTC and dare I say it even Nokia. Will Samsungs KNOX product work with all these other makes? A quick look at the website suggests not. The Employer would have to provide or stipulate all employees use Samsung. GO! Enterprise allows employees to bring their own phone, whatever it is and interface with his/her employer's systems.
Hi John -
My view is that each smartphone manufacturer will have BYOD functionality bundled with their hardware, Apple, Samsung, Nokia etc. So the question then is systems integration. I know of several large financial services organisations who regularly integrate and support today an employee's smartphone (Apple, Samsung, etc) to the company;'s mail service, all within a secure environment of their choosing (Cloud or proprietary servers). It doesn't take a great leap of the imagination to see an extension of this with the BYOD functionality.
Regards, Ram
GBO
I am really not sure what you are on about, Globo's recent customer wins include the likes of First Data, Coral, Dixons, Estee Lauder, European Reliance and Mercedes Benz.
The recent acquisition of Notify brings additional customers such as Oracle Corporation, Novell Inc., Securitas, True Value Company, Trinity Health, and The U.S. Equal Employment Opportunity Commission (EEOC).
Notify are also licensing their technology to Novell and it will be interesting to see whether this is a model that Globo can use across it's product range.
I see rather large multinational companies.
If you listened to the cc they mentioned the largest customer to date has 15,000 installations and looking to expand up to over 25,000.
The tech is highly scaleable.
November brings the release of the first jointly produced Globo/Notify product.
Paul,
As ever thanks for your write up, always very interesting and sometimes very amusing. I just wanted to share with you some investor angst over Anite this week, ARRRGGGHHHHHH! OW! Next time I will listen to you.
Best wishes
Guy
Thanks Ram, very interesting information on KNOX.
Meant to include this link to Samsung's website for more info on KNOX
http://www.samsung.com/global/business/mobile/solution/security/samsung-knox
Guys
Re. Globo. Putting aside the health or otherwise of GBO's financial accounts for the time being, a fundamental question for me is the value and positioning of their products and services. Their BYOD offering, Go!Enterprise, is really for the SME (small to medium enterprises) market. No FTSE 350 company would touch it with a barge pole. Lots of reasons and issues: strong IT departments, security issues, Data Protection Act, IP theft, loss of sensitive data. So the market they can address realistically is the SMEs. Yes they are one of the leading suppliers in this segment and their tie-up with Ingram Micros is likely to open it up. But here is something from the left field: Samsung KNOX. This product (undergoing pilot implementations at the moment) will come bundled with high end Samsung's smartphones and it appears to do everything of significance that Globo's BYOD provides. Now if you were senior management, would you go for Samsung with a bundled BYOD app on purchase and deploy that to your employees, or install Globo's? Well, remember how Blackberry rose to prominence in the corporate market. They provided a bundled email solution to small and large businesses. A few years back, no business manager worth his salt would be seen without his Blackberry seamlessly integrated with his company's back-end systems. So my crystal ball tells me Samsung, Apple and other smartphone and tablet providers will simply bundle in the full gamut of BYOD functionality, for free. And that IMHO would pull the rug under the feet of Globo and other similar providers. Just my view.
Regards, Ram
My name is Monty and I hold some GBO (PHEW! that feels better already).
I am an accountant and of course fully understand Paul's clearly explained distrust. I also acknowledge its no longer cheap. The recent price increase looked mad and the pullback more than likely due to a whisper of the placing news leaking out. Must confess I did not like seeing the director sales.
And yet I can see the possibility of a well qualified, stable, workforce working in Athens to produce great tech at a reasonable price. Talent turnover (a big issue for many such companies) should be minimal. Then the distribution deals could (though not necessarily will) generate an enormous turnover compared to current market cap. Possibly the long debtor period is related to the distribution arrangements, not ideal but not necessarily a disaster.
Well that's about what I've got. Its now my most speculative holding yet I hesitate to top slice (I know I should).
basharman - I would just be a bit wary with the likes of Plus500 - spreadbetting / CFDs is a super competitive industry and many have fallen by the wayside (Worldspreads comes to mind). It is very difficult to compete with IG and even the likes of City Index backed by Michael Spencer have failed after spending tens of millions in the process.
jam 7,
Take a couple of minutes, and re-read you comments to understand where the replies are coming from.
Let's stick to the fact and reach conclusions.
GBO.
yes they are burning cash.
yes the owner has significant % of shares
yes sales are up
yes, debtors are very high and typically a red flag indicator.
yes institutional ownership is low
make your choice, but listen to the comments dispassionately - you may be actually wrong, but that's not the point.
Please keep the discussion civil chaps, and avoid personal attacks. We're just here to discuss stocks. We want to keep Stockopedia comments section a cut above the rubbish you read on some other sites.
I don't want to curtail free speech, but I will Moderate any posts from now on that contain personal abuse.
Many thanks,
Paul.
I would like to highlight an interesting company which IPO'd (is that a correct term?!) at the end of July - Plus500. It's a retail online (and phone) trading platform (similar to IG Group) I bought into these having noticed that Mark Slater bought some for his fund. The revenue growth impressed me and the fact that the margins are very high 30-50% it also is expected to yield around 5-6%. The market cap is currently c£150m and on a rating of about half that of it's Big Brother - IG. The trading update, which was today was very good with PLUS reporting an increase in revenues for the first 9 months of the year by 52.7% with a growth in new customers. The strategy is to expand into new geographical markets. I would appreciate any thoughts and comments. Thanks.
I think that one of the most important notes in the accounts to look at if there is a worry about cash generation is the one on revenue recognition, this is an extract from Quindell's 2012 report about their outsourcing revenue (I can't find these words in the 2011 report):
"In the case of certain of the Group's revenue streams the amount of revenue recognised is measured by reference to the total amounts likely to be invoiced less a suitable allowance to recognise the uncertainties remaining".
I can't see any other way of reading that other than some of next year's invoiced sales are being pulled into the current year.
jam7 - you are a clown!!
Oh dear resorting to personal attacks.Have we hit a nerve somewhere?
Some cosey little club?
Interesting debate re: GBO et al.
Having said "My story stock picks currently are CAP and SEE. Although in both cases, they have a real product that is selling, and neither is making heavy losses, so they're more early stage growth companies, rather than story stocks as such." Same can be said of GBO, it has a real product that is selling and it is still a small company. Who knows how far it will run? So one man's "story stock" is another's "early stage growth company".
The main issue (as noted by Paul) is that it is not as easy to identify a "home run" growth stock that just keeps giving in terms of sales/eps as it is a "base hit" value stock that has been temporarily rated too cheaply. The reason being that there are quantitative measures to value all stocks BUT who knows what sales/eps will be next quarter/year? However, for the investor who can pick the next Dell, Apple, Google or Amazon in the early stages and simply hold the shares for long enough the rewards can be massive, even transformational given a decent bull market. This is the reason that I hold BOTH growth (story) and value stocks.
note - I have no current position in GBO, CAP or SEE.
Having said all this, I think there is value in becoming a specialist in something and sticking to your knitting. Careful value investors make money, careful growth investors make money. People who buy the story or use share tips are the likely cannon fodder.
And you have no financial interest whatsoever?
Jam7,
I am required to disclose all personal interests in a disclaimer at the end of every article.
So to confirm, I have no financial interest in GBO or QPP. Never have done with QPP, although I did hold a small quantity of GBO briefly some time ago, but when I did more digging & realised the accounting tricks being used to inflate EBITDA, I quickly dropped them.
It's not of any interest to me what the share price has done since. I don't trust their accounting, so it's uninvestable for me. Other people can do what they want, and good luck to them.
Regards, Paul.
Jam7- its because people are interested in what Paul has to say. Exactly the same things happens across other companies bulletin boards when he comments on them.
This gets more interesting by the minute.
Hmmm you were quick to appear!
BTW would you have any ideas why your posts on Globo are simultaneously posted across all bulletin boards.
As you say you have no financial interest in the shares?
Exactly the same thing happened with your last report.
It turns out an ABC2104 on iii is the same person as BPC10 on LSE who is the same person ans Martint111 on Advfn all seemingly very keen to get your message out.
I am curious,has your cautious approach provided you with anything more that very pedestrian returns?
Jam7,
You should research your subject before you start slagging them off! (otherwise it just makes you look daft)
I'm absolutely on fire at the moment actually - my SIPP has doubled in the past year, with no gearing. My Blog picks from last year have performed spectacularly well, and my public record of value/GARP picks, updated in real time, doesn't look too shabby either!
And the key thing is that these gains are NOT being made on dodgy story stocks with heavily massaged accounts and numerous stock promoters pumping them. These are all good, solid companies, mostly with net cash & paying dividends.
As for bulletin board posts, I've not posted anything this morning. People often copy my morning reports onto other bulletin boards, that's up to them, I don't have any control over it & have given up trying to control the copyright - after all, if it's on the internet, then it's out there, and the reports are free.
People wouldn't read these reports if they were full of rubbish!
But I appreciate we always get an influx of new members whenever I point out that some go-go stock has significant downside risks attached to it.
Regards, Paul.
Just to amplify a little more, it was a healthy scepticism about firms that seem to continually find reasons to need to raise more money that allowed me to avoid the debacle at Aero Inventory.
Investors (as opposed to speculators) need to bear in mind that successful investment is as much about avoiding big losses as it is about making big gains.
Cheers,
Mark
Few bets, big bets, infrequent bets - The Dhandho Investor
I think a very frank appreciation of one's perspective on risk and on risk in general is very important to investing. Looking back at the utter naivety I had in picking stocks when I'd just started out, I'm very thankful that I missed some very near catatrophic mistakes.
It's one thing to have accounting knowledge, another to properly wield the tools of investing, and a completely different beast to manage our temperaments as human beings!
What a good debate chaps. I'm afraid I'm with Paul. I am finding more and more that value is just getting hard to find. So lots of stocks are going on watchlists but not a lot of buying. Waiting for some of the froth to blow away. You just have to be wary of massaged numbers and repeated cash raisings, when the cash should be accumulating nicely.
I have however just invested myself in what I consider might be a bit of a "story" stock. By which I mean it's been around a long time, no profits, plenty of set-backs. But sometimes you get the feeling that, having sucked up (and wasted) a lot of capital, there is (finally) proof of a solid business model. New (and impressive) management comes in (esp CEO and Chair), sales continue to rise, and the company looks like it's on the cusp of profitability. But that lack of profits still makes it a valuation stab in the dark. What looks like a highly opportunistic acquisition could bring forward substantially the date when profits arrive. Finally, there's a wealthy backer (with a board seat) who seems to have the confidence (or maybe just the cash, but I doubt it) to keep hoovering up stock and lending the company money.
That company - Hydrodec.
I'd love to hear your thoughts Paul - appreciate you're a value man, but as you mentioned "story" stocks, i wonder if you make exceptions and write about these.
Sprue Aegis was a story stock for me. I invested about £2,500 when it first floated on OFEX in around 2000. I followed it for a while and then I invested £250k in the mid noughties (via an EIS qualifying placing, so £200k net of 20% relief)), and then bought more (on market) through the late noughties. Average price for around 4% - 20p. I sold some at 50p and more at 60p so you can imagine how I felt when the take over came. I still have a decent slug though, and am targeting 200p. Loving the dividends too.
With Sprue I made the leap, mainly because I was so impressed with the management. Ironically, "my" money was to help them get into the US (through a deal with Du Pont) that actually never took off, but lessons were learned, and they circled the wagons and "nailed" the UK, before then moving on Europe.
I'm not sure Hydrodec is my next Sprue, but I have been buying a few slugs at 8-11p on the last year or so. The thing about this particular story stock is that I think if you wait for the profit to come, you'll miss the boat, or you'll miss the opportunity at least to get in at less then 15p.
Hydrodec seems to have had a learning experience in understanding the real drivers of an industry rather than just accepting huge market size numbers which are always bandied around fo story companies. As far as I can tell Hydrodec to date has been effectively a straight bet on the relative prices of their input and output commodities - a bet which the company has lost in the past.
It certainly seems well worth keeping and eye on it for the future though. It does worry me that Velocys (US gas prices vs the oil price) and especially Quadrise might in fact be similar types of bet on input price vs output price ie factors beyond their control.
Hi Paul,
Super report today. Couldn't agree more with your comments. Nil Carborundum!
Another factor distorting AIM in particular, IMO, is the recent change to ISA legislation. I suspect a lot of money has been poured into speculative AIM stocks, when they were allowed in. Very hard to judge how long that will last - and it well get a fresh boost each year, as the annual ISA monies come in. Of course, a thirst for "story stocks" is a rogues' charter, and there are plenty of sharks who will take advantage of inexperienced investors.
Sorting the sheep from the goats will be tougher than ever.
Cheers,
Mark
Paul, Many thanks for the headsup on the MatchTech meeting in Manchester. It would be great if there were more companies prepared to present their case to private investors outside the M25.
So now, what happened with Quindell?
Quindell: I would say the jury is very much out on that one too - they've not generated any proper cashflow at all. They're heavily massaging the figures to present a positive picture (e.g. reclassifying debtors into other debtors, which has ballooned, so that they can claim that debtor days is improving, when actually it isn't [if you consider all debtors]).
That said, the flow of contract wins has been very impressive, and for the moment the Stock Market is giving it the benefit of the doubt. Although the very low forecast PER, and lack of Institutional investors over 3%, suggest that the story has not been bought by many people other than excitable PIs.
Maybe it will turn out well, but I'm sceptical. It's not about being right or wrong necessarily. For me it's about assessing risk, and where I find too many red flags, then I don't invest. The result is that my portfolio very rarely takes any serious hits any more, because I've screened out the highest risk situations.
I'm not saying mine is the only approach, far from it, there are numerous different strategies investors can adopt. But people read this report because I've got a very clear risk averse, value-orientated approach, which works very well in all types of markets. I don't mind missing out on high risk multi-baggers in bull markets, because an approach that takes big risks will inevitably come unstuck sooner or later. I know this, as I've made every mistake in the book in the past, which is what drew me to my current, low risk approach!
Cheers, Paul.
Life is full of if's,meanwhile one carries on hunting.I always take comfort when the founder and Ceo has a very large stake in the business,as it means our interests are aligned.
I look forward to reading your glowing praises for the company in six months time.
Absolutely, if and when GBO delivers some real profit & cashflow, then I will cheerfully eat humble pie on this one & praise it until the cows come home! ;-)
Regards, Paul.
The point is Globo is trading at a steep discount to both the overall market and it's peers.
The reality is that the next 6 months sales volume will tell whether this is really a great company in a great space or not.To date it has been all about grabbing footprints,distribution deals,(Ingram Micro,IBM,Fujitsu)product development and consumer education.
Are you familar with the BYOD space? In your critique you make no mention of the recent Notify Technology acquisition as one of the reasons for the fund raising.Apart from the MDM products that they can now cross sell,it bring 60 Silicon valley based techies to the group.
I think it was Peter Lynch that said words to the effect of "sales up ,share price up."
What you can't argue with is the sales growth over the last several years.
Hi Jam7,
GBO: It's only at a steep discount to its peers if you accept adjusted profit or EBITDA as sound bases for measuring profit. Trouble is, they are not a sound basis at all, but are badly skewed measures which greatly inflate the true level of profit in this case.
However, I accept your point that the sales growth is impressive, and IF they can turn that into real cashflow, and real profits (i.e. after accounting for intangible amortisation), then you could be onto something. However, from my perspective as a risk-averse investor, I'm not interested in paying up-front for something that looks & smells dangerous to me. I've seen too many of these high growth but no cashflow type of companies unravel in the past.
Regards, Paul.
Not sure the Ebay's Google's Amazon's and many, many others would agree with your observations, but I will leave it at that.
Jam7,
Of course if/when a really high quality, high growth tech company crops up, then a toppy valuation is justified. The trouble is, it's like looking for a needle in the proverbial haystack. Also, technology changes so fast now, that very high valuations for growth are especially dangerous since the product that is so popular now could be defunct in just a couple of years' time (look at Nokia, Blackberry, etc).
So if strong, sustainable growth is in evidence, based on sound financials, then a rich valuation can be fully justified. Trouble is, I don't think that's the case with Globo, but good luck with it.
Regards, Paul.
P.S. If I had to choose a tech stock to be long of, it would be Twitter. In fact, I'm nicely up on a grey market long position on that one. I think it's unique, has huge potential value, and the fact that it's been loss-making to date doesn't actually matter.
That is indeed strange because according to this website you contribute to,Globo passes 6 screens,including GARP.,Zulu principle etc
Unless of course the site is a load of £$"!
So what are people paying for?
Jam7,
This is Stockopedia, not advfn, so please moderate your tone, or I'll moderate it for you.
Stockopedia is a toolkit for investors who want to do DIY investments. So the screens are provided to show a wide range of investing styles & strategies. So stocks like Globo will do very well on any momentum-based screen, for example, because the shares have gone up a lot. To a value/GARP investor like me, that means nothing, as I don't buy momentum, I sell into rising prices because of the BLASH principle.
I don't know if you were around in the TMT boom/bust of the last 90's, but we saw all this stuff happen then, and it's natural & inevitable aftermath - which was that pretty much all the go-go stocks of the boom, ended up crashing often 90% or even 99%. That's what happens when valuation detaches from fundamental reality - sooner or later everything reverts to the mean, the bubble bursts, and a lot of novice investors end up losing most of their money.
The financial memory is about 15 years, so arguably we are now seeing the same type of scenario building up again - people are chasing story stocks, and are disregarding the fundamentals, fixating on growth, and any KPI which shows them what they want to believe, in order to justify valuations that are getting too high on conventional grounds.
There's a good case for enjoying the fun, if you are a skilled enough trader to get out at or near the top. That's not my game anyway - as you can see from the title of my morning reports, this is a Small Cap Value Report. So I will challenge aggressive valuations where I see them. Armed with the facts, if people still want to chase things higher, that's up to them, but it will end in tears at some point, it always does.
Regards, Paul.
Do you actually hold any stocks?Or simply a commentator? By the sounds of it you don't hold any technology shares because they are likely all guilty of aggressive accounting.
Jam7,
I've been a professional small caps investor for 11 years, and typically hold about 30 different companies, several of which are technology companies.
My focus is on Value and GARP shares. As my background is in accountancy, and having spent 8 years as an FD, I drill into the numbers properly, which is why people like my reports.
In my experience, the way to avoid big investing losses, is to avoid hyped up shares where the figures have been heavily massaged to present a misleading overall impression. People can make plenty of money on the way up, but when the penny drops that the profits aren't real, then it's a long way down.
Cheers, Paul.
Based on the company being able to achieve 8.56p EPS for 2014 making for a p/e of 17 just 14 months out
The accounting practices are no different from many other early stage fast growing technology companies.They comply with all apllicable laws.
A random selection of UK listed tech co's 2014 p/e's
Blnx 39
IMG 24
IOM 25
Opay 19
ARM 38
SRT 14.5
None,may I add, are growing anything like as fast as Globo.If indeed Globo was to get just the average of the above ,the share price would be 225p.
150p is just my base case.
The tail winds will be further contract wins and news of the success of the recently launched Go Enterprise product.The Notify acquisition will enable the company to cover the entire spectrum of the marketplace they are addressing.
Jam7,
Trouble is, the broker forecasts are based on adjusted EPS. That ignores a lot of the costs, so it's giving a false picture of the company's real profitability. If you want to base a valuation on a multiple of heavily massaged profits that never turn into cash, then that's up to you!
I just to make sure that my readers are aware of the risks, then they can make an informed judgment.
It's interesting that they show trade debtors separately on the face of the Balance Sheet, perhaps to emphasise that it's under control? Trouble is, what about all the other sundry debtors, and various other debits on the Bal Sheet? They could hide a multitude of sins. Quindell does the same thing - they show an improving trend in trade debtors, but then various other debtors are going through the roof - they just reclassify debits to make things look better! Again, huge red flags for aggressive accounting treatments that are probably designed to flatter overall performance.
Going back to Globo (LON:GBO), the litmus test is cashflow. Look at their last cashflow statement (this is part of it, as can't fit any more onto the page), and note that in all 3 periods shown, their operating cashflow is almost or entirely consumed by the purchase of intangible assets - i.e. internal costs that are being capitalised! This thing doesn't generate any cash AT ALL! Which is why it needs to keep raising fresh equity.
I took some profits at the end of September but after halving my position still have a 3% holding which I am happy to run. Paul is right to highlight the lack of cash generation and it needs to be watched closely. However Globo may just have a fantastic product with GO!Enterprise and I would suggest early evidence suggests that it is selling well. The Notify Technologies acquisition looked sensible and together with its distribution agreement with Ingram I'm hoping for good q4 sales growth, accelerating into 2014.
As for director selling; the chief executive did not sell any and who knows why three others sold some shares; maybe Globo shares represented virtually all their wealth! Personally I always find director share buying is a useful indicator but do not pay much heed to sells!
Trade receivables increased only by 4% compared to the Group's revenue increase (52%). All receivables are healthy and 60% of them are outstanding for less than 90 days.
"The correct price should be nearer 150p"
The directors selling don't seem to think so.
I listen to key people and follow their track record..So far Costis has delivered.
Costis Papadimitrakopoulos, Chief Executive Officer commented:
"We are delighted with the strong support for the placing from both existing and new shareholders. Globo now has the financial resources to implement the next stage in our strategy to become a global leader in enterprise and consumer mobility. Following the recent acquisition of Notify Technology, GO!Enterprise is the enterprise mobility market's most complete solution incorporating mobile device management, secure container technology and a cross mobile platform application development environment to build, distribute and manage apps. This places Globo in an excellent competitive position and we can now take full advantage of the opportunity we have to generate substantial value for shareholders."
They are employees,with frankly quite small amounts of shares. Costis,the founder and Ceo has not sold any.
GBO the founder and CEO who owns by far the largest number of shares,did not sell any.
The co has received strong institutional support from the USA.
The shares offer the best value for a fast growing profitable tech company.It trades on a very significant discount to it's peers.
They have only just started to ramp up GO Enterprise in the USA.Initial indication have been very positive.The funds will enable them to fund the Notify acquisition, hasten their product roll out and expansion.
The correct price should be nearer 150p
Jam7,
Re Globo (LON:GBO)
"The correct price should be nearer 150p" - based on what??
If you correctly account for intangibles (i.e. either put them back into the P&L as costs, or leave them on the Balance Sheet but deduct the amortisation charge from the P&L), then it really doesn't make very much money at all.
And the money it does make does not convert into cash, instead it just piles up as various debits on the Balance Sheet. These are serious warnings signs, ignore them at your peril.
As is the repeated need for fund-raisings. The cash should be flowing in from trading, but it isn't. Another big warning sign.
I take your point about the major shareholder not having sold though.
Regards, Paul.
GBO - directors selling a significant part of their holdings in the placing is a huge red flag IMO, although I'm impressed they managed to place that much at 71p!
GBG agree Paul , reference the racy valuation. Banked 25% profit at 125p earlier in the month. It is highly priced, however the flip side is that it is in sector which really is growing quickly..... On line authentication, due to the nature of fraud will always be required. The diffentiator is finding a company who is at the cutting edge in terms of protection v user experience
Re. GBG. There are a few big trends in the information technology sector and one of them is cyber security. GBG is one of the few niche players in the UK in this space. However It does not seem to have a patented technology or other competitive barrier that would justify the heady rating. So I agree, too risky on both fundamental grounds or as a punt.