Small Cap Value Report (18 Feb 2016) - AVG, NMD

Good morning!
It's very quiet for results & trading updates today.
ShareSoc seminar - Altrincham
As mentioned in yesterday's report, I think that networking with other investors is absolutely key to becoming a better investor, and also enjoyable. Most events for investors tend to be in London, so it's great to see ShareSoc and others arranging meetings further North.
This type of event simply won't continue to happen if people don't support them, so I strongly urge all readers within travelling distance of Altrincham (near Manchester, as I just found out from Google Maps, lol!) to attend this event - details here.
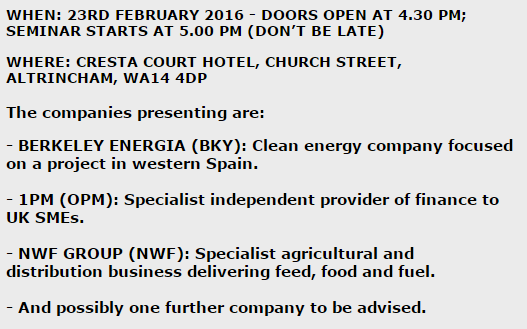
I would certainly be interested in meeting management of NWF Group, and 1PM, both are interesting companies. I'm not familiar with BKY.
Avingtrans (LON:AVG)
Share price: 123.2p
No. shares: 27.7m
Market cap: £34.1m
Interim results, 6m to 30 Nov 2015 - a reader was saying how marvellous these results were yesterday - I had a quick look, but something didn't look right in the numbers, so I had another look last night, and spotted an arithmetical error in the figures, as explained below.
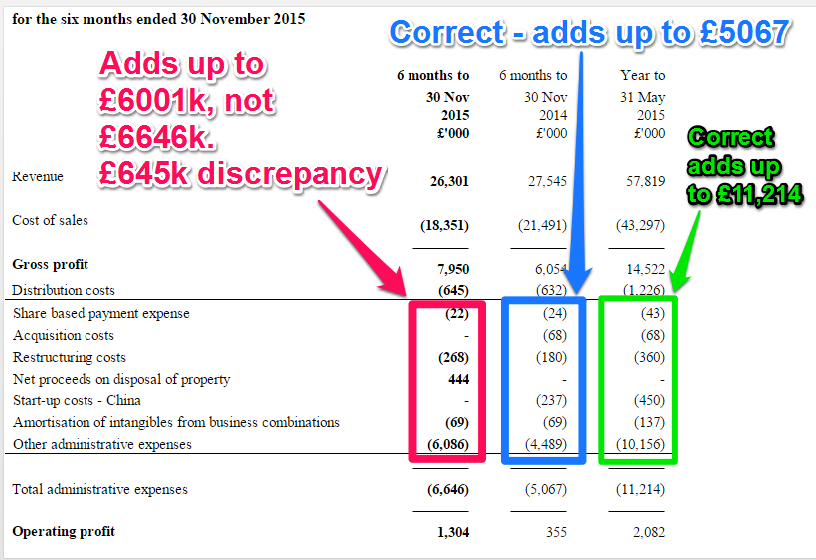
So basically someone didn't check the arithmetic properly. This figure needs to be corrected:
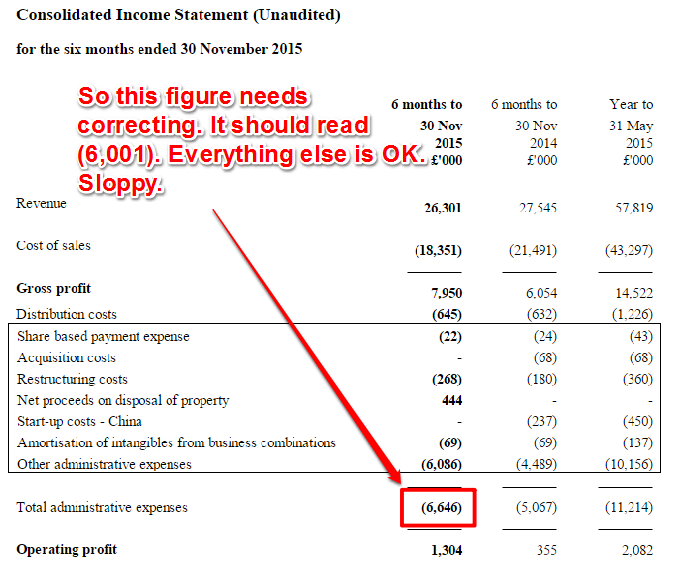
The profit figure isn't affected, so it's not a material error as such, just a sloppy addition error which should have been spotted and corrected when the figures were being reviewed prior to publication. It's really not good enough, getting a basic thing like this wrong. Investors have to be able to rely on the figures actually adding up correctly.
I spent many years producing & checking figures as a trainee auditor, and then an FD, so if a figure is wrong, it just jumps out of the page at me - your mind is doing calculations without you even being aware of it.
Operating profit - rose strongly (from a low base of £355k in H1 last year) to £1,304k this H1. Note that the operating profit margin is OK, but nothing to get excited about, at 5.0%.
If we double that, to make a full year, then operating profit would be £2.6m. I can't get particularly excited about that, given that the market cap is £34.1m. However, H2 is expected to be much stronger than H1.
Second-half weighting - results last year showed a bias towards H2 for profits, and it looks as if the same is likely this year;
Our full year revenues are expected to increase - due to second half weighting, especially in Energy and Medical. This confidence in the outlook for 2016 was boosted by the recent contract wins with Rapiscan and Bruker, thus underlining our continued dividend progression."
Finncap are forecasting adj. PBT to rise from £1.2m in H1 to £2.9m in H2, giving £4.1m for the full year. That's starting to look a bit more interesting.
Valuation - Finncap is forecasting adj. EPS of 12.6p this year, and 17.7p next year, so the PER based on a share price of 123.2p looks quite good value, at 9.8, and 7.0 respectively. The latter figure is of course dependent on the company achieving the considerable increase in profit forecast for next year, some of which is coming from acquisitions I believe.
Outlook - the narrative generally sounds pretty upbeat, although obviously an H2 weighting for profitability does hold potential risk that something might go wrong to trigger a profit warning in H2.
With good progression in the aerospace business and results for Energy and Medical anticipated to be skewed towards the second half, we remain optimistic about our prospects for the full year and beyond. Our strategy should lead to growing investor returns as stability is restored and with increasingly robust, long-term, blue-chip customer relationships, we remain confident about the future of Avingtrans and achieving the Board's expectations for the full year.
They've specifically confirmed full year expectations too, which is good.
Balance sheet - overall it looks alright, although I am concerned that debtors seems high, and there is some debt, although it's not worryingly high.
Overall, there is a good solid NTAV of £22.1m, which is 64.9% of the market cap - so there's decent asset backing to underpin the valuation. Although obviously the valuation is mainly based on a multiple of earnings.
My opinion - overall, I quite like it. So definitely one to do some more research on. I'm not terribly keen on investing in this sector - engineering/aerospace, as contracts can be lumpy, and problematic at times.
Having said that, it sounds from the narrative as if the company is on a roll, and the valuation looks modest, if they are indeed able to hit forecasts for next year.
Overall then, well worth a closer look.
North Midland Construction (LON:NMD)
Share price: 106.5p (down 4.9% today)
No. shares: 10.2m
Market cap: £10.9m
Trading update - I'm surprised this share hasn't fallen more than it has today, as the company announces fresh losses equivalent to 28% of its market cap!
The resolution of certain previously referred to legacy contracts across the Group has now been concluded and the settlement figures expected have not been achieved, resulting in additional total losses of £3.1 million. This leaves only one problematical legacy contract to conclude.
Mercifully, it only has one problem contract to conclude. I wonder what additional losses might crop up with that?
Other comments sound more upbeat;
Despite these negative settlements, due to strong underlying trading, management still expects an unadjusted profit for the full year, albeit significantly below previous management expectations.
The order book for completion this year currently stands at £195 million and the Board is confident about the outlook for the year.
That seems to suggest that the core business is doing alright, if it can mop up losses of £3.1m on problem contracts, and still report an overall profit.
My opinion - I've had a quick look at the historic figures, and this share doesn't interest me. It's a low margin business, with a not very strong balance sheet. Divis stopped in 2013, and wherever possible I try to avoid low margin building companies, as they often get into a mess with contracts that go wrong.
I suppose there might be an opportunity for the shares to be re-rated, once legacy problems are fully resolved, perhaps?
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

12 comments
Hi Paul,
Perhaps I am being dense but I don't think that update is for North Midland Construction (LON:NMD). They have a £41m market cap, the share price is 422p, and the update today talks about an increase in PBT & divi's?
Peter
Sadly, some of us have to go to work and so a show starting at 5pm is hopeless. Even if the event was next door I'd not be able to make it.
Can't you flex your hours a bit? These events just won't happen up north if people don't make a special effort to attend them. Then everyone can go back to moaning that everything's in London, and how unfair it is. At least ShareSoc are making an effort.
I remember when myself and a friend went to an ENORMOUS effort & personal expense/risk (we had to guarantee the restaurant that 30 people would attend, out of our own pockets, and my friend bought a screen, projector, etc, personally) to arrange a couple of investor events in Brighton, for no reward. (and thank you to everyone who came along, they were great!)
Some moaning old git emailed me afterwards to say how he didn't normally eat as late as 8pm, as it upset his digestion, and how if I didn't change the time to be more convenient to him, that unfortunately he wouldn't be able to support the next one.
I sent him a reply basically telling him to FO and get a life, and I've not bothered organising any more similar events since.
P.
I will be there and it will be my first such event so am looking forward to it. Am particularly looking forward to hearing from NWF, as they are on my watchlist, and to hearing what smart questions other investors come up with!
Colin
Brilliant - great comment - you made me smile with that.
Many thanks
Hi Paul,
Many thanks for your report on AVG, interesting read and I agree its very sloppy to get the figures wrong.
I understand your concerns with visibility of earnings being a problem with some engineering companies , but in this particular case the management have done an excellent job in negotiating a number of long term agreements.
Hi Paul
Thanks for your daily insight
I hear exactly what you are saying re: the ShareSoc meeting. I do want to attend these but I'm afraid it's just too far to travel for me for an early evening presentation. Personally, it would be easier during the day or a half or full day or maybe alongside a wider programme and as such easier to justify an overnight stay. I will, however,
try to attend, I'm sure it will be an excellent event
I worked as a 'claims consultant' for the construction industry.
The problem that companies like NMD face is that, to get the Final Account agreed and paid, each and every dispute has to be resolved.
This puts the Contractor in the invidious position of having to concede sometimes quite large sums of money (which may be rightfully due) in order to get the account settled.
It's a tough industry so it's not one that I would want to invest in.
AVG
The 645k is the distribution costs. Coincidence?
NI
As I live in Altrincham, the link you provided was great and I will be there
AVG is probably a decent engineering company but providing components to problematic industries. Two of the three sectors it operates in are aerospace engines (Rolls Royce given several profit warnings and Boeing just announced it is to make less planes next year due to industry oversupply concern) and the oil and gas sector. Not sure that a company providing components to aerospace/oil and gas is one to have confidence in at present?
Great work on spotting the error - any comment from the AVG FD yet .... :)