Small Cap Value Report (18 Jul 2016) - ARM, BEG, MTEC, CTG, FIF, WJG, CVR

Good morning.
These seems to be a lot of turmoil & uncertainty at the moment, what with Brexit, and the associated sharp movements in forex. Then more recently another appalling terrorist attack on France. On top of that, we also saw what seemed to be an attempted coup by a faction of the military in Turkey on Friday night, with considerable bloodshed.
It seems to be the case that we're just having to get used to a more dangerous world - no level of security could be high enough to prevent every would-be attacker. It seems to me that attackers are fitting a pattern - loners, disillusioned with life, easily led, attracted to extremist ideologies, that are being radicalised on the internet. Our counter-measures, on top of improved security, surely need to be more covert surveillance, primarily of the internet activity of "at risk" people. Plus of course, finding, and imprisoning the people doing the radicalising.
Certainly the market seems to be becoming increasingly immune to geopolitical events. Although I can't help feeling that, after the strong recent rebound, this might be a good point to take some money off the table perhaps? Or maybe to hedge longs with an index put option, or index short (but only if you really know what you're doing, in terms of managing the risk).
I'm also becoming increasingly worried about what looks to be a looming Italian banking crisis, with some alarming statistics coming from good sources on Twitter, about the very high level of non-performing loans.
ARM Holdings (LON:ARM)
Recommended acquisition of ARM by Softbank - Counter-acting the gloom today, is remarkable news of what is apparently the largest ever investment in the UK by an Asian firm. Japan's Softbank is offering 1700p per ARM share, in an agreed cash takeover bid.
That's a 43% premium, and values ARM at £24.3bn. Remarkable stuff, and congratulations to holders of the stock.
Also note the stated intentions of the acquirer;
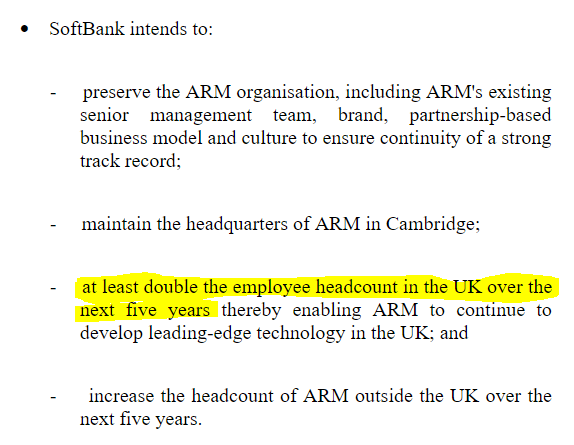
It should of course be borne in mind that acquirers do not always actually do what they previously stated an intention to do! So a bold statement of supporting & increasing UK investment & jobs would certainly help the deal go through without the Government putting any obstacles in the way.
However, if the above quotes are taken at face value, then it certainly seems like a very welcome boost to post-Brexit UK. Remember we were recently told by many supposed experts that inward investment into the UK would dry up if we voted Brexit.
A cash takeover of this size is likely to have a knock-on positive impact - investors and analysts are likely to be looking for the next UK target company for a foreign takeover bid. After all, sterling's recent fall makes UK companies with international earnings very attractive right now. So expect a lot more takeover bids for UK companies, from overseas.
Faisal Islam pointed out on Twitter today, that Softbank have been able to buy ARM £5bn cheaper, due to sterling's 21% fall against the Yen since the start of 2016.
Shares in other tech companies are likely to get a boost, as £24bn of fresh cash is likely to come into the market for other tech companies, once ARM shareholders have been paid out.
Begbies Traynor (LON:BEG)
Q2 Red Flag Report - I reported on insolvency practitioner Begbies Traynor last week. However, it's also worth keeping an eye on the firm's quarterly red flags report, which outlines the health of corporate UK, particularly smaller businesses. Trends spotted by Begbies can be useful background for us as investors.
Here are their key conclusions today;
Research shows British businesses are in a strong position to face Brexit challenges,but expect at least six months of turmoil ahead.
Levels of financial distress fell 4% ahead of the Brexit vote, but more than 240,000 SMEs still in a dire state.
UK Property and Construction sectors expected to bear the brunt of Brexit, with nearly 50,000 firms at risk
This ties in with other information I'm hearing, that apparently big scale new proposed construction projects are, in some cases, being put on hold. Although we've heard from housebuilders recently, that it's seemingly business as usual. Therefore I think it makes sense to steer clear of contractors and advisers to the commercial property building sector, for now.
That could have a knock-on effect too, pulling down support services companies facing the construction sector. So this area needs to be monitored carefully. Also we need to watch out for signs of a more general slowing of the economy, which seems to me very likely in H2 of this year. Whether it turns into a full-blown recession? Personally I suspect probably not, but that's based on generally quite reassuring updates from most companies so far. That could change of course, so vigilance and an open mind are critical for investors right now.
Matchtech (LON:MTEC)
Name change - I've decided to create an informal new award. It's called the "What on earth were they thinking?" award. The inaugural winner is Matchtech, who decided they need a name change, because after acquisitions, the group name doesn't fit well with the enlarged group, and has apparently caused some confusion.
Fair enough. So what is the brilliant new name for the group? It is "Gattaca". My first thought is that it sounds like the noise my Mini used to make in the 1980s, when I tried to start the engine on a cold day with a nearly-flat battery. After several gattacas, it would then progress to just a humming noise, and then complete silence after each turn of the ignition key.
Perhaps I've missed some significance of the new name? So I've googled it, and the page of top results all focus on a 1997 film called Gattaca, which was a box office flop, but achieved a low level of cult status. Its main theme is a future world where eugenics are used to improve the gene pool. Is this really a good message for a recruitment group to focus on? Perhaps the firm has become frustrated at low quality candidates, and is sending a message that it wants genetically superior candidates only?!
No explanation is given in today's RNS as to why the name Gattaca has been chosen, nor what it is supposed to mean. Shareholders are required to approve the name change - it will be interesting to see if they approve this bizarre new name or not.
Christie (LON:CTG)
Share price: 78p (down 9% today)
No. shares: 26.5m
Market cap: £20.7m
Trading statement (profit warning) - this business services group says that 2016 profits are likely to be lower than expected;
Christie Group plc (CTG.L), the leading provider of Professional Business Services and Stock & Inventory Systems & Services to the leisure, retail and care markets, announces that in the light of softer than previously anticipated trading in its Professional Business Services division, operating profit for the year ending 31 December 2016 is likely to be lower than previously expected.
OK, so what has caused this softer trading? It sounds as if Brexit uncertainty may have had some impact on transactions;
Within its Agency business, a small number of transactions were lost upon announcement of the European referendum result, after which point the business sales market is continuing its function.
I don't understand what they mean by "after which point the business sales market is continuing its function". What the hell does that mean?!! At a guess, I think they're trying to say that things are getting back to normal, maybe?
The company gives a rough idea on likely revenues;
While our first half revenue to 30th June is expected to be broadly in line with the corresponding period last year, we anticipate a growth in second half revenues year on year.
So it doesn't sound like a disaster. What about profit though?
Nevertheless, after recouping the expected first half loss referred to by the Chairman at the June AGM, this growth in second half revenues is now expected to be insufficient to achieve the level of full year profit that was previously anticipated.
I didn't report here on the company's AGM statement on 15 June. However, looking at it now, it seems the company was expecting (not unreasonably at the time) a Remain vote, triggering an improvement in H2 trading;
"As I recorded in my statement in April at the release of our 2016 results, 2016 started quietly, but gathered pace in spring. Whilst progress has continued, we expect to record a first half loss. Thereafter, we reasonably anticipate a post-EU referendum acceleration of billable activity resulting in full year profitability. (NB. this is from a previous RNS on 15 June 2016)
So it seems that the Brexit vote has undermined this company somewhat.
My opinion - unfortunately, I don't yet have any revised broker forecasts, so can't really take this any further, as there's too much uncertainty over earnings.
Given that the company was loss-making in H1, then I wouldn't put too much faith on it necessarily performing much better in H2.
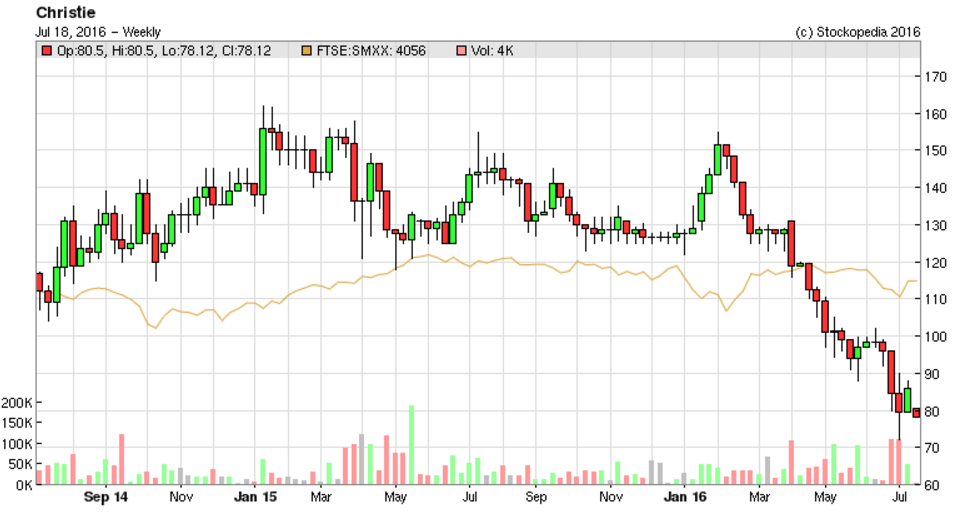
Looking back, profit here has generally been lacklustre, with 2 better years in 2014 & 2015. So perhaps we're now likely to see profits go back to previous more modest levels? That's what the share price seems to be telling us (see below).
I can't really see much attraction at all in this share, even though the price has halved recently. It is serving retailers, and the leisure & care sectors. These sectors are facing considerable pressure from Living Wage, and margin erosion (especially next year when forex movements will kick in, meaning higher input prices). Therefore a group providing professional services to those sectors is also bound to come under pricing pressure.
It's not for me.
Finsbury Food (LON:FIF)
Share price: 115p (flat today)
No. shares: 130.4m
Market cap: £150.0m
Pre-close trading statement - this bakery group has an end June year end, so today's update is for the full year just finished, and it looks solid;
The Board is pleased to report that, following the positive half year trading performance, strong trading has continued in the second half and the Group is confident of delivering profits in line with market expectations which were upgraded following the strong first half year.
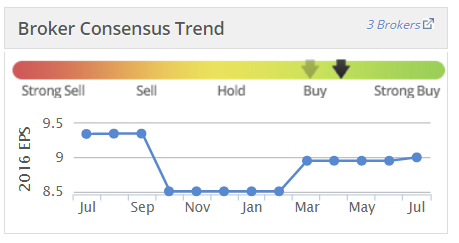
So in line, but with raised forecasts. So a decent result. Mind you, checking the terrific little Stockopedia graph for how broker consensus has moved over the last 12 months, forecasts were really only edged up back to a bit below where they had been previously;
Sales growth has benefited from acquisitions. However, note the decent organic growth of 5% too;
Total Company sales revenues grew to £319.7m, an increase of 24.8% on prior year (for the 52 week period, sales revenues were £313.5m, an increase of 22.4%), following the successful integration of the prior year acquisitions of Fletchers and Johnstone's.
This includes like for like growth of £12.8m, an increase of 5.0% versus prior year. The UK Bakery division grew by 3.0% on a like for like basis and the Overseas division, the Group's 50% owned European business, grew by 25.7%. Our sales to the foodservice channel accounted for 21% of total UK Bakery sales revenues and grew by 5.3% on a like for like basis.
Brexit comments don't really tell us much, but they don't sound too worried about it, which I find encouraging;
Whilst it is too early to fully understand the impact of the exit of Britain from the EU, the Board believes that as a strong multi-channel business and a large diversified speciality bakery group, it is well equipped to manage the potential effects of this outcome and continue to deliver growth and improved shareholder value over the coming years.
Outlook comments are vague, but with a clearly positive tone, e.g.;
"This growth is underpinned by capital investment and our continued focus on innovation, maintaining our position as one of the UK's largest speciality bakery groups. More than ever we are well placed to continue our solid performance and drive growth."
This sounds like a business on a roll (geddit?!)
Valuation - looking at the Stockopedia graphics, the current valuation at 115p per share looks about right to me, for now;
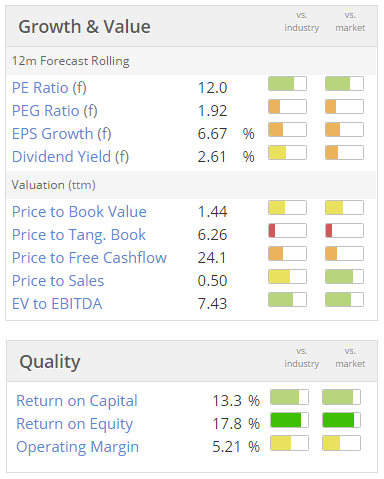
My opinion - this seems to be a well-managed group, which is growing well, despite what must be considerable pressure from customers to erode their margins.
The trouble with groups which grow by acquisition, is that the balance sheet can be degraded, with intangibles piling up at the top, and debt piling up at the bottom. So far, FIF seems to have kept its balance sheet fairly sensible, although it's not as strong as I would ideally like.
This is the sort of share that I would certainly have on my shortlist to consider for a long-term buy & hold type of portfolio. So overall, a thumbs up from me, but I'm not really seeing any immediate compulsion to buy any.
Watkin Jones (LON:WJG)
Video of recent Mello Beckenham meeting - this is the company which presented at Mello last week, which I attended. Management came over really well, and it looks a very interesting company.
If you were not able to attend, the presentation was videoed by my friends Tamzin and Tim at PIWorld.co.uk (a terrific website, with in-depth video content on mainly good quality companies). Here is the link. It's a long video, but if you're going to risk thousands of pounds on a share, then I suggest it's time well spent to watch a video like this.
The format at Mello is to have a company presentation or two, and then we go downstairs for a nice meal & everyone can chat about the companies we've just met. Very friendly & enjoyable evenings, I must attend more in future.
I should add that we had a long Q&A session after the formal presentation, and the Directors spread themselves around the room afterwards for dinner, so everyone had a chance to ask all the questions they wanted.
I'll sign off for now. Possible update later for one more company, will Tweet if I get round to it.
Regards, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

70 comments
Following up from yesterdays Berenberg comment.
Results.
ARM Holdings reported a rise in pretax profit for first half of 2016, helped by strong growth in royalty revenues, as the UK computer-chip designer continued to gain market share and benefited from greater take-up of its products.
Last week, ARM agreed to a GBP24.3 billion takeover by Japanese telecommunications and technology conglomerate SoftBank Group Corp, in what it called a “great deal for the UK”.
ARM on Wednesday reported a pretax profit for first half of GBP208.0 million, up from GBP198.1 million a year before, on revenue of GBP544.1 million, up from GBP456.0 million
ARM Holdings boosts revenue and profits as takeover beckons
http://www.proactiveinvestors.co.uk/companies/news/128674/arm-holdings-boosts-revenue-and-profits-as-takeover-beckons-128674.html?
ARM sees profits rise ahead of takeover by Softbank
http://www.ibtimes.co.uk/arm-sees-profits-rise-ahead-takeover-by-softbank-1572750?
Interesting comment vis ARM this morning.
Downgraded to HOLD.
""This is our bull-case scenario price target and thus we move the rating from buy to hold," the bank said."
""Prior to the deal announcement, we believe that sentiment was quite negative on ARM on the back of a slowdown in smartphone volume growth - and ARM was yet to see significant demand for its chips from the server and networking market."
http://sharecast.com/news/berenberg-downgrades-arm-as-it-lifts-price-target-to-reflect-softcat-deal/24731776.html?
So bid at a decent premium a fair reflection of both current position, and risk/rewards going forward.
Still, it's only Berenberg so pinch of salt time
If people think the takeover price for ARM is so cheap, there's an easy solution: bid for a blocking minority (25% it seems) at 1701p. This is certainly affordable for a coalition of UK institutional and private investors.
Personally I think people overestimate the value of ARM IP, ignoring several headwinds such as antitrust pressures in smartphones now Intel has dropped Atom, and open source CPU designs (see RISC-V) at the Internet of Things end where performance is not a major issue and zero is the best budget for CPU IP, as well as overestimating the addressable market. I wouldn't be surprised if Softbank has to write off some of the ARM goodwill a few years down the line (if the deal does get through).
Simoan
What to do about Arm. That's the question! What we need is an E petition, but I need at least five Email addresses to set one up. If you or anyone else would like to help stop this sale by urging the Government to look again at this loss to Britain's intellectual property please contact me on davidcox123dc@gmail.com
For anyone interested, there is what I consider to be a well-informed discussion about the proposed takeover of Arm on the Motley Fool website:
http://boards.fool.co.uk/takeover-13405459.aspx?sort=whole#13406414
Interesting comment here that Brexit has perhaps led to SoftBank having to actually pay a HIGHER price in yen to buy ARM Holdings (LON:ARM):
(WARNING FOR SENSITIVE SOULS: THIS IS CUT AND PASTE!)
"If you squint enough, it’s also possible to paint SoftBank’s acquisition as an opportunistic post-Brexit plot to cash in on the falling pound, although it’s not a claim that stands up to much scrutiny: ARM books its sales in dollars, meaning sterling’s fall has boosted its share price to the extent that the deal was more expensive in yen terms than it would have been before the vote."
http://www.telegraph.co.uk/technology/2016/07/19/arms-sale-is-not-a-national-tragedy/
The comment makes sense. The ARM Holdings (LON:ARM) share price went up sharply post the referendum since the company is a beneficiary of the US$ increasing in value against sterling and thus its US$ earnings are now worth more in sterling. That increase in its earnings and its share price was much greater than the effect of the yen becoming stronger against the pound.
So blaming Brexit for the takeover by the Japanese, as many here have been doing for the last two days, is incorrect. Without Brexit, they would quite possibly have been able to buy and would have bought ARM Holdings (LON:ARM) for a much lower price in yen.
(PS: That perhaps also makes the takeover an even greater vote of confidence in a post-Brexit UK).
Well the £ has fallen about 1/3 against the yen in the last year, the sudden fall after Brexit may have been the spur, yes ARM shares are up about 10% after Brexit.
Softbank's shares are down 10% today.
ARM Holdings (LON:ARM) was at 1019p on June 23 and then 1189p the day before the bid. I make that an increase of almost 17%.
SoftBank shares are well down today because the Tokyo market believe they have paid well over the odds for ARM Holdings (LON:ARM).
I think the shares fell because of even more debt its taken on. It was just getting on a better credit rating as it has sold off a load of shares, now this £24bn take-over has not gone down well. http://www.standard.co.uk/business/softbank-dives-as-arm-deal-raises-doubts-over-debt-pile-a3299201.html
This does assume that ARM Holdings (LON:ARM) share would not have gone up if we voted to stay in the EU. I think that unlikely I would have expected there to have been a rise in share prices. And the £ would have gone up also.
Whatever.................
(Sorry, Herbie, but speculation and whatifery is not my thing,
that's why I'm usually careful to say "perhaps" or "possibly",
so as to avoid the forceful but very tiring dogmatism I see so
much of as people try to impose their views on other people)
Jane, SoftBank's takeover bid for Arm might not be due to Brexit. However, Arm is a financially very strong company, with a lot of cash on its balance sheet, so I believe that it could fund increased expenditure on research and development and on recruiting new employees from its own resources, whereas SoftBank has enormous debts. This means that if things become difficult in SoftBank's other businesses in the future, it might use Arm as a cash cow to help pay the interest on SoftBank's huge debts, which would starve Arm of resources for R&D. It is even possible that SoftBank might go bust. Why should the government risk the future of the jewel in UK industry's crown by allowing this takeover?
Ask the UK Government that, not me.
UK industrial strategy is not for me to comment on.
I was simply commenting on this takeover having been depicted by many on here as the "jewel in the crown" being lost "because of Brexit".
It amazes me that private investors, who cherish the right to buy shares in whatever quantity they wish in whatever company they wish (with as low a spread as possible), should have the brass neck to complain when a company comes in, quite openly, to offer to buy ALL of the shares in a successful business at a substantial premium to market value. No existing shareholders are obliged to sell, this is just a market offer. What's to cry about?
If the UK Government regards ARM Holdings as a strategic company for the UK, then it should outbid Softbank on a market basis. If not, then too bad.
How much of our world-class expertise are we to sell abroad? Would the French allow it? I rather doubt it.
I'm puzzled by Theresa May's stance on the ARM Holdings (LON:ARM) takeover, she recently said "There was a call for the government to take more powers to block predatory takeovers of key companies — citing Kraft’s takeover of Cadbury and Pfizer’s failed bid for AstraZeneca"
So ARM is not a key company then?
@PhilH,Pka,
Thanks for the interesting comments.
Do either of you believe that such FDI into the UK should be discouraged in this instance? Some believe the price is too low, others that it shouldn't be allowed at all - ie Protectionist stance should be taken here and the takeover prevented.Presumably this holds for another buyer as well..
Fangorn,
I refer you back to Simoan's analysis of the impact of Japanese ownership on potential growth markets and invite you to consider if you think it's more or less likey to have a positive or negative impact on the proposed doubling of the workforce?
Phil,
As well as there being potential negatives ("sino-japanese context") there could equall be potential benefits surely?
Ultimately the question is hether we want FDI or not - we can't pick and choose unless a clear national interest claim can be made. if it were BAE, Glaxo such a case could be made. It's ARM - said protectionist case would be a tad flimsy imv.
As to the doubling of the workforce. That's surely a benefit in itself no?
Of course the intention to double the workforce is great but that's all it is ... a stated intention.
With respect to significance of ARM I wouldn't be at all surprised if they have a relationship with the UK Security Services. The Internet of Things has the potential to be a Spooks dream. Imagine a fridge telling a spook that it had just been opened potentially highlighting the active use of a place of interest.
So that might also be another angle in which to consider national interest.
Think I'm getting a bit carried away? Skype changed the way in which their encrypted calls were routed a few years ago, switching from a peer-to-peer approach to routing it via central servers. Microsoft (Skype's owner) also tweaked the user agreement wrt privacy and as such I could no longer guarantee to confidentiality and privacy to my online counselling clients.
My view was that the NSA/DoD told Microsoft to do it so they could monitor Skype calls and told them not to talk about it and so Microsoft couldn't explain why they'd changed the setup.
So having key technology in the hands of your own jurisdiction can be very advantageous and it being in the jurisdiction of a hostile country can be be very detrimental.
I don't know enough about the field to be able to give an opinion on ARM.
"Isn't such "design & license" practised by many globally?"
No - Arm is unique in that it is a world leader in the design of low-power consumption chips with relatively long battery life, and it is much cheaper for over 100 other electronic companies to licence Arm chips in their devices rather than spending expensive resources and time trying to design their own chips.
I see the selling of Arm as an unmitigated disaster for Britain. Anyone believing that the intellectual property that Arm possesses will not find it's way to Japan is deluding themselves. I couldn't believe the new government of Mrs May after all she said about foreign takeovers endorsed it so rapidly without seemingly any real thought about it's implications. You only have to look at what happened to Cadburys to know that promises mean nothing. What we need now is keep our advantages in technology. Not sell it off to make a few people rich in the City. In fact a new mindset of long term investment, not short term gain. I hope naively that shareholders will vote against it and the rest of us will kick up such a fuss that the government changes its mind and puts a stop to it before its too late.
David,
Well said! I have heard so much rubbish over the past 24 hours based purely on the complete lack of knowledge of what ARM represents. It is not a chip maker, it is not even a chip designer, it is an Intellectual Property licensor and the Japanese have just acquired 25 years of key British intellectual property on the cheap. I find it amazing that so few people understand this. There is also such a lack of understanding of the ARM business model that people think Intel, Samsung or Apple would be able to buy ARM when in fact this is not possible and will not happen.
I was thinking last night that if there really was to be a proper "industrial strategy" what should happen next in response to this is:
1) The UKFI sell off all the governments remaining shares in crappy Lloyds and RBS.
2) The UK Government uses the £24bn proceeds to buyout ARM shareholders at £17 pps and use the company as the first investment of a new post Brexit UK Sovereign Wealth Fund.
Not a chance of it happening of course being far too enlightened an approach. It seems crazy to me that old industry companies like Rolls Royce are protected by the government and yet one of the top global companies at the forefront of the digital economy is not. Warren East has been CEO of both and I would be interested to hear which company he feels is the most important to the future of the UK economy... I think I know the answer.
All the best, Si
The bid for ARM Holdings (LON:ARM) is at a price that is 47 times forecast 2016 earnings and over 70 times FCF.
I don't pretend to know or understand the industry and have never held this stock. There is speculative talk of this bid not being the last and yes, it's a great company but, seriously, who would turn that bid down?
Hi Jane,
Yes, if you take a very short term approach using conventional valuation metrics it looks expensive. However, it is easy to look at the small picture and completely miss the larger picture which is what is happening.
Of course, it would look even more expensive if ARM loses business as a result of this takeover which is entirely possible. As an example, one of the key growth markets for ARM is China and whilst the Chinese may be perfectly happy to license IP from an independent ARM as a UK company, I believe they will be far less interested in dealing with part of a Japanese company, which is in effect what ARM will become.
At the moment ARM's licensees have no motivation to use anything other than ARM IP in their chips. However, this ceases to be the case once it loses it's independence - this is the poison pill that means Apple and Samsung are very, very unlikely to buy ARM. Of course, Intel cannot buy ARM either because they will be hauled up before every competition authority in the world.
All the best, Si
Simoan,
"David,
Well said! I have heard so much rubbish over the past 24 hours based purely on the complete lack of knowledge of what ARM represents. It is not a chip maker, it is not even a chip designer, it is an Intellectual Property licensor"
Rubbish is it?
How do you explain
"They would never have even dreamt of allowing a company that makes chips for iPhones to be bought by foreigners"
http://www.telegraph.co.uk/business/2016/07/18/forget-protectionism-may-is-right-not-to-veto-arms-foreign-takeo/
Japan's SoftBank to buy iPhone chip maker ARM in £24bn acquisition of Britain's biggest tech company
http://www.telegraph.co.uk/technology/2016/07/18/japans-softbank-to-buy-arm-holdings-in-24bn-acquisition-of-brita/
Shares in Imagination Technologies have jumped 12.75 per cent this morning after its fellow UK chipmaker Arm Holdings was acquired by Japan’s SoftBank in a £24.3bn deal.
https://next.ft.com/content/caa155d2-3af0-3469-adbb-14b6def94444
Plenty of reference everywhere to ARM being a chip maker...
But then you know better thann everyone else don't you!
"There is also such a lack of understanding of the ARM business model that people think Intel, Samsung or Apple would be able to buy ARM when in fact this is not possible and will not happen. "
Why is it not possible then? Simple case of opening the cheque book surely as Softbank has done. ARM is listed after all.
"1) The UKFI sell off all the governments remaining shares in crappy Lloyds and RBS.
2) The UK Government uses the £24bn proceeds to buyout ARM shareholders at £17 pps and use the company as the first investment of a new post Brexit UK Sovereign Wealth Fund."
So you want protectionism clearly.That,surely,is the slippery dlope down which a economy flounders to its ineviable destruction?
"Not a chance of it happening of course being far too enlightened an approach"
Not a chance of that happening because it's simply not eminently sensible at all.
There's a reason BAe & Rolls are protected, and ARM is not. Go do some research and you'll work out why.
If you don't work in the UK Defence/Aerospace sector you will never understand why companies in this sector are considered strategic whilst Arm isn't.
I won't be commenting any further.
Fangorn,
Perhaps you should get your information from reliable sources??
From ARM's website ...
Perhaps you should concentrate on the topic rather than rubbishing the provider of a clearly more informed perspective?
Best of luck
Phil
Hi Phil,
This is my area of expertise and what I do for my day job. I have spent the past 30 years working in the UK semiconductor and electronics industry and so would like to think I know what I'm talking about more than most. I don't mind people disagreeing but its not possible to have a constructive discourse with some people and so it's best avoided for the good of Paul's blog.
I worked with ARM before they were listed in the mid 90's, I have visited the company on a few occasions and even held discussions with their original legal counsel a few years ago, so I'm very familiar with what is happening here. There is a good reason why people that understand the company are so distressed by this turn of events and others, including the UK Government, seem more sanguine about it. It's just a fact we have to live with these days that people know the price of everything and yet the value of nothing.
All the best, Si
Phil
"ARM's main CPU competitors include Intel and AMD for servers,[22] and the former on mobile with its Atom chips and the latter also sells ARM-based chips[23] in addition to competing with x86-based chips;"
What are these "ARM based Chips" then? I didn't say ARM was exclusively a chip company,but a chip company it surely is...selling the microprocessor technology it creates via licence?
Nor did I profess to have an expert knowledge - hence my questions. What I take affront at is Simoan's continued looking down his nose at my comments because I have the temerity to disagree with him on any topic. He lost the Brexit vote yet was a notable vocal supporter of FDI,and how it would negatively be impacted by us leaving. Now we have FDI, it's the wrong sort! Laughable frankly.
My point was I dont think ARM is strategic,therefore not worthy of protecting in the national interest which is where part of his issue with me lies. This,in addition to our dialogue over the Brexit period of course.
Fangorn, Unfortunately you have been misled by the ignorance of the sub-editors and journalists who write the titles of newspaper articles, who do not understand that Arm is a chip designer and is not a chip maker. Arm Holdings does not make chips - it does extensive research and development and designs chips, keeps the intellectual property of those designs, and licences them to many other electronic companies who manufacture chips from those designs and/or use them in a multitude of electronic devices.
PKA,
So it's a Chip company essentially, but only designs & licenses said "new creation" rather than manufacturing it themselves.
Thank you for heads up.
Isn't such "design & license" practised by many globally? Are such companies overseas protected by their host governments?
Thanks in advance
Nope even pka's description is incorrect. They license intellectual property that can be incorporated into the designs of chips developed by chip manufacturers.
An analogy would be that I produce iP around fuel tanks that can be incorporated into the design of a fuel tank that is then built into cars. In that case I don't build, design or manufacture fuel tanks or cars.
hI Paul,
Your heading mentions CVR - don't see your comment about it. Has it slipped out?
A key to whether or not the UK benefits from an ARM takeover is what happens to the money. Presumably a significant amount goes to foreign holders but the enormous amount held for potential re-investment in the UK could have a very favourable outcome.
It is not often realised that the holding Apple had in ARM (initially 30%) was so valuable that at the time of ARM's float Apple's share in the company exceeded the market cap of Apple itself - so you could have bought Apple's own business for less than nothing!
Apple then sold this "family silver" over several quarters, stabilizing its financial position and setting up its investment in IMac, the iPod and so on...It would have made enormous gains by holding on to the shares but they would have been trivial compared to what Apple did with the money.
Sorry Aislabie I thumb downed by accident.
Hi Paul
You say that you are becoming increasingly worried about Italian banks and their non performing loans, well below is a snapshot of various countries Banks non performing loans in 2015. From World Bank site.
No doubt the EU will fudge the situation and provide some support until the next time when their situation will be even more precarious. Italy is a country where there has been zero growth in GDP since 2008 and at the same time has seen its debt to GDP balloon to 140%, and still increasing.
Non performing loans 2015
Canada = 0.5%
UK = 1.4%
USA = 1.5%
Netherlands = 2.7%
Germany = No data
France = 4.0%
Spain = 6.3%
Italy = 18%
Greece = 34.7%
As I bought ARM just over a month ago for 979p I am very pleased with my gain. However, this got me thinking of the relevance of the so called 21% saving due to the drop in sterling against the dollar since the start of the year. As ARM has also benefited from the drop. ARM could be bought for 960p last month and if a 43% premium was offered then that would equate to 1372p which is 19.3% less than 1700p. Furthermore, back in early February when the price was 860p the saving would have been 28%. The drop in the rate of the pound will only give a bargain for foreign takeovers if the share price has either dropped also or hardly changed.
I have held ARM shares for less than a year but would have been a shareholder for longer had I known more about ARM at an earlier stage. I did some research this morning seeking another company benefiting from the "internet of things" to redeploy the money. Unfortunately I have not been able to find any company in the UK with the same high quality as ARM (please let me know if any suggestions!) but I have now reinvested some of the money in the US company, Linear Technology. Linear is growing more slowly than ARM but is a high quality business with remarkably good ROCE and a major beneficiary of the "internet of things". Quite a few differences from ARM, but the financial characteristics are just as appealing to my conservative philosophy and the risk to reward ratio is probably lower than ARM.
If it's not an investment why are they adding an EXTRA 000 jobs into the bargain?
"unless of course you consider someone walking into the Tower of London, taking all the crown jewels and leaving a £20 note in their place an "inward investment"? "
How's that analogy even representative of what we have here. Would you have been happier if say Intel had purchased it?
Facts are -
UK needs FDI. This was a point pushed by Remainers.
Arm isn't strategic
Softbank will employ an extra 5000 jobs (That's investment surely and good for Cambridge?)
"ARM is very strategic to the UK technology sector and anyone that does not see it does not know what they are talking about"
Enlighten me as to its strategic value then.
ARM makes chips for Apple & Samsung - so does IMG.
How is it strategic, exactly.I'm all ears.
"If you don't work in the UK technology sector you will never understand what a terrible day this is. I won't be commenting any further."
Why is it whenever I challenge you or you contradict a viewpoint of mine you always conclude thus after your first response in an attempt to stifle any further discussion.
I'll ignore the consistent disdain and looking down your nose that you exhibit whenever responding to any remarks I make btw.
I'm genuinely interested to learn why you think ARM is strategic - its a semi conductor company. They're dime a dozen globally aren't they, mostly in Taiwan.
ARM Holdings (LON:ARM) is unique in four ways. Firstly its brand of low power processors are uniquely suited to mobile devices. Secondly their low capital licensing model allows them to scale without significant investment. Thirdly, their deep integration with the processor fabricators makes them extremely hard to replace, because of the third-party investment in ARM specific processes. Finally they are the UK's only global IT corporation unless we count Sage (LON:SGE), which is a markedly different proposition.
The company's strategic importance is due to the fact that it's a technolgy hub, generating and throwing off earnings, attracting and spinning off highly skilled technologists and operating as a centre of excellence in a very specialised area. Perhaps the automotive hub in the West Midlands or the fintech hub in London may come to rival this, but at the moment it's pretty much beyond compare in the UK. Quite why that is, is a much bigger question to do with individual aspiration and the nature of the capital markets in the UK.
But comparing ARM Holdings (LON:ARM) with Imagination Technologies (LON:IMG) isn't really fair - ARM generated nearly a billion in taxable earnings last year, while Imagination are still loss making.
My biggest concern with the acquisition is not that ARM is being sold to an overseas buyer, it's that the price is far too low. Softbank are claiming that this is nothing to do with sterling's post-Brexit lows, but choosing to pounce at a multi-year sterling low against the yen is far too much of a coincidence for that to be true. This kind of deal isn't done opportunistically, they've been looking at it for months, if not years.
The issue with this sort of inward investment, is that if the purchaser runs into problems then they'll favour their home markets, and squeeze overseas funding. Softbank's financial position isn't especially secure, so the risk is that rather than investing they'll actually use ARM's revenues to shore up their position.
On balance, I don't think that's likely. It would be hard to pull ARM's unique brand of IPR out of Cambridge without suffering a major loss in intrinsic value, and the IoT investment target is credible. But carrying $70 bn in debt before buying ARM is (to use a Buffett analogy) akin to driving around with a dagger strapped to your steering wheel. You really can't afford to hit any potholes. If they do the UK is likely to suffer.
But my problem with this is that the price isn't right. This is relatively risky inward investment on the cheap, and it won't be the last such example.
timarr
Nicely written and balanced piece Timarr.
Thank you for your reasonable and well mannered reply Timar, in stark contrast to the rant of the other individual that seems to have a bee in his bonnet still..
Grateful for your synopsis of ARM's activities. Despite ARM being very profitable, generating as you say, a billion in taxable earnings, am I correct in concluding that Imagination tech is similar, has similar CPU/Chips but just isn't as advanced or capable as those that ARM churn out? They are both very reliant on APPLE aren't they,as well as other Phone manufacturers such as Samsung?
"My biggest concern with the acquisition is not that ARM is being sold to an overseas buyer, it's that the price is far too low"
We share similar sentiments in this regard then. The problem with some people is that they want to have their FDI cake and eat it. One assumes if ARM is so cheap, another potential purchaser might step into the fray, perhaps a USD based one?
"This kind of deal isn't done opportunistically, they've been looking at it for months, if not years."
Absolutely. It's now that much more affordable given Sterlings fall - but the underlying strategic sense behind their purchase isn't new, therefore this isn't an opportunistic bid based solely on sterlings weakness.
Concur that it also wont be the last foray of foreign companies. But isn't this FDI what Remainers wanted,and said wouldn't happen due to Brexit?
As to their strategic importance -
"The company's strategic importance is due to the fact that it's a technolgy hub, generating and throwing off earnings, attracting and spinning off highly skilled technologists and operating as a centre of excellence in a very specialised area"
Whilst I can see some merit, like yourself, I don't believe this merits a Govt kaibosh on the deal on grounds of national interest.
Interesting article in telegraph as well today commenting on this...
"Forget protectionism: May is right not to veto ARM’s foreign takeover"
To her great credit, the Prime Minister hasn’t blocked the takeover of ARM, a giant of British technology, even though the buyer is Japan’s SoftBank and despite the fact that this is the kind of transaction that will horrify protectionists and economic nationalists.
http://www.telegraph.co.uk/business/2016/07/18/forget-protectionism-may-is-right-not-to-veto-arms-foreign-takeo/
ARM Holdings (LON:ARM) was a potential takeover target for many years. Indeed I was long last year purely on the belief that they would be taken out. Rumours always pointed to large techs from the US, such as Intel, never thinking that a predator would materialise from the left field.
Unfortunately I kitchen-sinked my holding in January during the correction hiatus, so this is one fish that got away.
I am bemused about people blaming Brexit for this takeover. UK's free market economy has always been open to companies from any part of the world buying up UK firms. Brexit or not, this has and will always be the case. What has changed since the referendum is the £ being some 15 - 20% cheaper. It looks like the Japanese were quicker at pulling the trigger than some of the competitors from the US.
As an aside, I remember Hermann Hauser of Acorn Computers fame. A true pioneer who brought the world of computing to the ordinary public.
I'm not sure that "blame" is the correct phrase, but given that the UK has just entered a period of considerable economic and political uncertainty it's very hard to believe that the acquisition of ARM Holdings (LON:ARM) isn't related to the company being at a multi-year low price in yen terms. Perhaps a better phrase would be "unintended consequence"?
I would be very surprised if this and the (considerably less strategic) takeover of Poundland (LON:PLND) don't turn out to be the tip of the iceberg, and it's certainly one of the things I've been positioning for since the EU Referendum vote. Currently the UK government has almost no power to stop M&A of this type so Theresa May's announcement that this is one of the things her government will be looking at is likely to force potential acquirers into action. Another unintended consequence, no doubt.
As for ARM Holdings (LON:ARM) well, yes, it's a shame but realistically they were a sitting duck. The risk here is that Softbank are unable to meet their commitments to inward investment; they're already selling off stakes in other ventures to pay down their debt and their track record is patchy. But given how strategic ARM Holdings (LON:ARM) is to Apple I doubt this is done yet.
timarr
Fair comment.
ARM - mixed feelings, but I haven't looked at the figures and I cannot judge whether it's a good deal for shareholders or not. Setting aside any matters other than the investment case, I suppose, being in cash, it must be. The reason that so many such deals go through in the UK is because the top management are hugely incentivised to accept. Japanese management are usually not incentivised in the same way and cross shareholdings with other Japanese companies usually block any takeovers - but most Japanese companies are not run with placing any kind of priority on shareholder value (or even on profitability), so it's hard to find attractive investments in Japan.
Masayoshi Son, founder and CEO of Softbank is, however, an outsider - as a US-educated, ethnically Korean Japanese, he is hardly part of the establishment, so this is more akin to a Silicon Valley tech buyout, in my view.
While my instinctive preference is to see ARM taking over other companies, I am still optimistic - some people will leave, others will be inspired by the outcome and many new technology companies will be established in the wake of this, some of which will thrive and grow, supported in part by the profits made as a result of ARM. Cambridge seems to be that kind of place.
B2V
"Perhaps the firm has become frustrated at low quality candidates, and is sending a message.."
Matchtech's Twitter is usually pushing messages towards female candidates - don't know whether they're easier to place or not, possibly they are as companies do a bit of virtue signalling with their hiring policies. It's certainly true in academic science hiring. However Gattaca is not, if I remember, a women's picture, though it did have Ethen Hawke on a treadmill.
I hope there's not a gleaming new corporate HQ to go along with the new name.
"ARM has been the proudest achievement in my life and so it's a very sad day for me personally and for technology in Britain."
– HERMANN HAUSER, ARMS FOUNDER
– HERMANN HAUSER, ARMS FOUNDER
For the record Hermann Houser is a co-founder of ARM. I'm sure he won't mind me pointing out he had plenty of help in building ARM from a small bunch of engineers into the incredible company it is today. He's had plenty of VC money to invest in the years since with Amadeus and he hasn't come anywhere close to creating anything like ARM again, so I fully empathise with his sentiments. I imagine he and his colleagues are absolutely gutted even if they maintain large personal shareholdings. If this is the first casualty of Brexit then it has already been a very bad thing for the UK. apart from anything else the idea you can suddenly double a company like ARM in a few years is fanciful... the skills do not exist in the UK and we are about to make immigration of the required skilled EU workers much harder. What total stupidity!!
I don't expect Theresa May to understand how important ARM's technology is to the UK technology sector but she is clearly being very badly briefed indeed. If she thinks it's a good thing that ARM's technology is sold to a highly indebted Japanese conglomerate then it's the first sign that the new government is just as inept as the last one.
As Paul Weller once said, "Dig the new breed, same as the old breed"
Si
Simoan,
You want to continue to get foreign investment into the UK right - so stopping Softbank's acquisition, whether it be opportunitistic,or part of a more long term expansion facilitated by sterling's recent depreciation, will hardly send the right signal surely?
Yet this is what you seemingly call for with your
"ARM would have prospered very well without being bought by Softbank and yet more UK developed technology will be in the ownership of a foreign company. This is not a good thing despite what people are saying and it's exactly the kind of thing Theresa May should be stopping if she is going to be true to her word."
ARM is hardly strategic though. I'd be more concerned with a foreign buyer aiming for BAE, Glaxo, or the like personally. Despite being pro privatisation am not a fan that most of the electricity/utility sector is foreign owned.
Unless the target is clearly strategic, in which case there are "acceptable" grounds to block said approach, you can't have your cake and eat it. Either you want FDI or you dont.
This is not an investment in the UK and only a mug (or politician) dresses it up as that... unless of course you consider someone walking into the Tower of London, taking all the crown jewels and leaving a £20 note in their place an "inward investment"?
ARM is very strategic to the UK technology sector and anyone that does not see it does not know what they are talking about. There is no way the Americans would let this happen if ARM was a US company. If you don't work in the UK technology sector you will never understand what a terrible day this is. I won't be commenting any further.
Si
reckon we violently agree, Hammond's spin on FDI is not my take. A discounted foreign takeover is hardly greenfield and doubling a small UK workforce to around 3000 is no reason for joy...that would happen organically and be sourced from our own human capital irrespective
This is a jewel pawned to a Shylock and a great example of the oxymoron of "Take Back Control" in a globalised economy
Take-0ver History is littered with disasters caused by hold-outs.
The company retains its independence, then the market changes and the share price crashes.
Three examples spring to mind. Lord Sainsbury asked 6 pounds from the Quatar Investment Fund. Would you accept 5,95 for SBRY today?
Mouchel was blocked by Schroders and later had to file for bankruptcy.
Potash in Canada was offered 100$ a shares by BLT. Some influential investors persuaded the Govt to block it. Then the Russian potash price cartel collapsed. Check out the price of POT today.
Nationalism is dangerous. The co-founder of ARM has a german name and these nationalities will now have difficulty getting into England, let alone start a company.
I thought Gattaca was a Battlestar from the 80's not a Mini..
I have been a holder of Arm Holdings for 17 years and was intending to hold it forever. I hope this takeover fails, because a 40% increase in the share price today is insignificant when compared with the likely future growth of this company and its share price if it remains independent. It is one of the few companies in the UK stock market that is both a world leader in its field and is enormously profitable. According to the Stockopedia statistics, Arm's return on capital employed is currently a fantastic 21% and its average annual earnings per share growth over the last 6 years has been a phenomenal 37%. If the takeover does go ahead, it will be another testament to the short-termism of British investing institutions.
Hi pka,
I'm not an ARM Holdings (LON:ARM) holder (though wish I was - it's a company I've admired for many years...just shows, sometimes you should just pay up for the best companies), but fully agree with your sentiments here.
A 40% premium in cash is bound to be hard to turn down - but I agree that it is likely to be leaving a lot of performance on the table....
If shareholders vote for this I agree that it has a good possibility of being very short sighted.
Thanks Paul, after some deliberation I have taken the profit on ARM today. Should I have waited longer? Who knows but as it had already risen by 42% today I felt it best to sell now. A total profit of 80%.
Charles
"It should of course be borne in mind that acquirers do not always actually do what they previously stated an intention to do".
A fair comment when you consider the likes of the Kraft/Mondelez takeover of Cadbury . Japanese companies and people are generally a very honourable lot, so I would imagine this is their genuine intention.
Paul, Brian Wilkinson of newly rebranded 'Gattaca' was on here this am., mentioned name change I believe....https://www.shareradio.co.uk/
PS Im now looking for someone to come in and buy Lavendon (LON:LVD) for at least a 47% premium. After all it has lots of earnings abroad, it has a much lower PER than ARM Holdings (LON:ARM) and is even cheaper for foreign buyers now that the £ has fallen! Wishful thinking?
Re your comment on ARM Holdings (LON:ARM) Paul. I wonder if it woild ahve been possible for a UK company to have bought ARM Holdings (LON:ARM) if it had been a Japaneses company? Also, do you think that will be the end of it or do you think that someone else will come back with a counterbid. After all, everyhting ARM Holdings (LON:ARM) seems to touch turns to gold, and you can never hav too much of that can you - except in a bull market!
Thnak you for your pattern of introductory comments recently. Always thought-provoking anf often informative.
Paul, I see Finsbury Food (LON:FIF) issued a trading update today which looks very good.
Sure it's nice to see inward investment in the UK especially post Brexit, but it's not so good to see surely the UK's brightest technology star being bought up by a foriegn investor, sure they're saying all the right things now, but what will actually happen when things start to get tough, as inevitably they do at some point for any company?
It didn't seem that arm needed more clout, or more backing, they seemed to be progressing nicely by themselves, I suspect Intel will in the future regret not having struck first.
I say the above as someone who's a quiet recent but small share holding, so I've had a little windfall,
still this is modern life, it seems that despite Brexit, international companies might be more interested in the lower prices that a cheap pound offers.
K
Hi kenobi,
I couldn't agree with you more. This is a dark day for the UK Technology sector and particularly in the Cambridge area where I live and work. ARM is financially in a very good place and does not need the money or investment. For people to paint this as some kind of proof that "Britain is still open for business" since Brexit is just total nonsense, so the new Chancellor is already making himself look an idiot. This is purely a consequence of Sterling depreciation against the Yen and probably wouldn't have happened without it - it's pure opportunism by Softbank. I heard that they only approached ARM two weeks ago so this has all happened very quickly.
I should imagine a well-known Motley Fooler will have very mixed emotions today as he was one of the original founders of ARM. Obviously he's already pretty wealthy but must feel pretty sore that the baby he started with a bunch of others back in the early 80's is being taken from him prematurely. ARM would have prospered very well without being bought by Softbank and yet more UK developed technology will be in the ownership of a foreign company. This is not a good thing despite what people are saying and it's exactly the kind of thing Theresa May should be stopping if she is going to be true to her word.
All the best, Si
Despite the ARM Holdings (LON:ARM) windfall I must admit to being disappointed. I would prefer to have held it forever. Can't say I'm surprised though - look at the CV of the ARM Chairman, Stuart Chambers, one of the very few foreigners to have had success running a Japanese company. I imagine this may have been in the works since before his appointment at ARM.
Christie (LON:CTG) was a John Lee favourite a year or two ago. His strategy is buy-and-hold, so I wonder what his view is today.
Do £CTG's woes explain the poor share price performance of Waterman (LON:WTM) or is something else happening there? Waterman has Quality, Value and StockRanks that are all in the 90s but momentum is poor. Is this a buying opportunity with the yield and PE both around 6, or an imminent profit warning?
Hi FREng,
Waterman (LON:WTM) is bound to have a cloud over it at the moment, as the market is (understandably) factoring in the likelihood that it might lose future business from clients putting major construction projects on hold.
This historic numbers are not necessarily that relevant now, if the cycle has turned against them.
I think it's terribly important to remember that when investing we are essentially trying to work out what the future holds. With an uncertain economic outlook, the market sells off cyclical things. There could be some bargains out there, if cyclical companies are over-sold.
For me, it feels too soon to revisit Waterman. The company may well continue reporting good performance for some time, but I'm worried about the pipeline maybe drying up.
Regards, Paul.
I don't think there is any read across from Christie (LON:CTG) to Waterman (LON:WTM) as they are radically different businesses, Waterman have long term infrastructure and major development projects that are multi year in nature and Christie make most of their money as agents for sale of pubs shops and small businesses, I think Waterman (LON:WTM) is a standout buy at current levels as their pipeline is multi year and more resilient than the share price implies. IMHO as Waterman (LON:WTM) holder in size
"It seems to me that attackers are fitting a pattern - loners, disillusioned with life, easily led, attracted to extremist ideologies, that are being radicalised on the internet."
Sounds a lot like being an investor in AIM companies....
Re the Matchtech (LON:MTEC) name change, I am reminded of an obscure company from Houston, Texas back in the 1980s which decided to change its name from the what-it-says-on-the-tin Houston Natural Gas to the more trendy sounding Enteron.
However, at the last minute, it was pointed out to the directors that enteron is another name for the digestive tract, which might not exactly be suitable for a company dealing in natural gas. So they shortened the new name from Enteron to Enron, and the rest, as they say, is history.
Steve