Small Cap Value Report (18 Mar 2015) - SNTY, BMY, ACSO

Good morning! I was busy last night, adding comments on Fairpoint, Regenersis, KBC Adv Tech, and Ubisense to yesterday's report. So that full report is here.
Budget Day today, so no doubt there will be pre-election bribes for various interest groups, and a last ditch attempt to create a feel-good factor to make us want to vote Tory! Mind you, it will take more than George Osborne tweaking tax rates to repair the damage to my pension fund after today's news from Synety...
Synety (LON:SNTY)
Share price: 92.5p (down 33% today)
No. shares: 8.4m before, 12.3m after fundraising
Market Cap: £7.8m before, £11.4m after fundraising
(at the time of writing, I hold a long position in this share)
There are three announcements today from this niche telecoms/software company.
New Non-Exec Director - good news in that a highly relevant new NED has been proposed for appointment, Peter Simmonds of dotDigital (LON:DOTD) - a company which has been very successful in selling a niche software product on a SaaS model.
Final results - for the calendar year 2014. Clearly the market got wind of there being something up, as the results announcement has been delayed almost three weeks. Delay is never good news, hence why the share price has been falling of late. I'll come back to the results later.
Placing & Open Offer - it's been obvious for a while that the cash position was going to be tight in the run up to breakeven (forecast for early 2016), you could work that out yourself from the interim accounts. However, that didn't bother me because I thought it would be a quick & easy matter to raise a couple of extra million quid, if needed, given that the KPIs have been showing strong growth.
Unfortunately not. There has clearly been little appetite with investors for another fundraising, just a year after the last one raised £4.5m (before expenses) at 250p per share. As a result, the company has been forced to price this latest fundraising at just 90p - half the price the shares were trading at just a month ago.
3.1m new shares are being issued at 90p, raising £2.8m in a Placing. Existing shareholders will have the opportunity, if they wish, to take part in an Open Offer, on the basis of 9 new shares for each existing 91 shares held, also at 90p. So if fully taken up, the Open Offer will raise a further £0.75m.
My opinion - to be brutally honest, this has been handled badly by the company. It didn't raise enough money last year, and you can't go back to investors saying, ooops sorry we're going to run out of money. Or rather you can do that, but they may well take a very dim view, as has happened here.
Bottom line for investors though, you have three options;
1. Cough up some fresh money to maintain your % holding in the company (which should be possible, as some investors will not take up their Open Offer shares, so you can apply for an excess amount), or just buy in the market to offset the dilution from the Placing.
2. Do nothing, and accept that you will be diluted.
3. Sell up and move on.
So it's up to each of us to decide what to do. Personally I've done number 1, because I like the company & the product, and think they are close enough to the original plan to mean that, with the additional money, it should reach breakeven next year.
Final results - coming back to these, the figures are slightly below broker forecast - an operating loss of £5.35m, versus the most recent house broker forecast of £5.1m loss. Turnover is up 198% to £1.63m. These figures may sound terrible, but the company is building a high quality recurring revenue stream (clients are charged monthly, and the churn rate is very low). So the business model involves the up-front fixed cost of providing the cloud-based service, plus employing a sales team to generate customers. That was always going to be loss-making at first.
The interesting part is when operational gearing kicks in & the business has the potential to become highly profitable (as the gross margin is c.70%).
There was £2.36m cash left at end Dec 2014, clearly not enough to take them to breakeven (forecast for mid to late 2016 now, although that does tend to keep slipping). The monthly cash burn rate is c.£300k I understand, at the moment.
The key KPI is annualised recurring revenue (ARR). This is the current run rate of sales at any point in time. You can see ARR building nicely below - remember these are recurring revenues, so a reliable income stream;
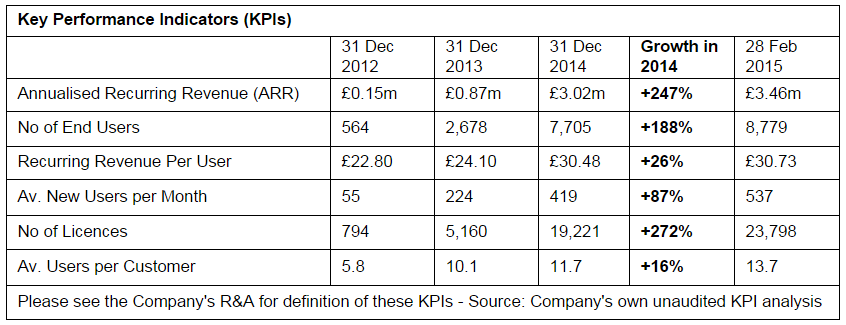
My opinion - the growth is impressive, but isn't quite fast enough to get investors excited (clearly!), and I feel that the breakeven point is too high. So personally I would like to see the breakeven point lowered somewhat through a closer focus on costs.
It will take a while for the dust to settle over this latest fundraising, and let's hope the new NED brings a tighter focus on reaching breakeven sooner, and with more cash headroom. I think this has to be viewed as the last fundraising, given how brutal the discount demanded by Institutions was this time.
On the upside, all it would take is some decent KPIs later this year, and this share could end up looking a real bargain. The product is fantastic (I've used it), and there is encouraging growth happening. The company now needs a total focus on delivering sales growth.
Obviously there are a lot of hacked off shareholders today (including me), but in the long run that doesn't matter particularly, as if the company does well then the share price will go back up again. The shares will succeed or fail based on the delivery of strong growth this year, and achieving breakeven next year, or not as the case may be.
It's clearly high risk/high reward, so will not be suitable for most investors. So far the shares have been a big disappointment, but that's mainly because they were forced to do a fundraising sooner than expected. Remember that on the recent, strong KPIs, the shares recovered to about 200p. If they had raised a bit more money last year, then everyone would be looking at the KPIs today, and saying they're OK. So it's important to keep perspective.
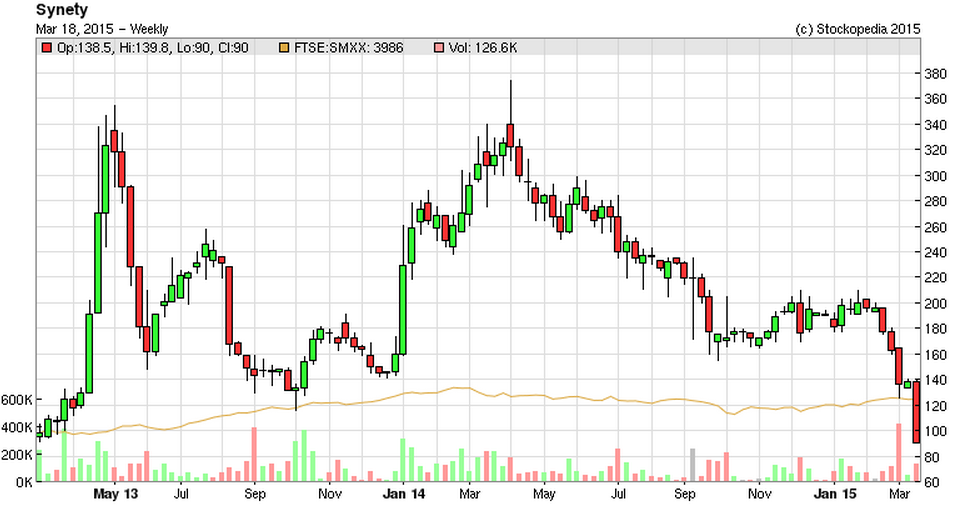
Bloomsbury Publishing (LON:BMY)
Share price: 152.5
No. shares: 75.0m
Market Cap: £114.4m
Trading update - there's a short and sweet update today from this book publisher;
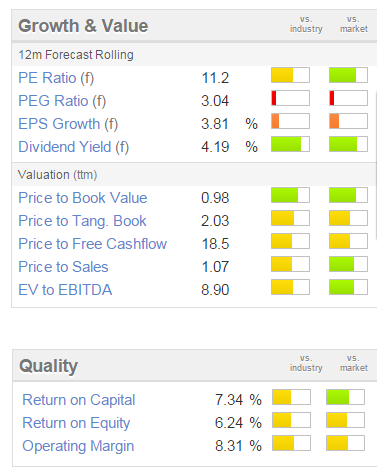
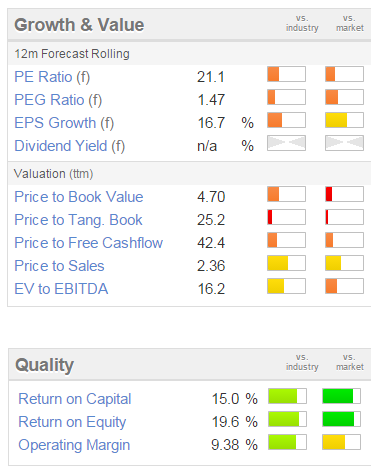
Valuation - it's a see of amber on the Stockopedia value & growth ratings;
Although, strangely the StockRank is extremely high, at 97.
My opinion - I've liked this company in the past, but am wary of anything to do with books - as surely such stocks are likely to be valued on low ratings, given the structurally declining nature of the sector?
accesso Technology (LON:ACSO)
Share price: 580p
No. shares: 21.9m
Market Cap: £127.0m
Preliminary results - for calendar 2014 are out. The company reports in US4. Turnover has risen 24.5% against 2013 proforma 12 month results, to $75.1m.
Adjusted operating profit rose from $7.2m to $8.7m, a rise of 20.8%. I'm not sure what amount of that is organic, and what has come from acquisitions.
Adjusted EPS came in a whisker ahead of forecast, at 30.81 US cents.
Balance sheet - this is looking quite weak now, following acquisitions funded by debt. Net assets are $56.9m, but take off $71.1m intangibles, and NTAV turns negative, to the tune of -$14.2m. Not disastrous, but not great either.
The current ratio is healthy at 1.78.
However, long term creditors includes a new $20m bank debt. That is partly offset by $5.7m in cash, but it's probably as far as the company should go with bank borrowings, to avoid stretching the balance sheet any further.
It would make a lot of sense for the company to do an equity fundraising, to strengthen the balance sheet, whilst the shares are valued highly, in my opinion.
My opinion - I don't know the company well enough to assess its future prospects, but based on broker forecasts it looks fully valued, or a tad expensive, but has done for a while. The valuation doesn't look extreme though, which it did a while back, but it doesn't appeal to me at this sort of level. Long term bulls like the company & its prospects though, I hear.
I'll leave it there for today, as have to cycle from Islington to Victoria station, and back to Hove, after a long stay in London. I've enjoyed the lively debate on Synety in the comments section below, so please feel free to add your comments. We welcome all intelligent comments, whether bull or bear, and it's absolutely fine to say you think I'm wrong, if you explain why. As I often say, investing is a team sport, and I think we reach better decisions by listening to a wide range of views on all shares.
Regards, Paul.
(as mentioned above, Paul has a long position in SNTY (unfortunately!!), and no short positions. A fund management company with which Paul is associated may also hold positions in companies mentioned)
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

63 comments
Hi thanks for this, its really helpful. I had wondered about the close period but didn't know.
I still like the stock and will hold on. I had topped up around 130p but that might look ok this time next year. I'm a bit worried they might need another cash top up next year but lets hope for a strong year of growth which would give them a much stronger hand even if its needed.
Regards
Andrew
Thanks for your views on Synety. I had been really positive on the company's prospects so its good to see I'm not in a minority of one.
I'm shocked at the issue price. Do you feel there's any chance that the price reflects a significantly changed landscape in terms of competition? Also do you know if there were any structural reasons preventing the directors from taking part in the fund raise?
Thanks
Andrew
Hi Andrew,
The Placing price at Synety was indeed a huge shock to all of us. I believe it was originally intended to do the Placing at about 150-160p, but there just wasn't an appetite for stock at that price with Instis. Plus the market got wind of the fact that something was wrong, as the results were delayed - which is always bad news. So the share price started falling, and potential investors in the Placing just kept lowering the price until a level was found where the company got the money it needed. I was staggered when I heard it was 90p.
That said, a decent set of KPIs in the coming months could easily see the share price recover strongly.
I have heard that the Directors were not permitted to take part in the Placing, on advice from the broker - they were inside, and in a close period. They ARE however able to deal now, and they ARE able to participate in the Open Offer. There were 3 Director buys annouced today.
I have collated all Director buying, taken from the company's website (see below), and you can see that they have spent £757k buying shares since Oct 2012, mostly at higher than the current share price. Mostly when the company was at a much earlier stage, and had very low sales too.
Great discussion. Synety On my watch list now.
Paul I bought VCP a couple of years ago as it looked cheap on book value. New mgt team have driven share price ever higher. Any opinions on VCP? Cheers.
Thank you Paul for taking the time to reply. Very informative.
I completely understand your point of view but would only add that:
1. The value of my portfolio is such, that in my opinion, I don't have the funds to allocate part of it to these higher risk stocks.
2. It would be exciting to see one of these multibag I don't think at the moment I have the mental resilience to watch several of them drop 50%/60%/70%/go to zero
3. I am not a full time investor (I have my own business to run which for half the year takes hideous amounts of time 7 days a week) so I struggle to find the time to research blue sky type projects so that I can understand the business properly and see why it makes a good investment.
4. I don't have enough time to fine a large enough number to spread the risk inherent in these type of stocks.
5. Though I am new (4 years max and very much part time) I also tend towards the concentrated portfolio school of thought (I have 15 stocks and 30% in cash). But I am still learning and adapting my thought processes.
That said your arguments are very compelling and it is tempting to invest £1,000 say just to stay in touch with the stock and where it might go - for a bit of fun
As ever thanks for great column and I think this one combined with the comments is one of the best ever.
Regards
Michael
I personally don't get Synety (LON:SNTY) and it is not one for me, mainly because I don't understand it and I don't mean understand what it does but what makes it a good investment long term. I can not see the barriers to entry or the moat. Additionally I can see one of the big boys (Apple, MS, Google) coming along and beating them at their own game. As I tweeted yesterday (https://twitter.com/MBroomSmith/status/578184866442919936) I admire Paul for his conviction and though he says he likes to have a small part of his portfolio in more exciting (bluesky) stocks (though later Paul says this is second largest holdings) I think he must have balls of steel to invest in stocks like this.
Now Bloomsbury Publishing (LON:BMY) is a company I think I understand. This is about content not physical books Paul, so it does not matter whether physical books are declining in sales if they are bing replaced by ebooks which empirical evidence for the general market would indicate that the are (see http://finance.yahoo.com/blogs/the-exchange/the-book-industry-isn-t-dying--it-s-thriving-with-an-ebook-assist-191025547.html) and as Jack Besoz is quoted as saying "Amazon Kindle owners buy more books than they did before they owned the ereader". Certainly that is true in my case. And I would have though (if Amazon does not take too big a slice) that this could be ehancing to Bloomsbury's bottom line.
So the question is whether Bloomsbury Publishing (LON:BMY) can keep or increase its share of this market. The stats for Harry Potter series are extraordinary (see www.statisticbrain.com/total-harry-potter-franchise-revenue/). And if it was JKR was to write another HP......
So Bloomsbury Publishing (LON:BMY) rather than Synety (LON:SNTY) is much more the type of stock I would like to own and it has a Stockrank of 97.
Hi purpleski,
It's not an either or for me (Synety OR Bloomsbury Pub.) - I would happily own both.
I hold about 50-60 stocks in my portfolio, of which at a guess I'd say around three quarters are good solid, high StockRank type shares. Indeed, I get a warm glow when I look at the StockRanks, and say, "got that! got that!", etc, as I look down the list!
However, I also like to allocate about 10-20% of my portfolio for high risk/high reward stocks like Synety. I fully accept that most of them won't work, and might lead me to exit with my tail between my legs, and a 50-75% loss. BUT, the odd one will pay off massively.
So you can't really compare the two approaches. It's chalk & cheese. Of course, it would be crazy to construct a whole portfolio of shares all on speculative stuff (although lots of newish investors do exactly that, and learn the hard way it's not a good idea!).
If you like looking at early stage growth companies, and you make the occasional multibagger, then I think it's a good idea to allocate a small part of the portfolio to multibagger chasing. 10% is fine for me. Sometimes I push it higher. Incidentally, I've bought a ridiculous amount of Synety (LON:SNTY) in the last week. Why? Because risk/reward on it, even short term, is great. 90p was the fire sale price that people who didn't want to invest at all (Instis) coughed up fresh money at. So will it go below 90p? Very unlikely. Yet the KPIs are good, so there is a high chance the company will release really good KPIs over the summer, once the dust has settled over the fundraise.
Therefore I see hardly any chance of SNTY shares going below 90p in the next 6 months, but a very high chance of them going up 50%+ on the release of continued positive KPIs. That to me, is superb risk/reward, with a (say) 6-month timeframe.
If I'm right, and the price goes up to about 140-150p in the summer, then I will sell most of the shares I've bought at the bottom this week for a big profit, and continue running my long term shares.
You don't have to form a fixed view on any share. I like to trade around a core holding. Especially when everyone else is beyond depressed, but is totally blinded by the short term share price movement, as in this case. The fog will clear, and people will suddenly realise it's fully cashed up, and it's dirt cheap. So I see an opportunity.
Regards, Paul.
It's lovely living in yesterday isn't it? Any thoughts on Puricore, Paul? (interesting news tomorrow - sorry, today)
Hi,
Going back to Tom W's rant on Synety (LON:SNTY) yesterday, there were actually some quite major factual inaccuracies in what he said. So I have posted a reply on his site. Just in case it doesn't make it there (which I'm sure it will), I have copied my response below;
Hi Tom,
There are a number of factual inaccuracies in your Bearcast today attacking Synety, so let me correct them;
1. The company had enough cash to last until about Aug 2015, and a small top-up of c.£1m would have been adequate to take them to breakeven in 2016. Now if you want to take a very extreme view, I suppose you could call that being bust, but to most people I think a modest top-up fundraising would be seen as par for the course with an early stage growth company. They only needed to raise about £1.5m, hardly a king's ransom. They decided to raise another million on top of that, for additional sales people, because they are getting a rapid payback of about 5 months on new salespeople added.
2. The historic figures look awful, but are in line with the business plan. This was a start-up about 2 years ago, so revenues are building rapidly, but from a low base. This type of technology start-up business will incur losses in the first few years. That's the deal that shareholders fully understand, that's what we have signed up for, and should not come as a shock to anyone, other than people (as you admit you are) who have done no research on the company.
3. Annualised Recurring Revenue (ARR) is basically the most recent month's revenue multiplied by 12, which gives the current run rate of revenue (and bear in mind revenue is recurring - being billed monthly, has a very low churn rate (customer retention rates are very high, especially for larger customers), and is high margin (gross profit is over 70%). So this is the best measure of the company's current performance, not the historic figures.
4. Therefore, as ARR rose 247% in 2014, it's meaningless to look at the £1.63m total revenue for the year. What you should be looking at, is that at the start of the year ARR was only £0.87m, but by the end of the year it was £3.02m. It has since risen to £3.46m in just the first two months of 2015. So this is a very rapid growth company. ARR should be say £6-8m by end 2015m, rapidly bearing down on the breakeven level, which is £9-10m revenue.
5. This rapidly accelerating revenue also means that cash burn is reducing each month. So the £400k+ per month that you mention for 2014, again was skewed by the big fundraising in April, at which point overheads were greatly increased, to push for growth. As I'm sure you understand, it's overheads first, then the sales come through, which is exactly what is happening, as planned.
6. The company has NOT missed its forecasts by a mile. In reality sales growth is on target. Overheads are a bit higher, but not massively. The main miss in the cashflow is that they are finding much greater retention rates with larger customers (as opposed to small customers with just one or two users), BUT it takes about two months to set up larger customers, which has opened up a two month gap on cashflow. The good news is that the churn rate on larger customers is tiny - so they are clearly the best customers to go for, which is what Synety is now focused on. So a positive in the medium to long term, but has a short term cashflow impact.
7. The £1.4m contingent consideration which you refer to, in current liabilities, is NOT a cash outgoing. It is payable in shares, to a maximum of 740,861 shares, as disclosed in the last Annual Report. These things need to be checked before you fire a factually incorrect broadside!
Overall, I appreciate that Synety is not an investment that will appeal to most people. The reason I hold shares in it, and took part in the 90p fundraising recently, is because I use the product (cloud telephony which integrates with multiple CRM systems, and keeps recordings of all customer calls integrated into that customer record on your CRM system). It's absolutely fantastic! The most impressive stat is that 70% of people who try the product on a 14-day trial go on to purchase it. The product pays for itself in cheaper phone calls, if you spend £50pm on calls. The new Chrome browser plugin is fantastic, and will accelerate CRM integrations.
You really need to try the product to understand what the appeal is. When people use it, they love it. So that explains why sales are growing fast.
Has the company handled the fundraising well? No! They made a total mess of it. There was no need for such a deep discount, and obviously the accounts being delayed 3 weeks sent all the wrong signals to the market. This is what caused the share price to drop from 200p to 90p. So obviously I'm annoyed about that, but the value of the company hasn't changed at all - in fact the KPIs have been GOOD in the last 3 or 4 months. Therefore the share price should, once the dust has settled, recover.
I would say the guys running Synety are very clever, very committed & hard-working, but they are not good communicators (they're too immersed in the tech stuff), and they've made mistakes in handling fundraisings, budgeting, etc. Hopefully the recruitment of Peter Simmonds, the outgoing CEO of DotDigital, as new Non-Exec might inject some additional expertise into the company, on better control of the finances, and how to properly present the company to the City & investors.
At £11m market cap, fully funded to breakeven in 2016, I would say the shares are looking a bargain now. It's counter-intuitive, but when everyone is tearing their hair out, saying what a terrible company it is, that is often the best time to buy, PROVIDING the company has enough cash in the bank, which after this latest fundraising, it does.
I would say though, that patience is wearing thin with management, and they have GOT to make this work. If they come back for more money next year, then it will be carnage. So very much a case of high risk, high reward, definitely not for widow's & orphans! Having said, that, I'm pretty comfortable that doubling my stake at 90p is going to look a smart move this time next year.
Love the bearcasts, by the way - compulsive listening for me, every day. Although maybe a bit more research is needed sometimes, before flying off the handle?!
Regards, Paul.
Thanks Paul, out of interest is your write up based on discussions you have had with Synety (LON:SNTY) management since the results came out or is it purely based on information you have gleaned elsewhere?
Kind regards
Jon
Hi Jon,
Synety is one of my larger investments, so I keep a close eye on it, including talking to the company about once a quarter.
The frustrating thing is that they're actually getting a lot right, and the KPIs are looking good - strong sales growth, and sales per user are rising very nicely - indicating that customers are happy with the product & use it more as time goes on.
Trouble is, they made a serious error by not raising enough cash last year - they assumed that any follow on funding would be easy to get, and would be at a higher price. They also didn't want to see their own personal shareholdings diluted too much at 250p - which has obviously backfired in spectacular fashion. Remember that management have been buyers of the stock at much higher prices - see 31 purchases at mostly much higher prices in last 3 years. So the Directors went all-in some time ago.
It's high risk. high reward. Although I remain of the view that now is by far the best buying opportunity we've ever had - the business is nicely advanced, proven (they could slash overheads & run it for cash if necessary), now has enough cash to get to breakeven, and yet the mkt cap is the lowest it's been since they started.
These things are often the opposite of market sentiment - it's when people are most negative about a stock that you sometimes get the best bargains.
Regards, Paul.
Thanks Paul, appreciate the reply.
I agree with your sentiments and this too is one of my larger investments.
I think the new (ex-Dotdigital) NED Peter Simmonds could have a very positive influence here.
This interview with him back in 2012 is interesting https://www.youtube.com/watch?v=e1cVKzh6dtQ
If you skip to 4:20 he talks about partnering with CRM companies in the US as part of Dotdigital's expansion plans, something very relevant to Synety.
Dotdigital subsequently went on to be very successful in their US expansion.
Kind regards
Jon
Cheers for the response PP.
Not a stock I follow, or would invest in tbh but I was interested in listening to his "OTT rant"
Just not a fan of his modus operandi but everyone has something interesting to say and unlike most I am always interested in hearing the other story.
It's just I occasionally get fed up to the back teeth having to trawl through pages and pages of dross,unsubstantiated lies, overexuberance,and,sometimes, blatant dishonesty on Advfn. Certainly not a BB for the weak of heart - stalkers galore as I can personally attest.
Am a big fan of your daily Small Cap blog though, despite crossing swords on other matters and have recommended it to many.
Most of my investments blue chip focused (outside of the minefield that is Oil of course where diworsification seemingly often doesnt work!) , mainly UK and US.
Synety - guess you'll be facing the shorting herd of Shareprophets listeners and Co then Paul.
Winnifrith bearcast on Synety today.
http://www.shareprophets.com/views/11151/tom-winnifrith-bearcast-18th-march
Dont follow most of the small shitty stocks that he does but occasionally our "interests cross" (such as GKP, Blinx, Afren)
So expect the stock to keep tumbling if there's any truth to his claims...
Hi Fangorn,
Tom W is always good value, and his bearcast today ranting on about Synety (LON:SNTY) is, as usual, a good listen! I would probably arrive at the same conclusions as him, if (as he says at the start), he knows nothing about the company or its products. If you just look at the historic numbers, then of course it looks awful - it was a start-up 2 years ago, so has had to spend the money first, and then revenue builds rapidly (which it is doing now). It hasn't missed forecasts by a lot, only marginally.
What Tom overlooks, is that because turnover is rising rapidly, the cash burn is not £400k+ per month. It's now down to £300k per month, and falling gradually, as monthly recurring revenues start to catch up with outgoings. So there should be enough cash now to complete the run at breakeven. He ignores proceeds from the Open Offer in his calcs, and I have a feeling the deferred consideration is payable in shares, not cash.
Although going back to my original comments above, I do agree that a tighter grip on costs is needed at Synety, so that some of the Placing proceeds are being used to add on more sales & marketing overhead, is a big concern. That said, you need to spend on S&M to drive the sales growth more aggressively. So it's chicken & egg really.
There was absolutely nothing new in Tom's bearcast today on Synety, nor did he reveal any insights whatsoever. But it was, as always, good fun! Those of us who are in this stock understand the business model (cash burn up-front whilst recurring revenues build), and are annoyed that they miscalculated the amount of cash needed, and have come back for more in a cack-handed way.
All this will have blown over in about a month's time, and if the KPIs are good over the summer, then those of us who averaged down at 90p will get our money back. I only need the stock to get back to about 145p to be back to 200p in old money, because I averaged down at 90p.
What caused the share price to tank from 200p to 90p in the last month? Nothing in the performance of the business (KPIs have been good). Just that they decided more cash was needed, and botched how it was raised. That to me is a buying opportunity, but I totally understand that most people won't see it that way - that's what makes a market!! When it gets back to 145p I shall be demanding free wine and pizzas at Tom's restaurant by way of an apology!! ;-)
Regards, Paul.
A picture paints a thousand words. Awesome post Ed!
I suspect cash burn will be lower than the £425k, the problem with doing it over a whole year is that Annualised Recurring Revenue more than trebled during the year.
So if I understand right, that means rough monthly revenue start of 2014 of £73k, end of 2014 £251k and end of Feb £288k (from ARR divided by 12)
Using their full year numbers you get a figure of £136k for their monthly revenue, so probably underestimating by £100-150k on their currently monthly revenue?
I recon SNTY has further to go down yet before it returns back because of a valuation of around 32p yesterday. I prefer a share going up like GATE, the last few days, thanks Stockopedia for another one.
Synety seems to of been a complete disaster if you ask me Paul, you sell TUNG which looks a far better company, but keep this dog in your portfolio - doesn't add up
The market's view of companies such as SNTY has dramatically harshened in the last year, and the heavy discount demanded has further hurt the company's reputation; a bit of a vicious circle. I think the company has pretty much delivered though, subject to your comments about cost containment, which I strongly support.
I invested at around 170p and still hold, but will not top up at the moment, mostly because in the current environment the price could be forced down to a ridiculous level (remember TNI? and that had cash flow). Maybe at 50p, we'll see.
A number of commenters above reflect on a poor value proposition but argue the case on a deep value basis. I see it a bit differently:
* progress is close to original plan, which is where most blue sky's fail - they normally take way too long to get going.
* £11M market cap.
* good accounts are buying (not to mention yourself!) suggesting the value proposition is real
* If current progress continues, the prospective earnings one year from now on today's mcap will look juicy.
The only real risk is that the progress achieved so far will falter. High risk, but the rewards may well be worth it.
I don't know Accesso particularly well, I have read some posts over the years on TMF and was at the Mello presentation last week. Accesso has a good story to tell but you have to pay a premium to buy the shares.
I have to say I'm a bit suspect of earnings that are adjusted for stuff like amortization, however if you use adjusted EPS the P/E is circa 28. They have ~£10m of net debt so the E.V P/E would be closer to 30. If you take reported earnings, 18c, the P/E is 47. Earnings haven't exactly grown at a rapid rate, according to Accesso's stock report earnings were 18c back in 2009, if you use the more flattering 2014 adjusted EPS of 30c earnings have grown at 11.3% per annum over that five year period. To buy ACSO now you would have to believe that there's going to be a very substantial growth in earnings over the next few years.
Hi Paul
Thanks for your write up re Synety (LON:SNTY).
You say 'The monthly cash burn rate is c.£300k I understand, at the moment.'
I wondered what the source of this information was?
At the Investor presentation in September we were told cash was £4m at end August 2014 and that cash burn had peaked at £400k per month. However the results show cash at Dec 14 end of £2.36m suggesting £1.64m burnt in 4 months which is more like £440k per month which doesn't suggest the cash burn is under control and reducing?
Cheers
Jon
Jon - I calculate the burn rate is £425k per month. This is based on taking the operating loss before working capital movements in the cashflow statement (which equated to £4.6m) and subtracting a further £0.54 from this (which is related to acquisition of PPE) and dividing by 12.
I'm not an accounting expert by any means, but this is the way I would calculate the burn rate.
Best wishes,
Imran.
Thanks Imran, so doesn't suggest a peak of £400k per month. Also re the placing announcement 'Placing will be used primarily to increase sales, presales and marketing personnel in the UK' suggesting costs will increase, potentialy further hampering a reduction in cash burn.
I can see the growth in revenues here is very strong but I think they should be looking to cut costs and reduce the cash burn. I'd expect to see cash burn reducing as revenues ramp up but that does not seem to happening.
Hi, One of the main things that has stuck in my mind after hearing Mark Slater speak last week is: Don't buy hope! Buy a business when it is performing - yes you may pay more but in the words of Warren Buffett: it's better to buy an excellent business at a fair price than a reasonable business at a good price. The problem is that few blue sky businesses actually perform according to plan due to numerous reasons both internal and external to the business. Investors are often sucked into the story or concept and become optimistic about the future potential and size of the market opportunity and often ignore the negatives - this is often compounded by enthusiastic and polished directors at investor presentations. There are plenty of examples of blue sky stocks that have tanked but relatively few that have succeeded and therefore buying shares of such companies should be considered a gamble rather than a investment. I have invested in a few blue sky stocks and most have been a disaster. I do however hold Tungsten (LON:TUNG). which I have put a 70%/30% chance of success/failure. Before making an investment decision I now make a list of reasons why I shouldn't invest in the particular company. This feels unnatural to begin with because our brains are geared to look at the potential opportunity and thus assess the investment positively (reasons to buy).
Best of Luck all.
Ben
Ben, I'd also add that there's value in doing a regular "would I buy this stock today" exercise.
It might bruise your own ego to conclude you might have made a bad decision but if you find you have doubts, you identify them straightaway and make a fresh decision on whether to hold or to sell. Imo, a lot of money is lost from just sitting on losers, not wanting to admit you've been wrong, and hoping things will "somehow" just turn around, i.e., "I'm right, it's the market that's wrong!"
Like Paul,I have had Synety in the "blue sky" section of my portfolio and have been happy to describe it as one that I expect to see mature in 2016. I still do, but I had not anticipated that it would make 2015 look quite so difficult.
It has also been a stock where I have, in retrospect, not been taking the right message from the continuing decline in the price over the last few months. I tend to look around and say "there is no reason that this stock should be falling". Well clearly there was a reason, how that gets out to the market can be debated, but as with other stocks I have owned there seems to be a lesson here that - mostly - the market KNOWS. I plan to be more respectful of that in future.
I started writing a blog last week that started to get a bit too long... it got to 3000 words ... so I'm now realising it should probably be worked into an ebook.
I'd be interested in anyone's comments... it sort of developed into a fable and is definitely a bit ham-fisted. Its current working title is "What Pays Off and Why". It talks about the difference between two archetypes of stock - whose statistics are based on the averages of 2 extremes of the StockRanks. I can't help but feel that in the last week, Dart & Synety & the market reaction to their news are a near perfect example of the 2 archetypes described. You can read it here...
Ed - this bit is totally unrealistic. Most sell side analysts are there to generate orders, and are paid to be optimistic. It's not their fault, it's what they are paid to do - the analysts who don't "play the game" suffer a lot financially. There ARE occasionally bearish analysts, eg Sanjay Jha, but they are very smart, and often very right. But they don't work for large investment banks, they do it because they enjoy the intellectually challenge of being right, and know they'll never be rewarded like people who "play the game".
"Look Charlie... our sector analyst, Mithun Parekh, is the best in the business... he's a triple AAA rated star analyst with 15 years industry experience and he really strongly doesn't fancy this stock. He’s adamant that this year’s growth is only a temporary cyclical uptick... he's expecting low, if any, profit growth for the next few years and his price target is only 5% above the current level. There are 4 other analysts covering the stock and they barely rate this a buy. Why waste your time with an old economy stock like this when the market is on a tear in other areas? It's really not worth the bother. Look, I'll talk to Parekh personally and call you back with his best idea in 10."
You'd be amazed... the story isn't completely fiction... it's actually based on the real statistics from 10 different buckets of stocks ordered by the StockRanks.
I do appreciate that brokers are paid to be optimistic.... but that doesn't mean they need to be less optimistic on higher probability shares - but the charts below show that that's exactly what they are doing.
Bear with me...
Here's the profitability of the average stock in each StockRank bucket
And here's the historic growth...
I think we can say there's a clear trend towards higher profitability stocks showing higher growth. You'd expect the best companies to have higher price targets and growth expectations... but no... it's the other way around... the fastest growing and most profitable companies have the lowest expectations !
So surprise, surprise... which stocks do you think have been beating (or missing) forecasts?
The best companies with the lowest expectations have been beating expectation - so guess what the brokers keep doing... ? Upping their numbers on good stocks, cutting them on bad stocks....
And finally, guess which companies keep having to dilute shareholders massively ? You guessed it...
In my opinion these statistics should make for utterly galling reading for anyone mucking about in low StockRank stocks. You have to expect to be diluted, see reduced broker expectations, share price losses and generally poor outcomes.
So I don't think the paragraph about the broker is in error at all... I've been a stockbroker and have listened to analysts talking gumph and had to sell it. Just because there are a few good independent analysts out there doesn't mean that in general their predictions are of any use at all.
The fable I wrote is not just made up... it's based on my own statistical research across 2000 UK stocks... of course there's lies, damn lies and statistics... and I'm just as good at finding what I'm looking for in data as anyone else... but I think the trends above are pretty clear.
I've just got to say Ed - these graphs are awesome - they should be on the front page. I know that you're talking your own book in a sense (re: Stockopedia) but the earning surprise and dilution record graphs are utterly compelling. I'm slowly rebalancing my portfolio away from lower-ranking stocks but frankly I should just get on with it!
Damian
Thanks Damian... I'm utterly paranoid about the StockRanks eventually underperforming as I use them 100% as my own investment system - so I'm constantly researching their qualities. I do appreciate that sharing and popularising them is perhaps shooting myself in the foot, but given the persistent behavioural biases everyone has which make us avoid high ranking stocks I think the anomalies will persist a long time.
Dart Group popping 18% in a day is a classic example - nobody expected it to keep trucking.. while from the readership stats here there's clearly thousands fully loaded into this classic story stock Synety. Why wasn't everyone buying today's highest ranking stock - H&T Group ? I doubt many did... it's a pawnbroker and its peer Albemarle & Bond went bust.... you'd have to be a brave man.
I find the behavioural side of the StockRanks fascinating... everything about them is contrary to human nature... we avoid the fear & loneliness involved in buying cheap problem stocks, can't bear buying new highs and particularly avoid the boredom of buying safe, dull stocks. Seems so many of us prefer to go bottom fishing with everyone else in exciting pre-revenue growth stocks !
Hi Ed - paranoia is good you know as the 'market' really is out to get us! As time has gone on, and the track records have extended, I've very much got on board with the idea of assessing different metrics (quality, valuation, momentum) and linking these to the often illogical biases that we all labour under.
It's easy enough to listen to Warren Buffet talk about keeping his powder dry and only buying when everyone else is running scared but it's a whole heap harder actually acting on these thoughts. Along these lines, and in retrospect, I should have invested everything but the kitchen sink in 2009 and yet I didn't and why not; fear and uncertainty mainly along with a sense that I couldn't quite trust myself to decide what to buy.
Like you I find human psychology fascinating, particularly as it pertains to investing, and I'm only too aware of my own weaknesses; which is why many of my recent purchases (Spaceandpeople (LON:SAL), RTC (LON:RTC), £NG. £PPH) have been in stocks with ranks above 80 and in spite of any recent share price strength. I've definitely come around to the idea that upwards momentum is worth having and I find it a bit strange that I used to favour shares where the price was falling!
Oh and I do have some Dart (LON:DTG) and it is one of my top-ten performers - although not quite as good as Man (LON:EMG) in recent times! As for H & T (LON:HAT) it's a really interesting prospect; they have survived where so many others haven't and recent results show a much improved balance sheet; so I actually am tempted despite the sector!
Cheers.
Hi Ed
These posts are turning into one of the best ever on Stockopedia. May be you should link to it on the home page?
I dont suppose you would mind expanding in "I use them 100% as my own investment system"? Does this mean you only invest in stocks with stocks with Stockrank of over x? (Where x is 90 or 95etc?)
Thank you.
Hi Ed,
Thanks for your posts very interesting
I can see the benefits of the Stockrank system in picking shares but have you done any analysis to see when is the best time to sell. Presumably an obvious fall in Stockrank would most likely occur a long time after the event for example bad news causing a major reduction in SP and therefore momentum rank. By the time the stockrank reflects the current state it is I assume too late to sell.
Any thoughts?
P.S any updates on the possibility of Stockopedia ETFs? (not that I am lazy)
ED,
From your graphs strikes me that what we should be looking for is QMV Stockrank scores of over 90 with quality parameters in the order of:
ROA >10%
ROCE >18%
ROE >18%
Reminds me of a Can-Slim approach when above combined with recent momentum. Ian
So exemplified today by Synety (LON:SNTY) vs Bloomsbury Publishing (LON:BMY). I have to say that despite having multiple monitors and fancy data viewing tools, every time I have to try and understand complex data at work, I go straight to the printer and then crack out my trusty ruler and yellow highlighter... Something about "feeling" what I am reading, I wonder if the multi-millenia history of books is finished just yet? Maybe I am just a dinosaur.
Ed this looks like the start of a book I would very much like to read, at the same time educating many of us in how to construct a portfolio with the characteristics of the mythical super stock.
Hopefully it will contain information on the practicalities as well as the theory.
Anyone that's interest should read back through the comments I've made on Synety previously after one of Paul's (excellent) blog pieces
Synety is a company with zero barriers to entry. Their product is laughable, and they have been releasing RNSs along the lines of 'We got a developer to do half a days work today and make two bits of kit talk to one another'
Reason there's no investor appetite - I could build their product in about 10 hours. Their only USP is that they have a friend at Salesforce - but I can't imagine they'll be friendly for very long.
lucien,
not sure microsoft made a mess of skype, they bought it, ran it for a while, didn't like it, closed it down and now offer unified comms via a far more integrated product called lync, which offers a lot more than skype did for the business office, i.e integration to exchange and office etc.
regards
They haven't closed down Skype, and I don't see them doing so in the future. Lync is MS's business product, they are also starting to push Skype for business more.
I've been using it for many years, its our company standard for IM communication and every time they do an update it seems to get worse. There are so many features that used to work almost flawlessly that now seem to break (sending files for example).
My thoughts are mostly based on anecdotal evidence but I have heard at least 10-20 people independently complaining about the same issues. Its a sizable percentage of the people that I regularly work with via Skype.
Hi lucien2k,
It's funny that you should mention Skype in the workplace as when I joined my current employer everyone used it for IM, video calls and suchlike; so I was forced into using it. However just recently I've convinced everyone to switch to Slack (https://slack.com/) as an alternative because it's just great; easy to use, integrates extensively and with a search that works.
I'd suggest giving it a look - and I have no interest in the company apart from being a happy user!
Damian
I’m ultimately happy that I hadn’t invested and have no inclination to enter today but I respect your views and hope it works out for you. They are closer to the bargepole list than the watch list today; mainly skewed by my opinions on management competence rather than the figures.
I do have a question about portfolio weighting though. You said that you will take part in the placing so as not to dilute your holding which I can understand but aren’t you just overly exposing yourself? You have previously said that Synety (LON:SNTY) was your second largest holding. You also said you were buying up at the 250p level which was the previous support level for the last botched placing. You must be having to put some serious funds into this company to not be diluted but how do you justify that with the re-balancing of your overall portfolio and exposure to such a highly speculative stock?
Hi billytk,
I've doubled my position in SNTY at 90p, which is taking a risk, yes.
But for the reasons given, I think it stacks up as things stand today. Personally I don't get too hung up about what has happened in the past - I have a mental process to get rid of the emotional feeling on bad news as quickly as possible, within the first hour of bad news, and then focus on the fundamentals as if I were a new purchaser of the share today. The market doesn't know or care what price I paid, and what my view on the share was in the past.
So based on it now having more than adequate cash to reach breakeven, and the mkt cap being the lowest it's been so far, for the company in its current guise, and with the KPIs showing strong growth, then looking at it completely logically, 90p is probably the best buying opportunity there has been so far for this share. That's why I've doubled my position in it at 90p.
I haven't worked out what % of my portfolio it is yet, as I don't want to scare myself!
Regards, Paul.
I have a mental process to get rid of the emotional feeling on bad news as quickly as possible, within the first hour of bad news
It would be interesting to hear more about how you do that Paul. Have you ever written about it?
Kind regards,
B
Just sitting reading through their annual report and they do give some good detail in here.
Sales staff increased from 12 to 32 in 2014. 15 to 23 development staff and overall they doubled their head count from 41 to 82, doubling their wage bill. That is where their money is going.
Their staff don't seem to be super expensive for a tech company either, £51k per person.
With Microsoft making a mess of Skype, there's definitely potential for another company to capitalise. As Paul said, its about managing costs. If they can continue their sales growth, then in 6 months a new statement may look very good, especially if their new sales staff can deliver.
rick - ?? What is the point of a comment section if the merits of the stock in question may not be discussed? Yes: let's not turn this into an ADVFN bb discussion where any dissent is censored.
--
Paul - yes after today's fall SNTY may fall into the GARP category. Good fortune.
singer have updated on todays, note the breakeven on Q4 2016...
"Synety has raised £2.8m (gross), placing 3.1m shares at 90p with the potential for a further £0.75m from an open offer to fund continued acceleration in the growth of both the UK and US operations. Since the capital raise in Apr’14, Synety has grown its customer base by over 70% and users by almost 90%. The US office, opened in June, is delivering metrics which suggest it is following the trajectory of the UK with a much larger potential market. The additional capital will allow Synety to continue to expand its recurring revenue base as it develops a leading position in the growing cloud telecoms market. The software-as-a-service (SaaS) platform means that revenues at full run rate will generate a high drop through to profitability, which we expect to build substantially from breakeven in Q4’16, despite continued investment in growth."
no position.
Regards
mrwhits.
Lets not turn this into an ADVFN bb discussion we get your point loud and clear dasv. Show some respect to your host.
rick,
No, no! I welcome a lively debate, and people can say what they want here! (it's fine to criticise me, I have no problem whatsoever with that). dasv's comments are absolutely fine. Critical opinions are often of more value than ones which reinforce ones own view, as they make you think again.
I completely take the criticism on the chin with SNTY, it's been a bad day, and they've messed up by raising money at such a discounted level, no arguments over that. My enthusiasm for the share has not worked out (so far), and I totally accept the criticism.
However, I'm also pointing out, that all is not lost by any means.
Regards, Paul.
Story stocks are a minefield for stock market investors, one needs to be extremely careful about capitalising hope... There's a famous study by Rob Arnott that showed that while the stock market always valued the correct (future growth) companies at a premium, it never failed to overpay for the growth !
Hi Ed,
Sure. On the StockRanks, you would never buy any smaller, speculative share. Which overall would probably save us all money!! On the other hand, if nobody ever invested in smaller growth companies, and was prepared to fund the early stage losses, then most tech companies would have never got off the ground! (including Stockopedia! ;-)
Good ideas need funding, and it's high risk/high reward. There will be occasional multibagger, but most will be losses. Personally I tend to keep these high risk/high reward shares to less than 10% of my portfolio overall.
With Synety, I'm not sure that screwing up one fundraising is justification for saying that the company is rubbish. It's KPIs have actually been good, with strong growth in recurring revenues. So it's not actually a story stock. It's a small, high growth company which is currently loss-making. To my mind, story stocks are blue sky things, developing a new product. Synety is an early stage growth company - the product is out there, it works, and is high margin, they're now growing the user base rapidly. Again, similar to what you're doing with Stockopedia!
Regards, Paul.
Ed, with what are effectively "story stocks", it's perhaps better to pick up on the story at chapter 2 or 3. The action never usually happens in the first chapter, anyway. After having my fingers burned a couple of times in the early days by the "Red-Hot Penny Shares" type of stock, I now only very, very rarely invest in companies that are story stocks or start-ups and seldom in "recovery stocks". BOOB (buy only obvious bargains) and TABOO (there'll always be other opportunities) are a couple of investing acronyms that have served me well.
Hi Ed
As human beings lots of studies have shown that we are hard wired to be optimistic.
There is a very entertaining TedTalk on this subject by Dr Sharot "The Optimism Bias" here.
"With respect, you wouldn't think the numbers were terrible if you had researched it, and knew what expectations were!! The figures are largely as expected."
I used to be a holder (speculating post IPO). I have looked at the company a few times.
true - I wasn't following expectations for numbers today.
But the figures are still terrible in absolute terms, whether they are unexpected or not.
So I disagree that I wouldn't think the numbers were terrible if I knew the expectations! Yes it's a start-up but with such a huge loss relative to revenue, the company has driven the sp into a wall by not cost-cutting earlier as revenues have been slow to grow (in absolute terms and in relative terms to cost, even if revenue growth is high percentage-wise, relative to the previous year).
"The business reaches a breakeven run rate during 2016, and is then profitable in 2017."
Will the placing be sufficient for the company to reach break-even, or will further placings be required? Same question for WAND and BLUR and n-stocks in the rest of speculative AIM BTW.
"It's a high growth tech co, so this share will not appeal to most people here."
I agree: this is called the Small Cap Value Report.
I don't think you can call SNTY a value stock, although you could argue the discussion is not about value stocks, but of the value of all stocks?
"Anyway, you can't judge it now - we need to look back in just over a year's time, and judge it then, on whether they have reached breakeven or not"
The market's participants continually make judgements or forecasts. My money would be on a further placing being required before break-even. Management could have seen this coming, should have managed costs better in advance, and as you say didn't raise sufficient capital earlier. Will management decision quality improve or remain the same? If you believe in the guys running the co. - that they will focus on costs as well as growing revenues, then there is a case for being long. I think I'll just be watching on the sidelines on this one.
Hi dasv,
The focus of these reports is Value & GARP. I write about what, in my opinion, are the best Value & GARP situations that I come across. I get more right than wrong, that's why thousands of people read these reports!
So with Synety (LON:SNTY), given that the market cap is now £11.4m AFTER this latest fundraising (that's assuming full take up of the Open Offer too), then I would say the company is a GARP stock.
If you look at cash, it would have existing cash of £2.4m at 31 Dec 2014, plus £3.5m raised today (say £3.2m after costs), which gives pro forma net cash of £5.6m at end Dec 2014 - half the market cap. Cash burn of £300k pm, means it should now be fully funded to breakeven. That cash burn should of course steadily reduce as ARR continues to rise each month.
The company could have taken a gamble, and carried on without a fundraising, but took the view that they needed to be certain of having enough in the bank to get where they're heading.
Moreover, with management having thoroughly screwed up this fundraising, I think they've now GOT to reach breakeven, and I am making that point directly to them. Another fundraising is not an option now, and they need to start being a lot more careful with overheads, in my view.
Regards, Paul.
Kate Hanaghan at TechMarketView writes, re Synety (LON:SNTY),
"Regular readers will know TechMarketView frequently talks about the difficulties of making profits from a SaaS model. Indeed, even Salesforce – the original SaaS 'poster-child' – remains in the red, as do many of the other well-known SaaS firms. Synety's Board, however, remains “excited about the prospects" for this year and views the future with “optimism". We admire its positivity but without a shadow of a doubt very difficult times lay ahead. "
I'm neither long nor short, but this seems like another story stock, and very high risk, so I'm staying out.
"Final results - coming back to these, the figures are slightly below broker forecast - an operating loss of £5.35m, versus the most recent house broker forecast of £5.1m loss. Turnover is up 198% to £1.63m. These figures may sound terrible"
Final sentence: you took the words out of my mouth. Terrible.
Are my sums right? they'll need 1 328% increase in turnover to £6.98m to break-even assuming no rise in costs and no price reductions in their product.
If they made a loss of 5.35m on 1.63m turnover, that means they burnt 6.98m in the period?
You say cash burn is now 300k. This is about 50% of the annualised burn?
End-weighted cost reduction or end-weighted revenue?
Hi dasv,
With respect, you wouldn't think the numbers were terrible if you had researched it, and knew what expectations were!! The figures are largely as expected.
So the £1.63m turnover is rapidly growing from a low base (this was a startup 2 years ago remember). So by the end of 2014 the run rate of turnover had reached just over £3.0m.
When you have very rapid turnover growth from a low base, the historic numbers look awful, of course they do. The business is valued looking forwards, not backwards. So the 2015 broker forecast (issued this morning) is for a leap[ in turnover from £1.6m to £4.4m, then £8.0m in 2016. The business reaches a breakeven run rate during 2016, and is then profitable in 2017.
It's a high growth tech co, so this share will not appeal to most people here. Has the business performed disastrously against what was expected? No, not at all. It's a little bit shy of forecast, and needs a relatively small fundraise - only a £2.8m Placing, which should have been a formality. It's been handled badly, hence the share price drop.
The share price will go up again if/when the KPIs show continued strong growth. The crucial thing though is to buy more at the lows, in my view, otherwise dilution is the killer.
Anyway, you can't judge it now - we need to look back in just over a year's time, and judge it then, on whether they have reached breakeven or not. If they have, then it's probably a multibagger from here (especially if you buy heavily at 90p, as I've been doing). Other people won't want to touch it with a bargepole, I totally get that, and that's fine. Whatever floats your boat! I like one or two high growth, speculative stocks in my portfolio, but am mainly focused on value/GARP.
Regards, Paul.
I agree with you as regards the long term prospects, but I do have reservations regarding the cash burn rate and whether another placing will be required before break even.
Another point which on balance dissuades me is the mention of delays of 6_8 weeks in
'Customer provisioning' which I presume is setting up Synety's systems up for the customer to start using the service. This could be the real bottleneck, and as an operational issue could stall growth.
It worries me.
Synety (LON:SNTY) I tend to agree with billytk. Looking at the cold numbers only, even on optimistic assumptions, it would take more than 2 years before we see a net profit. And that assumes fairly aggressive revenue growth.
I have no investment in this company. So is it attractive at today's knock down price? Taking into account other factors too such as (lack of) management professionalism, IMHO the answer is no.
Morning Paul, sorry that you're still involved in the car crash that is Synety (LON:SNTY). I nearly bought in a couple of times over the last year or so mainly due to your coverage of the share and enthusiasm for the scope of the opportunity. I think Simon Clever is slippery and have no time for the guy. After today's announcements and another huge discounted placing I wouldn't go near this share as they have lost all credibility IMHO.
Not that you can separate your emotions from having been invested in here for some time but I can honestly see that if you were to cover this company today for the first time you'd probably put it on your bargepole list. Yes there's scope but the management have continually over promised and undelivered. Breaking into the US in a big way is going to cost far more than a couple of million.
Hi billytk,
It's no good letting your emotions drive investment decisions. You just have to look at where the business is now, what it is currently valued at, and what the prospects are.
So in the case of SNTY, it has delivered results that are only very slightly below forecast. The KPIs are pretty much in line with plan too. The valuation is dirt cheap. What has gone wrong then? They just didn't raise enough cash last year, were short by a couple of million, and came back to the Instis for more, when they were in no mood to put in more. So the Instis demanded a big discount.
Has it been handled well? Not at all, as I said in the article, it's been handled badly. But is this a bad business? Not at all - it's growing very rapidly, building recurring revenues and is within reasonable distance of breakeven.
I don't believe in throwing the baby out with the bathwater. If growth was slowing to a crawl, then I would have no hesitation in throwing out the shares. But take a step back, and ignore the cash issue, and you'll see a business that is performing close to plan. They made a big mistake in not raising the cash needed to get to breakeven, but that's been fixed now.
Hence why at the valuation noted in today's article, cashed up now until say mid-2016, I think this is probably a great time to buy. Who cares what happened in the past, it doesn't matter. We are here now, and it's purely a question of whether the business plan is credible, and if the valuation is reasonable? I would say yes to both of those. But equally I totally understand why most people will disagree with me. I use the Synety product, which is probably one of the reasons I can see the potential here.
Regards, Paul.