Small Cap Value Report (18 May 2016) - DX., HMLH, CAKE, CHH

Good morning!
What an awful day yesterday! First all the problems with LAKE, which caused me a nasty financial loss first thing (but I'm pretty confident that's money I'll get back in due course). Then my article here corrupted, with the formatting going haywire. So a reverse midas touch day. Never mind.
DX (Group) (LON:DX.)
Share price: 20p (down 11.1% today)
No. shares: 200.5m
Market cap: £40.1m
Planning application refused - this logistics company is committed to a very expensive new sorting hub in the Midlands. As its finances have deteriorated, external (therefore more expensive) funding was arranged.
Today it announces that the local authority rejected its planning application last night. The company is now considering its options.
In my view, this might be a blessing in disguise. My view on this share has hardened recently. I think that the core, most profitable business, the DX Exchange could now be in terminal decline. With a fixed cost base, it has big operational gearing. Customers are increasingly emailing documents, instead of using couriers. I don't see any reason why that trend would stop, let alone reverse. That leaves DX Exchange high & dry potentially.
Other business is low margin, and highly competitive. So this is likely, over time, to become just another struggling, and possibly even loss-making courier/parcels company. As such, the shares have little to no attraction in my view. Taking on a hugely expensive new depot seemed like overkill anyway, so hopefully the company might now drop its plans to do so.
Good money can be made from catching falling knives, providing you only pick companies with a good business model, sound finances, which have encountered temporary & fixable problems. I initially (wrongly) thought that DX Group fell into that category. However, I have revised that view, and now believe that this company is in structural, possibly terminal decline.
Also, when you look at its balance sheet, the deferred income is likely to unwind as the DX Exchange declines (because customers pay cash for an up-front subscription). Therefore, I think there is an increasing likelihood of a cash crunch here in the next few years.
HML Holdings (LON:HMLH)
Share price: 32.3p (up 2.5% today)
No. shares: 38.9m
Market cap: £12.6m
Acquisition & trading update - another small acquisition has been made. This is the group's strategy, of rolling up small property management firms. It's a good strategy I think, in that they can usually be bought quite cheaply, then bolted on to HMLH's existing IT system, and deals with insurance companies, etc.
Revenue is annuity-like, with low client churn. So quite a nice business model on the face of it. My main concern is that the largest profit generator is kickbacks on arranging insurance for clients. I think that's potentially vulnerable to action by Govt, regulators, etc.
Back to today's update. It's a reassuring, in line update:
The board confirms that trading for the period ending 31 March 2016 was in line with market expectations and looks forward to releasing results in relation to this period in late June 2016.
Valuation - Stockopedia shows consensus of 3.26p EPS for y/e 31 Mar 2016. So the shares look reasonably-priced at 32.3p, giving a historic PER of 10.
The PER is 9, if you base it on forecast earnings of 3.5p for the new year.
That seems a modest rating, for a nice little growth share.
Dividends - the yield is only 1.14%, but this is because cash is being used to make acquisitions. That's fine, as the track record on acquisitions seems good.
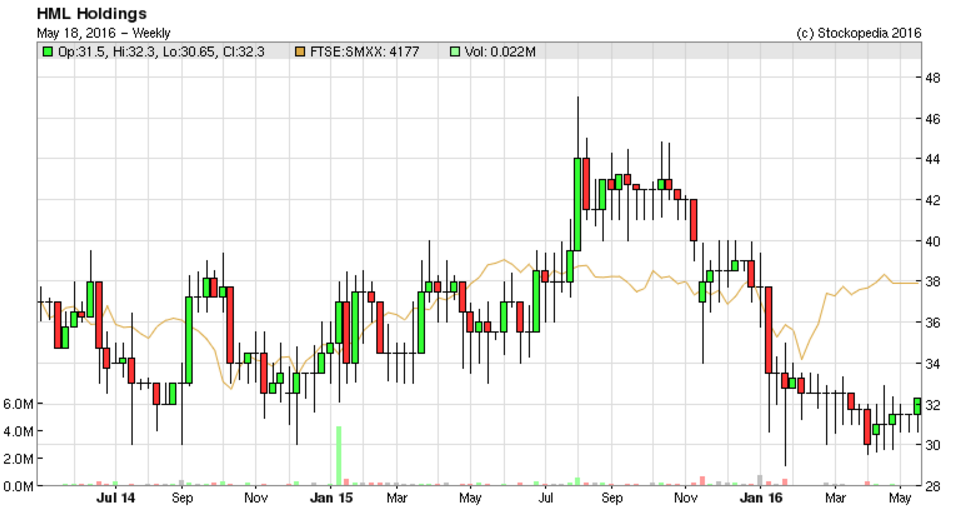
My opinion - the price has come down quite a lot in the last year, and it's looking reasonably good value now, in my view.
I liked the management when we met them at Mello some time ago - not flashy at all, just seemingly safe hands, and with a good strategy to gradually grow the business.
Lack of liquidity can be a problem when you get down to this sort of market cap, so for that reason I probably won't be buying any myself, but it is tempting at this price I must admit.
I've heard that the Govt is looking at reforming the law on insurance. So it's an important issue to consider. Investors therefore need to check out whether the commissions received by property managers like HMLH might be under any threat from new legislation.
Patisserie Holdings (LON:CAKE)
Share price: 351p (up 3.9% today)
No. shares: 100.0m
Market cap: £351m
Interim results, 6m to 31 Mar 2016 - these are absolutely superb results. I'm very tempted to buy some shares in this successful retail roll-out, despite the rating being very expensive.
Here are the highlights:
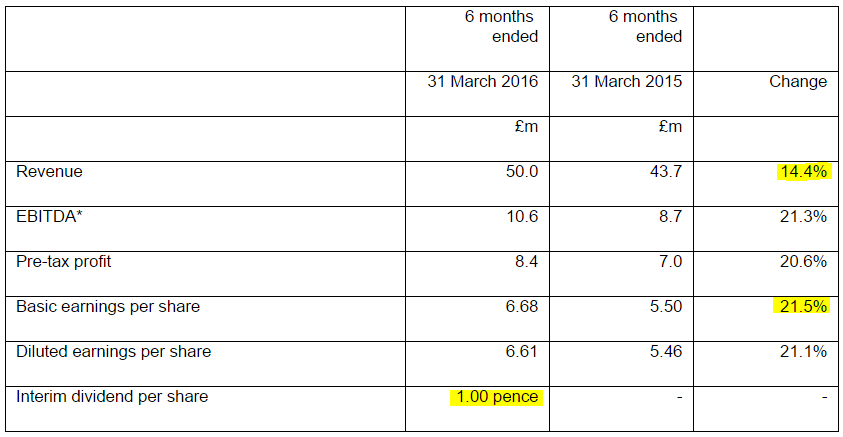
Note that profit is rising faster than turnover.
Also note the 1p divi. The lovely thing about this business, is that it's self-financing the roll-out of new sites, and still has cash left over to pay divis.
There's no doubt this is a very popular format, you can tell that from the high operating profit margin. So I reckon there could be potential for maybe 3-5 times the current number of stores perhaps?
Outlook - sounds good:
These results represent another strong performance from the Group. We continue to control costs tightly, make efficiencies in our supply chain and with the quality of the new site openings in the first half of the year, the developed pipeline and continued solid trading from our premium offerings I am confident of achieving the Board's expectations for the full year.
Valuation - forecasts are for 13.3p EPS this year, and 15.3p next year.
That gives a PER of 26.4 this year, and 22.9 next year. Yikes, that's a rich rating, but in this case I think it is justified.
There are very few good retail roll-outs. This one is probably the best right now - it's already highly profitable, generating a lot of cash, and paying divis.
Other ones I like are Crawshaw (LON:CRAW) which is still quite early stage, hence looks crazily expensive right now, but won't look expensive in 2 years't time. Then there's DP Poland (LON:DPP) which in my view is a complete crock - rolling out a format that doesn't make any profit is just plain daft. Although it is generating very strong LFL growth (but needs to!).
Then you have organic growth from Boohoo.Com (LON:BOO) which of course can expand faster, as it doesn't need physical stores, and can expand internationally too, from a UK base.
My favourite roll outs are BOO, CRAW, and CAKE. The only one I don't hold any shares in right now is CAKE, so perhaps I need to grit my teeth and just pay up?
We're in a market which is obsessed with growth, and will pay a high multiple for it. CAKE has a terrific format, and after results like today's, it's difficult to justify not owning any shares in it. Sometimes we just have to pay up for quality & growth.
Note that only half of CAKE's cashflow was needed to finance its expansion (i.e. capex). So the company is now in that lovely sweet spot where it self-finances further expansion. There's a lot of competition in this space though, but CAKE seems to have cracked it, with an up-market brand image.
Smashing figures, I really like this company.
Churchill China (LON:CHH)
A reassuring update today:
"I am pleased to report that 2016 has started well with good progress against our objectives. We continue to achieve growth in sales from a combination of our new product ranges and from replacement business on our extensive installed product base. As a result we continue to anticipate that we will meet our target performance levels for the year as a whole."
My opinion - another nice company. The share price has had a good year, rising decently, and looks fully valued now. The fwd PER is about 18.5, although that is matched by a similar percentage earnings growth, so a PEG of 1 looks about right.
Got to dash, as I have an investor lunch to attend.
Regards, Paul.
(usual disclaimers apply)
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

34 comments
Paul
After briefly looking over DX its not really for me as its simply to competitive, but its reassuring to see your have a more 'hardened' view on this one now, compared to your last review on it.
The hardest thing is to sit on the fence and give a very objective view even if it does look potential value.
Keep up the good posts
Sean
Thanks Sean,
DX. does indeed look value, but I'm increasingly concerned that it may be in structural decline.
Also, I can't remember such a dramatic % share price fall - it dropped about (maybe) 60% on the day, then continued falling, and has never really recovered. That tells me something is really seriously wrong.
I wrongly caught the knife, as it was falling, but I reckon it could be a 0p situation in the long run. That said, management have bought massive amounts of stock personally, which boosted the share price for a while.
I generally pay very little attention to management buys these days. Just look at that lunatic at Tungsten, who did something like a £2m CFD just to prop up a fake share price. It's surprising what Directors when hubris, spur of the moment, and when under pressure from brokers, PRs, and Instis. Believing their own BS - you'd be amazed how many actually begin to believe their own nonsense, after they've repeated it 20-30 times in one day, to Instis, let alone long term.
We've got to be careful. A lot of the people we're dealing with, in UK small caps, are smooth liars.
Regards, Paul.
Thanks Paul for the report on CAKE; I hold a long position and up 30%.
CAKE offers a compelling proposition: High footfall (the shop near me is always busy). A range of premium products which add margin. High volume transactions. Solid investment programme and development of new stores. Free cash flow. Good management team with sound track record.
Expensive but worth it imho and I will be buying more. Can't get enough CAKE!
Absolutely brilliant reader comments today, well done to all contributors!
As the huge thumbs up score shows, readers very much appreciate people with sector experience commenting on how they see various companies - which often shows companies in a very different light to the one that management try to project!
Let's have more of this stuff please! So if you know a sector well, from working in it, or having worked in it, then I'm particularly keen to hear your insights on any company that I write about.
It's very much a team effort here, and I love it when we have high quality reader comments, as we did today! So a collective pat on the back is in order :-)
Regards, Paul.
will89,
You've chosen to start. Please do elaborate on why CAKE will be a letdown.
Scm
Re CAKE. I have held this for a while and am showing a loss. ADVFN is today saying it rose by 6%, but that the Spread is 17.7 %.
That doesn't look very investable.
That spread is incorrect, its less than 1%, in fact its about 1p. It went up 4.8% according to HL. Stockopedia agrees also, spread is 35bps.
I'm not sure the spreads quoted for some stocks on websites are reliable.
Digital look recently quoted a spread of 7.78% for Begbies (BEG).
I thought that was a bit greedy, considering the spread was about 1/3rd of the entire 52 week price range.
However, I purchased some at less than the Digital Look offer price. Then I immediately got a quote to sell a block (but did not sell).
The real spread was 3.81%. Still something I would like to see eliminated, but less than half the value shown on Digital Look.
Ideally, they need to allow people to post flexible orders and bypass the market makers.
DX (Group) (Lon:DX)
Decided to buy an initial holding early this morning and than foolishly or otherwise increased my holding again in the afternoon.
Reasons
The market could have today acted in two ways. It reacted badly as if this hub was the saviour of the company. I think not! My best guess is that the share will return to 21-22p over next few days when the news is more fully analysed. So much bad news is already baked in the share price that a small tailwind of positive news will carry it slowly upwards.
Regards
Dearg Doom
That's a brave contrarian call on DX (Group) (LON:DX.) Dearg. although I acknowledge plenty of thought has gone into your investment decision. I bought in at the time of the first profit warning last Autumn at just under 24p and have yet to see the shares come back above this level.
Re reading the 29th Feb trading statement, there is quite a lot of bullish commentary about new sales being made so far in the first quarter and the company exiting from marginal/loss making contracts. Remains to be seen whether this is just management spin or green shoots that won't be prejudiced by the failure to get planning permission on the new hub. One thing to bear in mind is that the £35m hub was being funded by a developer, presumably on the back of a long term DX lease, so it wouldn't have put the full debt on the balance sheet (although it would have tied them in with a substantial lease). I would be interested to know who is bearing the planning costs etc., for the hub - DX or the developer as these must be mounting up.
I am inclined to give the management the benefit of the doubt pending the next reporting update but resisted any temptation to top up today. It will be interesting to see if either the management make further purchases and/or some of the big II's that bought in at the time of the IPO decide to cut their losses on this latest round of news.
Gus.
Hi Gus,
DX (Group) (LON:DX.)
Thank you for your fair comment.
Originally DX group intended to purchase and develop the site themselves for around 35 million. This figure would have been reduced somewhat by the sale of their nearby depot and some other property disposals.
The lease option was necessitated by need to control cash flow given the markets uncertainty around the firm's future profitability. The development by DX group would have meant a destructive share placing at 10p or less on top of newly created expensive loans to finance the hub. The new hub would have needed to add 7 million to profits to give an 20% return. It may ultimately have just kept the company competitive with low returns.
I reckon the lease option was management's only option and also a poor option given that any developer would need to make a good rental yield on the 35 million investment, plus the developer would get any future capital appreciation and the upward rent reviews. DX group for its part would be tied into a long term lease with no real upside potential or future cost advantage versus competitors.
My main concern as a new shareholder today is that none of DX group direct competitors made money. They seem to go bust with regularity. Here is an industrial sector with very poor returns on capital in an ever shrinking market for its services. it is possible that two or three years out only negative earnings can be earned by DX group in its present format.
This industry certainly looks like a set of lemmings bent on self destruction with price competition. DX group may indeed be a lemming candidate with too small a share of the overall market, DX group possibly does not have either scale, enough hubs, or management skills to flourish,
Some lemmings do survive however. Is DX group one of them? That's the question. My gut feeling is that today was not negative news, Today's sudden share price drop gave me that opportunity to buy close to the recent directors' purchase price.
Finally if DX group can walk away from the hub deal and take advantage of other opportunities, than shareholders at current price may be rewarded. Lots of stale bulls will provide stiff resistance to a major pick up in the share price in the absence of positive news flow.
Regards
Dearg Doom
Hi DD
You make a very compelling bear case given you are a shareholder!
Best of luck , you'll richly deserve your contrarian profits if & when they arrive
This type of debate plus Super Pauly Scott's articles are the very reason I read this site on a daily basis. A huge refreshing difference to the bs on bulletin boards. Thanks very much.
For those who like a bit of TA with their fundamentals there was a decent doji last week from Patisserie Holdings (LON:CAKE) with a strong following candle so far this week on the weekly chart. It 'may' indicate a reversal of the recent pull back. Definetly do not wish to start a black arts conversation.....
DX I believe are still running two distinct networks, one from DX and one from Nightfreight, hence the desire for the new hub. The carrier market is a really difficult mix of marginal volume and margin. Rates are going up across the board but I wonder if it will be soon enough
hi paul re cake they do not give lfl figures. this suggests they were not impressive. however most people say that the shops are always busy when they go past so perhaps they reach their maximum potential very quickly after opening.
CAKE, Luke Johnston does it again, but as he gets distracted or moves to a new role best to sell out.
CAPD, rig utilisation is just going to keep hurting, spread makes it uninvestable. NO
Re Capital Drilling (LON:CAPD) , poor rig utilisation is the spare capacity required for the business to benefit from an upswing, it is cash generative and paying hefty dividends in spite of costs of unmobilised rigs.
Re Spread , yes it is often very wide but I bought in over 20 transactions and only paid full offer one iirc.
Cheers
Thanks for the input
It is unlikely that DX (Group) (LON:DX.) is going to be acquired by an industry player, as others have rightly mentioned that there are already big players, with national networks already.
However, I think there is a chance that a major retailer in the UK might acquire DX, to build out their own delivery network. Amazon is doing this (they are not likely to acquire) because they can control the quality, drive down costs, and offer more innovation (e.g. same day, timed deliveries).
If Amazon is successful, other major retailers like Argos, John Lewis, B&Q, AO.com, etc are bound to consider maybe building their own delivery network. They might not have ambition to ship 100% of orders on their own, but they might want to ship premium or awkward items themselves (i.e. furniture) and offer some flexible shipping options. So I can see a strategic acquisition of DX make sense in this case. At £45m market cap its a doable acquisition size.
Capital Drilling (LON:CAPD) Capital Drilling released a trading statement today. this is possibly my most exciting holding. Its on a p/fcf ratio of about 5, has paid down debt to almost zero over last few years and should swing into profit this year. This is all before any gold price tailwind it may benefit from this year. Through the last few years its continued to generate cash but recent updates look like revenue has bottomed and about to pick up.
I'd be interested in any bearish points on this company - it looks almost too good an opportunity.
Hi Shaun
As you know from Twitter I hold Capital Drilling (LON:CAPD) in size and thus am biased but I should point out it had net cash of $8.3m as at end Dec as per the Jan. update.
I think the downsides are the "challenging" nature of the areas they operate in that could throw a wild card into the mix at any time, if you recall they got trashed when Centamin was unable to pay drilling bills in Egypt and iirc declared Force Majeure. There is also the Tanzania tax issue that seems to be dragging on. However the company has transformed itself and its balance sheet since then and has diversified well , there is a very good presentation here ; http://www.capdrill.com/investor-relations/presentations/
I'm very happy to hold as a lower risk higher yield alternative way to play the commodity upswing which finally seems nascent.
Interesting analysis of Patisserie Holdings (LON:CAKE) which is not yet rated highly by Stockopedia's algorithms. I checked the comparison with Greggs (LON:GRG) and Greggs scores higher on most criteria (I don't hold either stock). Maybe Stockopedia's algorithms don't handle roll-outs very well; is there an obvious reason why that would be so?
The Stockopedia ranks are spot on for this company. CAKE has a quality rank of 87 and growth rank of 92, subject to revision by the latest results. The low value rank of 10 is summed up by Paul's statement "Sometimes we just have to pay up for quality & growth."
Re. Patisserie Holdings (LON:CAKE) ... And Luke Johnson as Chairman. Must admit the high PE has so far put me off. I might nibble this cake.
I agree with Paul that this might be a blessing in disguise for DX. I fear however that it is merely delaying the inevitable. The core business is in terminal decline and I can't see anything that could replace it.
The wider logistics market that they compete in is fiercely competitive with large incumbents (TNT, Royal Mail etc), low barriers to entry and massive power on the buy side (Amazon et al) which from a strategic perspective is a bad place to be. Pretty much as bad as it can be to be honest.
Unless the (very well paid) CEO and CFO can find a way of entering a different market but re-using the people and property and any IP they have within the company, I fear for DX's long term survival.
Surely scale of the network is a barrier to entry in this business? If you have 5 trucks and 1 depot you're going to have trouble offering nationwide delivery, aren't you?
There are barriers to entry at a countrywide level but there are thousands of local delivery firms who cover a small area that the big players hand items off to for the "last mile".
A number of large users of delivery services are very adept at leveraging this somewhat fluid but generally cheap route for delivery. It's almost a "last mile delivery cloud" type of thing. Cuts the likes of DX out of the picture completely.
When I last heard the DX exec team speak they were trying to emphasise the quality of the their drivers and how well vetted they were etc. but people very rarely care about that. The seller chooses a courier and takes the risk and 999 times out of 1000 they will go for the cheapest and accept the risk of occasional replacement items.
Hi Paul,
Interesting thoughts on DX, I actually come across them at work, as we ship what couriers would call 'ugly' freight, essentially large boxes that don't weigh very much.
DX obviously bought Nightfreight, who were one of the traditional couriers for this type of freight (and we had used on and off for a long time), but last year I got DX in to see us and they said that the freight didn't fit their business model any more.
Our currently setup is basically - 1 box: DPD, 2-40 boxes: Tuffnells & TNT 50/50 split for risk management, then pallet networks for pallet deliveries and different again for full lorry loads. There is a clear split in the market between those who are targeting home deliveries (DPD, Royal Mail, Hermes etc) and those who don't want to. Tuffnells charge a £6.80 surchage on a consignment to send it to a residential address. TNT charge just under £2.
Importantly for us, we send to all kinds of recipients from distribution centres to cul-de-sacs, and the customer size doesn't necessarily dictate the order size. We might send a 20 box or 2 pallet order to a house, but today for example we are sending out 476 single box consignments (by DPD) to individual stores of one of the supermarkets.
In the residential market it's a race to the bottom. DPD and Royal Mail have good infrastructure setups and seem to be thriving - we've all made use of the DPD 1 hour delivery window with text alerts etc etc, they've invested in that and it seems to be working. Hermes, Yodel etc are becoming renowned for damages and throwing your parcel over a wall into your flower bed. Hermes pay the delivery driver 50p per delivery, so it's not really surprising...
Anyway, TNT have now told us that we were given fantastic rates 'by a rogue salesperson no longer with the business' so are now going to start volumising the freight, which counts them out, so our 'mid-size' consignments are now going to all be heading to Tuffnells (Connect Group) because we've run out of other options. This is where Nightfreight (DX) would traditionally have competed. Tuffnells will charge you a consignment charge then a small charge per kilo, which allows larger quantities of boxes to be sent and suits our type of freight. DPD, RM, Hermes, Yodel etc charge a flat box rate where you simply pay a charge per box shipped. We like to split our freight between various carriers to prevent a City-Link type situation, but it's becoming harder and harder.
DX are surely in terminal decline as you say. They have a very bad reputation for damages in the industry, and they are clearly being very picky with the type of freight they are agreeing to carry, which is fair enough, but must be limiting their growth potential. DX bought a lot of equipment (cages etc) from City Link when they collapsed, and I would put money on them going the same way in the mid-term. The move from the classic DX business of legal papers and passports to integrating Nightfreight, often affectionately known in that industry as Sh**efreight, was actually a very (too) big jump and change in freight profile.
The only consolation may be consolidation. It's an industry where takeovers are becoming more prevalent - purely from the couriers I've mentioned; Fedex have bought TNT, Tuffnells were bought by Connect Group, DX bought Nightfreight. I wouldn't be surprised to see some of the Hermes/Yodel/DPD/Royal Mail smaller freight types acquiring/being acquired at some point. I'm not sure who I could find to buy DX though! You have to remember that these businesses are often bought for their infrastructure, and (generalising slightly here) all the big players now have a hub in the places that they want one. The best current example (don't hold me to this in 10 years) of a 'good' takeover is TNT. Fedex have bought them because of their large European and UK networks, which Fedex don't really have themselves.
Connect Group is a funny one, and I'm unsure of the future both from a personal (business) point of view, and an investor one. Tuffnells can't be making much money at all on the freight they take from us. There will come a type where, like TNT, they evaluate this and realise they need to focus on higher margin business (so they'll volumise our freight, because they need to get the correct revenue for the space it takes up in the lorry), which will cause some problems for us but won't be the end of the world. Currently we can send 30 boxes of goods that weigh say, 120kg (very light), for under £30, but that takes up a huge amount of space for the courier, so we'll probably end up needing to send more full pallets at a slightly higher cost in the longer term, as these mid-size couriers become more picky with the freight they carry. They're trying to become more efficient and focus on the higher margin business, but that's a completely flooded market.
Understand this isn't directly related, but thought it may be interesting. We are yet to resort to Yodel...
It's always interesting to hear about the industry sector dynamics of a company Paul covers, so thanks for taking the time to provide these insights.
Excellent post; just the sort of thing one hopes for on this site.
An excellent post wgadsby1 - always good when posters speak up of their real-life experiences of the shares discussed here - many thanks.
DX (Group) (LON:DX.) is not a business that I would in any way want to invest in (lost money in Business Post years ago so won't make that mistake again). Too much competition, heavy investment required, and no real 'moat' to stop others. Also the lack of business common sense of delivery companies continues to amaze me - I lost count of how many times delivery companies would try to deliver to a residential address during working hours - and would continue to do so 3 or 4 times, when most working people are at work! The amount it must cost them in failed deliveries must be substantial... doesn't apply to business parcels of course. Resolved this issue by using Doddle, a service that is well worth the cost.
Anyway thanks once again, always heartening to hear of real-world experiences.
Thanks for sharing relevant experience. I've held Connect for a while and thought Tuffnells a good purchase, so let's hope they can nudge their pricing up with you, just a little bit, not enough to send you elsewhere, but... :). Seriously, we'd love it if you re-posted at the end of the year to tell us all how the delivery world has changed, or not, for you.
Thank you for the replies, I'll make sure I update later, we're a very Christmas focused business so it's always interesting to see how the different couriers cope at that time of year. Shipping is such an integral part of our operation, the whole business is reliant on it, and the courier is representing our business to our customers. As an industry I think there is much room for improvement!
I'll endeavour to add a few 'real world' comments as and when it seems appropriate and non-confidential, as our customer base includes many of the retailers that Paul comments on.
With lots of the retailers it's always interesting to see the insights that our sales team have on the approach of the buying departments of different companies, some are much more efficient and organised than others, some with heads in the clouds and extremely 'creative' and some with very grounded, realistic objectives, or at least that's the gut feel you get when working on projects. It's often obvious whether or not this is a yardstick for the effectiveness of the underlying business, and it can be very apparent if there isn't much top-down guidance going on. The screams or cheers of the accounts/credit control department can also be a useful indicator. It can act as a useful counter to simply looking at the company results.
Don't get me started on Patisserie Holdings (LON:CAKE)... I think it'll be a letdown!