Small Cap Value Report (18 Oct 2016) - G4M, AVON, DOTD

Good morning!
More interesting news about the retail sector. I'm very fearful about this sector, and think it's generally best avoided at the moment. This is due to multiple headwinds - online is increasingly eating their lunch, plus overheads are rising fast (Living Wage, etc). The latest one - much higher input prices feeding through in 2017 due to weak sterling, could I think crush a lot of smaller retailers that have only just been hanging on. Plus margins are likely to be squeezed across the board, for all retailers.
This article makes some interesting points. There's evidence that consumers are tiring of buying "stuff", and are now prioritising holidays and entertainment (meals & nights out) ahead of adding to already groaning wardrobes.
All in all then, I reckon a lot of apparently cheap retailers could turn out to be value traps next year. So caution is definitely needed there. Which brings me on to probably my favourite GARP share at the moment, in a sector which is rapidly transitioning online.
Gear4Music (G4M)
Share price: 334p (up 5.7% today)
No. shares: 20.2m
Market cap: £67.5m
(at the time of writing, I hold a long position in this share)
Interim results for 6 months to 31 Aug 2016 - if you follow me on Twitter, then you'll already know that this is probably my favourite GARP (growth at reasonable price) share at the moment. The company is an online retailer of musical equipment. It operates about 17 websites across Europe, with the UK being the biggest market. It's based in York, and has been established for about 13 years. The founder CEO is still by far the largest shareholder.
The stock market is attributing very high valuations to growth companies. I'm not saying that is necessarily correct (as I think some valuations are too high now). However, if you spot something with outstanding organic growth, then it can pay to pile into it whilst the price is relatively cheap, because the rating is likely to expand dramatically once other people also spot it. That worked brilliantly for us with Boohoo.Com (LON:BOO) between Jan 2015 and now, I know a lot of readers joined me in that one (which I no longer hold personally, as the price seems quite high now).
For me, G4M is not dissimilar, although it's more niche. So some people question whether its addressable market is big enough? The company says that it's 4bn euros, which seems a fairly decent market to me. G4M's strategy seems to be a land grab for market share, on lowish margins, and it's clearly working. This sector is rapidly moving online - conventional retailers simply won't be able to compete against such a huge product range, and low online prices, unless they're a niche within a niche. I'm looking forward to meeting management this Thursday.
On to today's interim results - the key figures speak for themself. Here's a screen shot, which saves me having to re-type it. Comments below on the items I've highlighted.
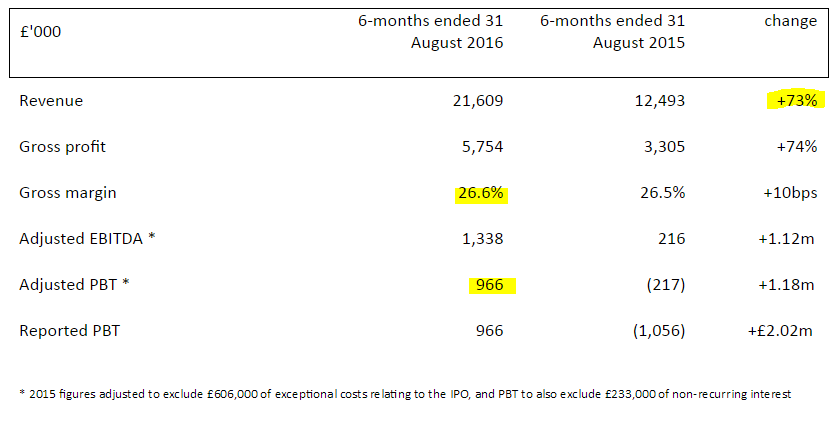
Spectacular organic growth of 73% was already flagged up in the trading update which I reported on here on 6 Sep 2016, so that's as expected.
In the past, I've worried too much about the low margins achieved by G4M, but for me the penny dropped recently that this is an irrelevance. The stock market is interested in top line growth, rather than profitability, right now. Again, I'm not saying that's necessarily correct, but that is what's going on, and it's a good way to make money by observing what the market does.
With G4M, it will be able to gradually raise its margins as more own-brand product feeds through, and volumes rise. Also, Amazon has shown how the way to dominate online is to keep prices & hence profitability low, then you can switch on the profit engine later, once you totally dominate a market.
Note also that the average order size is quite big, at £125.64. So whilst by comparison, fashion retailers may boast larger % gross margins, their basket size is usually smaller than that. So the gross margin per order in £ terms for G4M looks just fine to me, even though 26.6% gross margin may look low.
G4M has fantastic customer service too - which is the way to build customer loyalty & market share. Their TrustPilot reviews are generally superb, at 9.5/10 for a large number of customer transactions overall.
Valuation - how to value it? For hyper-growth companies like this, you're missing the point if you try to value it on a conventional basis, using the PER. Nonetheless, it's always reassuring to at least make a stab at that, and then accept that the PER will look very high for a while, until earnings growth brings it down again.
Broker upgrade - Panmures is the house broker, and has put out a very upbeat note this morning. This raises their price target from 200p to 400p. I usually ignore broker price targets, but in this case the valuation comments & calculation look sensible to me.
Panmures has raised its forecast for the current year's profits by 22% to £2.0m (year ending 28 Feb 2017). This results in EPS forecast rising from 6.0p to 7.7p. That gives a current year PER of 43.4.
Yes, that looks expensive to most of us. However, I would say that 73% organic top line growth justifies a high PER. This is cheap compared with some other online retailers, yet the growth here is out-pacing that of most others.
Also, I reckon the new profit forecast looks conservative. There is a strong H2 seasonality to G4M's business, so there's plenty of chance it could beat the revised forecast. Indeed, Panmures says today that its revised forecasts are "conservatively framed".
Panmure's forecast for FY18 is 11.4p EPS, giving a PER of 29.3, which looks perfectly reasonable to me, given the growth going on here.
EDIT - there's a new commissioned research note out today from Edison, click here.
Capitalised development spend - is fairly modest, at £600k in H1, compared with an amortisation charge of £277k. That looks reasonable to me, although the net figure of £323k is the amount by which H1 profit is boosted from this accounting policy.
I like the news today that the software development team is being brought in-house.
Outlook - everything seems to be going great;
"Accelerating sales growth into Europe, which represented 40% of our total sales during the last two months of the period, has reinforced our decision to expand our distribution capacity in Europe and further enhance our customer proposition.
"To underpin our strong growth and physical geographic expansion, we are pleased to announce that our software development team will be brought in-house and, with further recruitment planned, expanded even faster to ensure we continue to build a market leading e-commerce platform.
"Whilst we continue to invest to grow the business it is pleasing to have generated significant profits during the last six months, when historically we've produced the majority of our profits during the second half of the year.
"Trading remains strong heading into our important Christmas period and the Board considers the Group well placed to deliver results for the full year that will be ahead of its previous expectations"
The key sentence being the last one - trading ahead of expectations. It's always good to see that. Also note how Europe is expanding very rapidly. Within the 73% total sales growth in H1, Europe grew at an astonishing rate of 169%!
Two new European distribution hubs are being opened, which will improve delivery times into these rapidly expanding markets. So we should see very strong growth from this company for some time to come I think. It's already gearing up for £100m p.a. sales. You could probably double that, looking a couple of years further out, at which point the current market cap of £67.5m would possibly be a distant memory. That's what I'm hoping for anyway, and it looks achievable.
Seller this morning - I was puzzled why the share price was initially marked down this morning by 8.5p, and remained stuck there for about an hour. There was a seller drip-feeding out stock through Panmures at 310p, which private investors were hoovering up relentlessly.
Just after 10am this morning some very large trades (totalling about 3.5m shares) went through at 300p. This could well be the former private equity owner, Key Capital Partners, selling out, as they've been top-slicing previously. I hope it's not the CEO selling some of his holding, but there again you could hardly blame him for reducing somewhat, given that the price has more than tripled in recent months.
Anyway, the RNS will no doubt reveal all shortly. Quite a bit of the shareholder register has changed today, and it's good to see a big shareholding being fragmented into retail buying, as this will improve liquidity and should narrow the spread too.
EDIT at 16:14 - we now have more information on who the sellers were, as follows;
Andrew Wass (CEO) sold 400k shares. Remaining shares held: 7,887k (39.1% of company)
Dean Murray (NED) sold 75k shares. Remaining shares held: 250k (1.2% of company)
Key Capital Partners sold 2m shares. Remaining shares held: 829k (4.1% of the company)
I was right that the main seller was likely to be Key Capital Partners, as they've been top-slicing previously. As regards the CEO top-slicing his own personal holding - personally I don't begrudge him selling just under 5% of his total shareholding. So not a problem from my point of view.
I wonder who the buyers will be? A certain amount has been fragmented into private investor hands, which should help liquidity. As for who bought the bulk of the shares sold, we'll have to wait & see. There should be more "Holding in Company" RNSs out shortly.
As with practically all recent floats, the City firms pay no regard to the need for liquidity post flotation. They just want to bag their huge fees as quickly & easily as possible, by placing the shares with institutions, and usually leave behind a very poor ownership structure - with large, lumpy holdings, and hence no after-market. This needs to change. However, it can also create nice opportunities for those of us who sniff out bargains, where a company is overlooked because few PIs have researched it yet.
My opinion - as you've probably gathered, I love it!
People tend to "anchor" to a share price, and be reluctant to buy a share that has risen a considerable amount already. Personally I've been trying to unlearn this very bad habit. It's all about fundamentals, and if the fundamentals have dramatically improved, then the share price should be a lot higher.
If market conditions towards growth companies remain as positive as they are now, then I could see this share reaching £5 (c. £100m market cap) in the not-too-distant future. Longer term, I'm targeting considerably more than that. As we saw with BOO, once the institutions start scrambling over each other to build a stake, they will chase the price up to levels that most private investors wince at. So I think there is a strong case for running positions in growth companies to an over-valuation in this current market, if you have the cojones to do so. I didn't, and sold my BOO shares far too early. Still, hindsight and all that.
Now of course, things can go wrong along the way. Rapid growth often leads to bumps in the road, which are particularly painful at highly-rated companies. Competition can intensify, etc. So nothing is a given.
Overall though, on just under 30 times earnings for the new financial year starting on 1 Mar 2017, yet achieving stellar growth in Europe, I really don't see this share as expensive right now, despite its explosive move up. I've actually bought more today.
DYOR as usual, but if I sound very upbeat about this share, that's because I am! It's one of the best opportunities I've spotted in some time.
More bearish views on this share are encouraged - I need dousing with some cold water, so if you take a negative view on this share then please do post in the comments section below, to stop me getting perhaps over-excited!
Avon Rubber (LON:AVON)
Share price: 1006p (up 0.6% today)
No. shares: 31.0m
Market cap: £311.9m
Trading update, and FD leaving - personally I always find it unsettling when an FD leaves a company, as it can be a warning sign of trouble ahead. There again, I can understand why the FD here wants to move on after 8 years - that's the sort of timeframe when you're bored with a finance job, and ready for something new.
Mind you, today's trading update sounds fine;
We are pleased to report that the financial year has concluded in line with the Board's expectations on both sides of the business.
In Protection & Defence, in September we received a non-DoD order for 15,000 mask systems which will be delivered in the first quarter of our new financial year.
In Dairy, the global milk price has continued to increase, which provides an encouraging backdrop against which to start our new financial year.
Our balance sheet remains strong, and good operating cash flow meant the year concluded with net cash of £2.0m (30 September 2015: Net debt of £13.2m).
As you can see from the Stockopedia graphics below, it has high quality scores. The dividend yield looks mean - I wonder if there is scope to increase that?
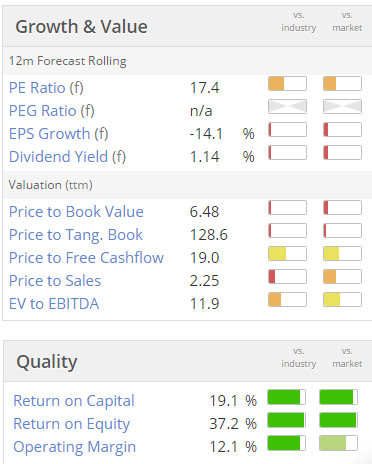
Overall - I don't have a strong opinion on it either way, but recognise that the company has performed very well in recent years, with excellent earnings growth.
dotDigital (LON:DOTD)
Share price: 53.2p (down 2.2% today)
No. shares: 294.1m
Market cap: £156.5m
Results, year ended 30 Jun 2016 - it seems rather late to be publishing results for a June year end. However, the numbers look good to me. It's another year of decent growth in turnover and profits.
Diluted EPS has risen 13.7% to 1.83p - which translates into a PER of 29.1 times - that looks a very punchy rating for good, but not spectacular growth.
Net cash has risen to £17.3m - the company appears to be hoarding cash. Although it does mention special divis today. In valuation terms, the net cash is now 11.1% of the market cap. Hopefully at some point shareholders might either receive a meaningful special divi, or be delighted with an earnings enhancing acquisition. Doing nothing with a cash pile seems a wasted opportunity, given that DOTD has reliable recurring revenues - so doesn't have to worry about future cashflow.
Outlook - there's quite a lot of detail, with points covered being;
- More international expansion
- Developing partner relationships
- Integration with other software packages
Overall:
...well placed to continue to generate strong organic growth not only from the markets it currently operates in today but wider into the global markets it is looking to enter.
My opinion - I've only skim read the narrative, having already decided that the price is too high for me. Nice company, but looks fully priced, and perhaps not strong enough growth to justify a rating quite this high?
All done for today. I didn't manage to cover all the companies I intended. However, I'm tending to concentrate on the most interesting company results of the day, as after all we all want to make money, and not waste time on unremarkable companies & results.
See you in the morning!
Regards, Paul.
(usual disclaimers apply)
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

48 comments
I bought following your article 6th. September . I'm not complaining about a 60%+ rise in under 2 months.
I was under the impression that G4M was the sole specialist internet operator for music instruments.
Definitely not the case. Netherlands based Bax Shop for example also operates through a UK branch,
selling music instruments on the UK net at low prices. Makes me feel G4M could be up against stiff competetion from various overseas based specialist Internet sellers.
The flip side, looking at the above chart, is that £G4M currently have just a small fraction of market share which does give a lot of opportunity for growth by eating into others.
G4M would need to eat into others a good bit to warrant current market cap, IMHO.
Paul, any comment on the valid point lenart raised about the stokopaedia earnings manipulation risk with regard to G4M
I think people will view and test music instruments in shops, then go and buy on the Internet. Not nice for the shops, but that's likely to happen.
Just a quick thank you to everyone who posted positive & negative comments on G4M. It's great to have a sounding board here, where all views are encouraged, not just one-sided positive ones. I always think that, if you're long, listening to bears is the most important thing. You can only really be positive about a company once you've thought through all the negatives, and reassured yourself that they're not a concern (which remains my view with G4M).
Regards, Paul.
On the BOO point. I remembere the Burntsfield fire when ASOS - which I was then considering- dropped like a stone to around 98 and I thought it was a busted flush., but we know what happened. Up 50X approx. Boo on that comparison has from the drop to 20p has a long way to go. Surely?
I'm surprised nobody has commented on the director sells yet.
Hi ricky65
Paul has commented in the updated article. I guess liquidity is generally thin so the only time to sell is when then the PR floodlights are on at results time.
ricky,
I've already update the main article to cover the large sells today.
The CEO has sold 400k shares, which is under 5% of his holding, so personally I don't have an issue with that - he still holds 39% of the whole company.
There's also a 75k NED sale.
By far the largest, 2m share sale is the exiting Private Equity former owner. They were already on their way out, so no issues with that either. It's only disclosed as a Director sale because one of the NEDs is an appointee of the PE firm.
So it's pretty much worked out as I expected - I stated this morning that the big seller was likely to be Key Capital Partners, which it was.
Regards, Paul.
Paul, thanks for the reassurance. After the recent good run I'd probably have top-sliced myself if I were the CEO. Good call on the Key Capital Partners sell.
I think I will sleep better holding shares in Amazon than in a small competitor like G4M. I'm not optimistic that G4M can ever own the territory enough to drive up their margins without getting squashed by Amazon.
Excellent article and your enthusiasm for this stock must be admired.However,it seems a very straightforward business....buy in musical instruments and then sell them on line.Where are the barriers to entry? Perhaps explains the low gross margins?
sorry to be negative
I'm no expert on these things but when I started my children on musical instruments (violin/ cello) I needed to go to the shop to get expert advice on sizing- and as far as I'm aware professionals like to play an instrument before buying to get a feel for the sound/ tone/ comfort/ size etc. So I can understand purchasing amps etc online but this seems a little more complicated. I would imagine that shops who are willing to match an online price will survive.
Re. £G4M Here is an interesting tabulation showing how this company compares with EU competition. About 18 months out of date, but good enough for a general overview.
Source: Admission Document.
Paul ;
An interesting article; thanks for the headsup; they seem to be doing all the right things and emphasiing customer service including speedy safe delivery. When you meet with them please establish their view as to why they believe the price took off in Aug 2016 .The first annual report was then but Prelims were back in May 2016 but not a flutter until formalised. Please add a few notes to your blog on the meeting.
"Not sure about buying a group of developers either. I know that industry well and they are pretty much the least sticky staff you can imagine". I know that industry very well, and outsourcing development is what makes them not sticky. Many companies in many industries these days are suffering the rarely perceived hidden costs associated with the myth of the fungible developer - remember that the next time your bank's ATM network goes down or their payment system fails. By bringing it in house, they have a chance of improving things. If they do it right. The technology is key to these companies success. A risk factor to consider is that they may not do it right.
I think G4M is an interesting one, it's a marketplace that I vaguely know, having been a semi-professional Trumpeter in a past life.
I think the key marketplace is youth, the number of late school/college age people who 'form a band' and need to buy some equipment is huge, and the push on the homepage seems to be towards 'cool' instruments rather than more traditional brass/woodwind etc. If I was a 17 year old who wanted to buy an electric guitar to appear cool to my peers I would probably be looking online...?
When I was a kid we had a fantastic brass instrument shop in town, and I've keenly watched their evolution (as a much smaller business) over the years. As has been mentioned above, by the time I was wanting to spend £1000+ on a Trumpet I would need to go in and try it, but the range on G4M seems good even at the top end where I expect sales are tiny. Equally, they sell plenty of own brand trumpets in a much lower price bracket that I am sure the margins and volumes are better on. Interestingly even 10 years ago my local shop had an own brand range, so that in itself doesn't say a huge amount.
I actually had a chat with the online manager of the local shop recently (yes they now have an online manager) as they were having some development work quoted by our web developer and wanted a referral. He said that something like 80% of their sales are now online, with the volume market being schoolchildren, and they do very well with lease type agreements both to educational establishments and individuals, perhaps a growth area for G4M? If interested, the business is 'John Packer'.
I think this is going to be one that might fly for a while, and then hit a bit of a growth wall, so I'm in for the ride at the moment!
Hi,
One of the things I try to do in life is to find things that work and try to replicate as much of what worked as possible. It has done me proud in a huge number of scenarios from cleaning up my diet, getting more sleep, even ultra running - simply find somebody as much like you as possible, and copy what they did and generally, hey presto, target achieved.....
I do the same with my investing, analysing the best investments I and others like me have made and trying to find similar stories and situations.
Which leads me to £G4M. The parallels with Boohoo.Com (LON:BOO) are there but there are some key (to me) differences.
- One thing that is in BOO's DNA, part of their USP, is their ability to pick clothes from a huge range that will sell and are selling and sell more of them. Not sure there is quite the range of violins to choose from that will enable that differentiation for G4M.
- Amazon would not find it hard to muscle in on G4M. Indeed, an earlier post has found 27 different ways of buying an identical item. They'd (or anyone else) find it much harder to do that to BOO.
- BOO have the advantage that fashion changes four times a year. Whilst people take up musical instruments all the time, they tend to only do it once or twice.
- Nobody really buys second hand clothes. Why would you? You'd get them new from BOO. Lots of people buy second hand musical instruments though, particularly beginners who are the key market. Ebay is awash with second hand instruments.
Not sure about buying a group of developers either. I know that industry well and they are pretty much the least sticky staff you can imagine so it's likely that a lot will have left before long leaving not much behind......surely let somebody else carry that risk?
On the other hand, average order value is good, they are growing revenue and the inventory should not lose value in the same way clothing does.
I'm not saying G4M is a bad investment, just trying to draw out some differences between it and Boohoo.Com (LON:BOO) with which it has frequently been compared.
Disc - no position in either (any more).
JDW72
Hi Paul,
Thanks for in depth and interesting report as usual!
Any thoughts on UTW? Results today look good, debt down and cash up but eps slowed and share price still going nowhere!
Syd.
Hi Paul,
Thanks for your report. Despite some of the comments above I'm very encouraged. I read the report this morning and couldn't understand why the price was down. It would be interesting to know how much of their sales relate to instruments to school students as that would seem to be a huge, but price sensitive, part of the market where people will be happy to buy online if the price is right.
G4M certainly made my trip to your Brighton ShareSoc meeting worthwhile.
Thanks, Roger
Paul
In answer to your call for bearish comments, the following para leapt out at me from your article:
"In the past, I've worried too much about the low margins achieved by G4M, but for me the penny dropped recently that this is an irrelevance. The stock market is interested in top line growth, rather than profitability, right now. Again, I'm not saying that's necessarily correct, but that is what's going on, and it's a good way to make money by observing what the market does."
Wasn't valuing tech businesses by sales not profit a major sin of the dot com boom?
Accepted you can speculate on the price rising because of what other market participants do, but as an investment it doesn't stack up unless you think it will generate future cash returns from profit so by definition there's shed loads of assumptions and execution risk. Not saying you're wrong to buy it (and I will have a closer look myself) but surely whether revenue growth is profitable is never irrelevant.
Have not looked into G4M but a few thoughts out loud from a quick glance after Paul's report this morning would be:
1) 40% of sale going to Europe must raise some questions regarding potential issues once actual Brexit takes place next year? (local distribution hubs being set up may mitigate some of this but not all risks). There is a lack of global diversification presently to offset any such effects too.
2) Where margins are small as here currency effects can have a major impact. Where do they source the equipment from? If any of it is outside UK then sterling depreciation will be a hit to margins in the UK, assuming they can't raise prices in line with that (would be good to know if they have any room in terms of competitiveness to lift prices outside UK due to Sterling depreciation - i.e. pricing the at same level in Euros despite sterling depreciation - helping them on the Euro sales side). They will make a limited win back in any event on Euro denominated sales translating into Sterling, but since Sterling depreciation against Euro has not been (and probably not likely to be going forward) as dramatic as against Dollar and other global currencies they won't get quite the same tailwind from this as the more globalised businesses have done. Unless they have managed to currency match using their Euro revenues for Euro stock purchases of course (if they buy from Europe) which may help offset the effect of this. Won't help them if they have to buy stock from US or other sources of course.
3) If we do find ourselves facing a drop in consumer spend next year if things get tough in the broader economy then discretionary spend on recreational music gear would likely take a hit? With such a high rating it probably wouldn't take much to rattle the stock?
4) Sales figures comparisons this year will be flattered by Sterling decline but this will be a one-off benefit (unless the plunge in exchange rate continues into next year). Continuation of low Sterling would aid competitive pricing in Europe but , as above, all depends how much of their cost side is non-Sterling based and how much this undercuts the European sales side currency benefits.
I have no view either way on this company having not looked into it in any detail, so the above are just some initial musings.
Not being a musician I picked a bit of musical equipment from the European Website mentioned above & did a search for a Fender Mustang III V.2 (an amplifier). Widely available via Amazon and others at same £235 price as G4M. Google search they didn't seem to be anywhere on the first page as far as I could but a one shop operation in Guildford at the top! Google's shopping tab listed 27 online sellers listing it at same price.
So not too sure what their USP is or how people would find them on this limited basis? I guess their own label stuff might be cheaper & more profitable for them. I see the operating margin was only about 4% - where do you think that can get to as 1x+ sales seems a bit rich at this point.
Looks like a classic growth / momentum stock not my kind of thing but good luck with it.
Paul,
£G4M cash flow statement shows they are still loss making...does this not worry you ?
i avoided it for this reason.
Hi truegent,
The cashflow statement looks fine to me, for G4M, given where it is in terms of very rapid expansion, seasonality, etc.
Maybe I've missed something. What in particular concerns you?
Regards, Paul.
hi paul, cash generated from operations was negative, plus a further cost for capitalized dev costs....so reported profits are no where near free cash flow, which is actually negative and was in last prelims too....do you not see this as an issue ?
thank you.
Paul
I don't think the cashflow statement says that?
There is a significant movement (£2.5m) in working capital that results in negative operating cashflow, but that is the buildup of stock for the Christmas period, and is highlighted in the first page of the statement.
i guess so....but a loss is a loss and to this day they havent made a single penny...so for me, reported profits need to start translating to cash....
I think that the point about working capital movements is that they are not a loss at all, they are changes in the amount of capital held as inventory vs. cash. Its absolutely normal for a retailer with a Christmas season weighting to have more cash and less stock in February; and less cash and more stock in October... which is what the accounts state.
As a music nut, I have used both G4M and Thomann extensively to buy equipment for my band. Both are very good, (though as an investor I wish that Thomann was listed, as that is a business that Warren Buffett would be proud to own a piece of).
I've also observed the steady decline of local music shops over the course of the last few years as they found it harder and harder to compete. That process isn't over yet, the economics of music equipment are massively in favour of large distribution networks, as the stock has an indefinite life and customers value as wide a choice as possible. I think that there is still a lot of room for growth in this market.
If you look at Thomann, the undoubted market leader, their aggregate customer base is 7.8m. Getting an equivalent number for G4M is difficult as its not clear whether Thomann's figure is a lifetime number or an annual number, but assuming lifetime then G4M is probably just clearing 1m.
So, accordingly, I'm in. The warning sign on this kind of business is Inventories, currently 9m (and up 50% on the corresponding low point in February, post Christmas). It will be interesting to see what the position is at the start of next year.
Hi Paul
Thank you for an excellent piece on G4M.
FWLIW, you may wish to correct "334p (down 2.4% today)". For much of this morning G4M was trading at 307-310, down 2.4%, albeit it was really 310 on both the bid and the offer.
Cheers, Martin
Hi Shanklin,
Ah well spotted, thanks. I will correct that error.
What happened was that I started writing the article when G4M shares were down, but then the price moved up so much that I thought I'd better amend the market cap bit at the top. But it looks like I overlooked the need to change the percentage too - doh, schoolboy error, sorry!
Thanks for pointing out my mistake.
Regards, Paul.
Hi Paul
It seemed churlish to mention it but I thought it might be useful as and when people look back to today's report in a few month's time.
Cheers, Martin
Hi Martin,
Not churlish at all - if people spot a factual/figures error, then I definitely want them to flag it to me, so I can correct. Minor spelling mistakes, where it was obvious what I meant, less so.
So thanks again for flagging.
Regards, Paul.
G4M
Stockopedia thinks Earning Manipulation Risk is high. 4 red flags! The rise in turnover is extremely brisk. Both important warning signs. This may well be a Story Share.
Lennart
What jumped out at me reading the results this am was this line ..
- Property lease signed on German Distribution Centre.
Looking at Edisons research note quickly Thomann is G4M biggest European competitor with 12.8% market share and over 500M turnover. The company is also German so interesting that Gear4 are setting up shop here. Having had a look at Thomanns website looks a bit naff and dated but i do have a bias as i hold G4M.
Could Gear4 start picking and nibbling away @ Thomanns lunch? Food for thought..
Lovely top up this morning and off it goes again.
From experience of raising kids in Scandinavia the music element of schooling is far greater than here in the UK so to me its an exciting market that isn't diminishing (as some of the negative stuff out there today seems to suggest).
Surely their main target market isn't established musicians that would require extensive testing of product, but the European scholastic market which is vast and growing all the time with the arrival of many school age migrants. We had to buy my daughters umpteen instruments some of which they had never played before, if only then we could shop around on the net.......!!
I agree with herbie47 above. Thomann has been around and quite impressive with decent prices for some time. I am also part of both of these suppliers target market, but have never bought from them, nor ever will do. Basically, if you are buying a musical instrument there is much more than just look and price to consider, and will travel to test/try the right gear. Online, no thanks.
So, maybe they have some growth to come, and so far, as Paul points out, growth looks good, but there is ceiling here, I guess. Having just looked at their site, I am wondering what, if anything, they are doing better than Thomann? Not for me.
TT
Hi Paul - £G4M I share your enthusiasm about this company and today's results are outstanding. I have been building up a stake since July and topped up again today.
To take up your request for anything bearish to mention, the company is planning on opening two distribution centres/ hubs ove FY2017, one in Sweden and the other in Germany. That will require capital expenditure. However the figures are not significant in the scheme of things; unlikely to make a major dent to the bottom line.
The other comment I would make is that a high PE ratio for such stocks is not a factor to worry about, as you say. Here is a mathematical example to make my point.
- Say you have a stock with SP 400p and EPS 10p, making a current PE = 40.
- let's assume eps growth is 50% p.a. over next 2 years.
- so the forward PE after year 1 becomes 400 / 15 = 26
- and the forward PE after year 2 becomes 400 / 22.5 = 18
Another example of the magic of compound interest.
In the context of this stock, a 50% p.a. growth rate is not blue sky. Edison reckons their EU market share currently is only 1% .
Isn't it all a bit A&O'ish? Unlike clothes how many pianos/drum kits do you need? Keen prices though!
Surely amazon could easily obliterate them? That is what has kept me away, perhaps I'm incorrect?
Panmure is G4M house broker, they have put out an upbeat note and increased the target price, yet they have been dumping vast amounts of institutional stock to easily led twitter, guru, pundit and blogger following private investors. A classic scenario of modern times.
ericb,
How do you know the buyers of G4M stock today are "easily led"? (answer: you don't, you just made an assumption).
Surely people are buying the stock because the company has just reported excellent results & outlook? That's why I bought more shares this morning. If an Institution wants to help out by feeding liquidity into the market, that's fine.
Have you read the Panmures note? If you do, you'll find that it's fact-based, and all perfectly reasonable. If anything, they're under-forecasting. So there's no evidence whatsoever to back up your claim that they're publishing bullish updates in order to facilitate a seller. Their last note flagged that forecasts would probably be raised. In fact, they inexplicably held forecasts too low before today, in my view.
I think sometimes people think it's clever to be uber-cynical. But one needs to get fully informed on the facts first.
Paul.
Paul
You asked for bearish views, so I gave you an angle on the big share placing this morning. You have seen previously how private investors can be easily led into stocks by following guru and twitter comments, so there is plenty of reason to suggest there is evidence of that here too.
However its just as easy to look for other explanations, depending on whether you are cynical or over excited.
I didnt think I was suggesting Panmure was publishing bullish updates in order to facilitate a seller, more that the large sales being handled by Panmure were at odds with the enthusiasm they have for the stock.
I remind of your statement above "I usually ignore broker price targets, but in this case the valuation comments & calculation look sensible to me." I certainly usually ignore Panmure notes as they are often the wildest out there for variable quality. But I guess even Panmure can look sensible when over excitement kicks in.
£G4M results have all the right headline figures and glossy internet sales excitement, but there is a lack of actual cash building up and alot of expenditure coming up to grow the business. Certainly not enough for a dividend.
So these are all things to consider when looking for bearish views, this is what makes a market and should be encouraged rather than brushed off as being clever. Is this another AO World (LON:AO.) in the making ?
Paul, my main concern about £G4M is the margins are very small, there is also a well established online retailer in Europe in Thomann, they are quite large, 1,200 employees and over 7m customers.
Was a buyer of G4M first thing this morning, must have been a big seller in the wings. All harmonious now ....lets hope they treble.
Regarding retailers what did you make of the phone conference with Crawshaws yesterday?