Small Cap Value Report (19 Jan 2016) - ZYT, TSTL, DOTD, XLM, STM, FRP, MYSL, JDG, JPR, QP., SCS

Good morning!
Looks like it's going to be a bounce day - with the futures up strongly, apparently due to positive Chinese economic data. Although there seems a great deal of scepticism over how much we can believe such data, in line with pretty much everything that comes out of China - e.g. the garbage that they have floated on AIM, along with fictitious accounts in many cases.
The big question for lots of us, is whether we should be buying the dips, or selling the rallies (or both!). There's no denying that the major indices have now broken the long up-trend which lasted from 2009 to 2015. Therefore, I detect far more caution amongst investors that I talk to regularly right now.
Also, bear markets are characterised by powerful rallies of course. So just because the market breaths a sigh of relief today, doesn't mean that we're out of the woods.
That said, prices of several good quality companies on my watchlist reached levels that I couldn't resist, and I went on a shopping spree yesterday, picking up more Zytronic (LON:ZYT) and a new purchase of Tristel (LON:TSTL). In the case of Tristel, I possibly jumped the gun a bit, due to perhaps "anchoring" to the previous, higher share price.
These soft patches in the market are a good opportunity to chuck out shares that you're not happy with, but have tolerated in your portfolio due to inertia. That raises fresh money for picking up some better quality shares at advantageous prices, where panic and sentiment-driven selling by others (perhaps people on margin call?) hands you a bargain on a plate.
dotDigital (LON:DOTD)
Share price: 50p (up 5.8% today)
No. shares: 293.5m
Market cap: £146.8m
Trading update - this email marketing software company updates the market for its estimated H1 figures to 31 Dec 2015 - the company has a 30 Jun 2016 year end.
Today's update contains numerous bullish points, but it's important to remain grounded by reinforcing that the title says "in line with market expectations". So all these positives were really already baked into the price.
A few key snippets that I noted down on my pad;
- H1 revenues up 29% to £12.9m (of which SaaS is £10m)
- Avg revenue per client up 31% to £525 p.m.
- Cash of £14.8m, just over 10% of the market cap
- 0.36p dividend - why so tight, when they have plenty of cash?
- US growth good, but from low base - up 84% to $2.1m
- Magento partnership sounds significant
My opinion - this is one of my favourite companies, and I regret having sold out too early, as I thought the valuation was getting too warm. It's since risen about another 50%!
If you take off the net cash, then the fwd PER is about 20, which given the strong organic growth is actually fairly easy to justify.
Overall then, it gets a thumbs up from me, and it's certainly staying on my watchlist, with a view to buying any dip down to say the 40p level, if markets overall sell off.
Note the very good track record historically of this company;
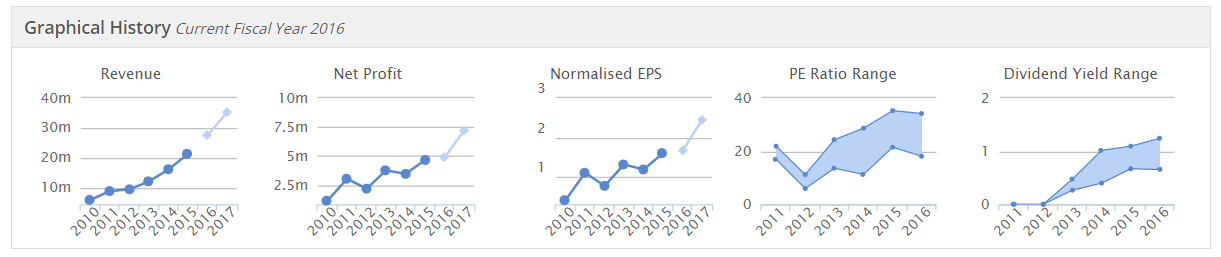
A word of caution though, when economies do go into recession, then it's marketing which is often one of the first things to be cut back, as customers hunker down to weather the storm. Therefore if the US economic wobbles at the moment do turn into a proper recession, which spreads to UK/Europe, then the strong growth at DOTD could well peter out. That, I'm afraid, would take the PER of 20 down to a significantly lower level, so you could see a double whammy of lower earnings, and a lower multiple, giving scope for this share price to perhaps halve?
That's the downside case, which I'm not saying is going to happen, but it's important to work out the downside case, and consider what risk there is of that occurring. I'm very wary of paying a PER of 20 right now, when the economic outlook is uncertain.
Remember also that company results are backward-looking, so there's no guarantee that good performance in 2015 will necessarily continue in the future. Although DOTD is expanding into new geographic territories, so it could probably keep growth going, maybe at a slower rate, through this, even if its main markets slow down.
Overall, I like it a lot, but am not sure I'd pay the current price, when the economic outlook is becoming more uncertain.
XLMedia (LON:XLM)
Share price: 67.5p (up 7.9% today)
No. shares: 200.4m
Market cap: £135.3m
Trading update - on the face of it, everything sounds great - exceeding market expectations, although note that they focus on the (largely meaningless) adjusted EBITDA as a performance measure;
The Group has continued to deliver strong growth in the second half of 2015, building on the excellent performance in the first half as well as the addition of Marmar Media acquired in July 2015. As a result the Company expects to exceed current market expectations delivering annual revenues of at least $88.6 million and adjusted EBITDA of at least $28.2 million. This strong performance represents growth of approximately 75 per cent. and 66 per cent. respectively, compared to FY 2014.
Annoyingly, this means I have to check back to the last accounts to see what actual profit was. Looking back, I see that XLM capitalises a large amount into intangible assets - in 2014 that figure was $11.5m (shown on the cashflow statement), therefore as I expected, the adjusted EBITDA figure greatly overstates real cash profits - of course it does, that's the reason companies quote adjusted EBITDA!
My opinion - having said that, the rest of the accounts look believable. The other big red flag that usually comes with high levels of capitalised intangibles is excessive debtors - and that is not present here. The balance sheet has lots of cash on it, and the company has been paying generous divis - both are important pointers that reassure about the accounts probably being genuine.
Therefore to my mind, it seems to more fit the mould of Plus500 (LON:PLUS) rather than Globo - i.e. it looks like the profit, cashflow and cash are probably real, but as is usually the case with this type of Israeli company listed on AIM, the profits may not be sustainable - that's the big question that investors need to investigate. Remember Blinkx too - similar sector - that looked too good to be true as well, and the wheels came off there when the good times suddenly halted.
We saw with PLUS that regulatory corners were being cut, and we've also seen with almost the whole ad tech sector, many of which are Israeli, that their profits were unsustainable and killed off by ad blocking software.
So far, XLM seems to have dodged those bullets, but personally I remain highly sceptical about this company. It's overseas, and AIM - which is the biggest red flag you can get - because there's nearly always something wrong with most of them.
For the time being though, things seem to be going well at XLM, with upbeat outlook comments. So maybe this company might be the exception to the usual rule of avoiding foreign companies on AIM like the plague?
The Group expects to continue with its strategy of increasing scale and diversification, while focusing on enhancing its technological edge. We will continue to invest in technology in 2016 to further develop our in-house systems and infrastructure.
The Board believes that the Group's strong growth, combined with its technological abilities, position the Company well to further develop the business. Accordingly, the Board remains confident of the Company's future prospects.
STM (LON:STM)
Share price: 53p (down 18.5% today)
No. shares: 58.9m
Market cap: £31.2m
(at the time of writing, I hold a long position in this share)
Directorate change - the CEO is leaving;
STM Group Plc (AIM: STM), the multi-jurisdictional financial services group, announces that Colin Porter, CEO of STM, yesterday tendered his resignation to pursue an opportunity in a non-competing industry in the United States. Colin will serve his 12 month notice period to ensure an orderly hand over and will work closely with the Board to support the transitionary period. Alan Kentish, Director of Product & Business Development and formerly Chief Financial Officer at flotation of the business in 2007 and executive director since then, will assume the role of Interim Chief Executive Officer as of 1 April 2016.
A CEO leaving usually rattles investors, which has probably contributed to today's sharp share price fall. I'll eat my hat if the outgoing CEO actually does serve the full 12 month notice period - companies always say that they will, but in practice they hardly ever do - it's just a fig leaf to justify the 12-month notice period payout that is standard practice these days. In my view, 12 month notice periods in Directors' employment contracts is just one of the many scandalous ways in which Directors rip off shareholders in corporate UK. The norm should be 3 months, not 12 months.
Trading update - this doesn't sound too bad - only slightly below expectations (aka. "broadly in line"!), and it's good that the company gives a specific figure for profit too, of £2.7m, a good increase on last year;
The Board announces that the Group has traded broadly in line with market expectations for 2015 of profit before tax of £2.7m (2014 actual: £1.7m). STM continues to invest in its business development infrastructure and product development capabilities, the benefits of which will be further seen in 2016.
My opinion - Edward Roskill made a good case for the bulls in this share in one of my audiocasts a while ago. Personally I wasn't convinced, so didn't buy any. There are certain aspects of this business that I'm not keen on - namely that nearly all its new business comes from one particular introducer, called De Vere.
Also, the business seems to have little historic profitability, but has hit upon a new and apparently lucrative source of profits, from QROPS (a particular type of overseas pensions). This gives too much concentration risk in my eyes, of one profitable product, and one main sales source.
Having said all that, the bull case is also interesting, in that the company is building a very sticky stream of recurring, profitable revenues. If that continues, with nothing going wrong, then the shares could go up, possibly?
On balance, it's a business that I don't particularly like, but the sharp fall today means that it's starting to look interesting, so I've picked up a tiny scrap of shares this morning, as a small punt, and to motivate me to do more thorough research on the company, although it will never become a significant holding in my portfolio.
There are no divis either, which I'm not thrilled about.
Fairpoint (LON:FRP)
Share price: 145p (up 4.7% today)
No. shares: 45.6m
Market cap: £66.1m
(at the time of writing, I hold a long position in this share)
Trading update - the company has used a weird system for making this announcement, resulting in their being no line spacing, so it's practically illegible. So I've had to copy/paste the text into Word, and add some spaces, to make it readable.
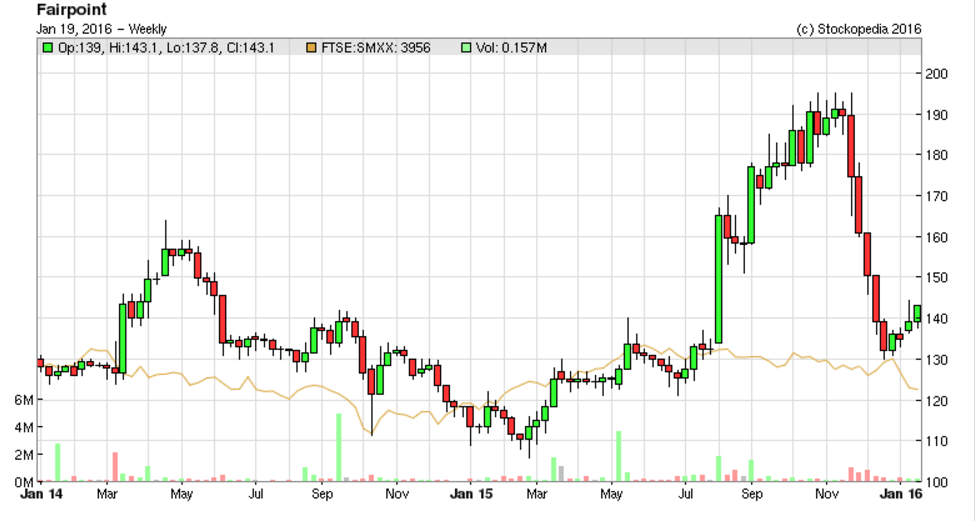
The upshot is quite encouraging, given that the background has been a big sell-off in the shares, on worries about changing Govt rules over compensation claims (especially whiplash);
Overall, the Group's adjusted* results are expected to show double digit growth against the previous year and are in line with market expectations.
The adjustments to profit look reasonable, being amortisation of goodwill, exceptionals, and changes in deferred consideration.
Valuation - broker consensus is 18.5p EPS for 2015, thus valuing the company at a PER of 7.8, which obviously looks very good value.
The reason it's cheap, is because of sniffiness about the group's activities, and also worries over future earnings falling, due to both the IVA and PPI activities declining, plus the more recent acquisitions of legal services possibly also seeing declines in profitability.
On this point, it's interesting that Fairpoint repeats that it reckons the changes might be advantageous for them;
We believe our platform provides us with a structural competitive advantage which suits forthcoming market changes. Overall, we are confident of our positioning and our growth prospects.'
Net debt - looks under control to me, so not a concern;
Group net debt as at 31 December 2015 was £13.6m (31 December 2014: £7.6m). This largely reflects the acquisition activity undertaken by the Group within its Legal Services business during the year and is comfortably within the Group's committed bank facilities of £25m.
Whiplash claims - more reassurance is given today, which is a good thing, because the last trading update dodged this issue.
This category of business, on a pro-forma basis, represented approximately 8% of the Group's revenues in 2015. As noted previously, the Group believes that its recently acquired Legal Processing Centre positions the Group advantageously to manage such legal work at low cost.
It may only be 8% of revenues, but if it's high margin work, then could be a much bigger percentage of profits - so again, the issue has been only partially addressed, but at least we're inching towards better understanding what is likely to happen in future.
My opinion - I'm not a fan of this type of business, and the sector has a propensity to deliver unwelcome surprises. However, Fairpoint looks well managed, and two thirds of its business is now legal services, with a focus on streamlining, and reducing the cost to consumers of seeking legal redress.
At a lowly multiple of earnings, the big question is to what extent earnings will be resilient in future?
Divis are good here, about 5% yield, and the StockRank is strong, at 97. So it's worth considering I would say. Personally I'm happy to run with my smallish position in it, but probably won't be adding any more for now.
I ran out of time earlier, so here are some quick comments on other companies reporting today:
Judges Scientific (LON:JDG) - shares are up 6.1% to 1445p today. The company puts out a trading update for calendar 2015. This sounds good;
As reported at the half year the Group experienced a difficult first quarter, with order intake recovering to a satisfactory level in the second quarter. This improvement in order intake across the Group was sustained throughout H2 2015. Consequently the Board anticipates that the final results will show a return to organic sales growth with trading comfortably in line with market expectations.
The year 2016 has started with a solid order book at 11.9 weeks (organic: 11.4 weeks against 9.9 weeks at the start of 2015) and a more encouraging outlook on exchange rates.
Broker consensus is for 100.8p EPS for 2015. Presumably "comfortably in line with" means slightly above? So it looks like the 2015 PER is about 14, and with a positive-sounding outlook, I can see why this share rose nicely today.
Overall, I think it looks priced about right for the time being.
Johnston Press (LON:JPR) - underlying EBITDA and net debt are said to be in line with expectations.
Total revenues fell 7% year-on-year. Circulation revenues are also down 7%.
I remain of my long-standing view that the equity here is probably worth zero. This is because, by my calculations, the remaining cashflows from this dying sector probably won't be enough to repay the debt, and service the pension fund.
It's a value trap in my view. That said, there can be lucrative dead cat bounces on the way down with dying companies, and with the equity just a stub now, greatly out-weighed by net debt, and the pension deficit, then it's perhaps an interesting share to punt for the gamblers out there!
Quantum Pharma (LON:QP.) - bad luck to the people who were bottom-fishing here, based on an apparently low PER. There's a profit warning today, but it's only a mild one for the year ending 31 Jan 2016 - adjusted EBITDA (since when did this become the main performance measure?!) is expected to be c.£12.7m, versus market consensus of £13.4m. Quite a small miss, given the extent of share price drop recently.
However, there's more bad news - delays on product launches, of about 12 months;
By the end of the current financial year to 31 January 2016, the Board expects that five regulated products in the Niche Pharmaceutical division will have been launched rather than the ten products anticipated at the half year results in October 2015. The other five regulated products are now due to be launched during FY 2017.
Various other details are given. I don't have an opinion on this share, it's a new one to me. I'll review the accounts when they are published on 10 May 2016.
MySale (LON:MYSL) - (at the time of writing, I hold a long position in this share) - quite an encouraging update - the company reports a significant turnaround, from heavy losses in H1 LY, to EBITDA positive (here we go again!) of A$1.5m in H1. A 250bps improvement in gross margin is good news.
It has plenty of cash too - A$30m, or A$51.1m underlying cash (what is the difference?! Surely cash is cash?)
My opinion - I like this share (obviously, as I hold some personally). I'm in it for the turnaround, which seems to be happening. So all looks good to me. Management are experienced in the sector (crucial), and Philip Green is a major shareholder, and pre-IPO backer - so it's probably going to work.
SCS (LON:SCS) - this one has taken me completely by surprise - a very good trading update;
Trading over the key Christmas and January sales period remained strong within both ScS and House of Fraser, resulting in total like-for-like order intake for the 25 weeks ended 16 January 2016 up 8.8%. This is a pleasing result against tough comparatives in the previous year.
As a result the Group expects to report profits significantly ahead of current market expectations for the year 2015/2016.
This has been reflected in a 16.7% rise in share price to 178p today.
All done for today, see you in the morning!
Regards, Paul.
(of the companies mentioned today, I have long positions in: ZYT, TSTL, STM, FRP, and MYSL. I hold no short positions in companies mentioned.
These reports are my personal opinions only, which will sometimes turn out to be wrong, and sometimes right. My opinions are subject to change without notice.
Please always do your own research, as we do not give recommendations on this site)
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

25 comments
Excellent set of half year results just posted by Tristel (LON:TSTL) this morning. Strong earnings and profit metrics across the board, especially in export markets and increase in interim dividend of 95%.
http://www.investegate.co.uk/tristel-plc--tstl-/rns/half-yearly-report/201602240700119349P/
Possibly much of this is already in the price which is well up since Paul's comment in mid Jan but pretty pleasing nevertheless.
Gus.
Interesting to observe that while all my other holdings were crashing by an average of 3.5%, FRP was the only one actually going up. What can we gather from that, either about the market in general or FRP in particular?
Re STM (LON:STM) is the fall now down to the terrible market conditions or the fact that the EPS will probably be around 3 pence? Interestingly they will be taxed this year so the EPS figure could be a bit lower, Sitting on the sidelines for now, but looking to reenter if it goes much lower.
Paul
I enjoyed the Edward Roskill interview and STM was the buy I took away A little out of pocket now but as Edward said the earnings accumulate nicely year after year because the business is sticky Over time the eps will make it look real value again I understand your concern re De Veres and the QROPs issue but financial salesmen will sell what they can so as long as there is an underlying demand I would have thought DV are a good broker to be with That said when the value of the investments fall though I believe takings fall as well Funnily enough this is like Record a company i recently bought because they just look cheap to me and I would appreciate any comments on that!! (Yes exclamation marks do work)
Sorry to all re punctuation my Apple Macbook seems to have lost the urge to print full stops and commas Its reaction to recent market moves
Guy
Re STM (I hold a long position) It's a pity STM were not forthcoming with more detailed financial information in today's RNS. On the face of it, an increase in profit before tax at nearly 60% is a worthy result and deserved some amplification.
Looking back at their interim results to 30 June, I see revenue up 12%, profit before tax up 40% and cash up 29%.
A 17% cut in their share price today just doesn't seem justified.
Fairpoint (LON:FRP) seem to be saying, with references to govt statements, that legal representation is still allowed for these 'low cost' claims. I suspect their 'competitive advantages' of which they refer means that they still see this as a profitable part of the business because of their operating efficiencies, implying that other legal firms may struggle in this area. It also will not affect the business for a further 2.5 years.
So overall, I see this subject as a bit of a storm in a tea cup.
The other fair point I like to emphasise about Fairpoint (I hold a long position) is that there is a case for considering it as a growth share. It is on a cheap fwd P/E but this isn't a company that is moving sideways (like Laura Ashley or ShoeZone in my opinion), it seems to have found a unique business model in consumer legal services - i.e. actually detailing to consumers what prices are up front!! I therefore think there is good room for growth of the business. This might be partly offset by its currently declining debt management business but even on that side it's only a matter of time now before interest rates go up a bit and put pressure on family incomes.
Tristel (LON:TSTL) is another one that I sold too soon. When will I learn?
Re STM (LON:STM) why is the fall overdone? Brokers forecasts for this year were EPS of 4 pence. Last year profit before tax was £1.7 million and a EPS of 1.97 pence. So extrapolate that from £2.7 profit before tax this year and we get about 3.1 EPS this year. That puts it on a rather warm P/E ratio of 17! I remember the podcast with Edward Roskill and he was talking more along the lines of 6 pence EPS so that is quite a bit out. If they hit 6 pence EPS, then it is a bargin. But I can't see why the fall is overdone. I sold out. Feel free to correct if you think I'm mistaken.
Hi thekingsgambit,
Re. STM (LON:STM) I am working from consensus EPS forecasts shown on Stocko of 3.8p for 2015, and 5.0p for 2016. So if they're only slightly below the 2015 figure, then the valuation looks reasonable to me.
Regards, Paul.
LSIC seconded. Supposedly forecast eps around 28c so p/e is 10 ish?
Hi Paul,
If you have time I'd be interested in your views on LSIC who had a TU today. Looks v cheap to me (I hold) so hope I am not missing something.
Deucetoace
Isn't LSIC de-listing and going to the US? I read the interims but didn't see it mentioned though.
A strategic review was announced in September & that was one possible option. It hasn't reported yet so who knows. Mind you if it happens could that trigger a rerating?
If they abandon the UK quote then the share price is likely to fall until it is settled on nasdaq as there will be shareholders who don't want to own shares in a solely US listed entity.
It may be as you suggest. If so I can wait. I don't see it as a significant downside. Indeed it is possible to argue that it would be a buying opportunity where it to fall so is in the longer term a positive.
Perspective is all :)
It's only one possibility of course. Maybe the review will come up with nothing new.
XLM do have some nice photos of their board and management on their website.At least they're not being shy !
Paul, Do the large directors selling at dotDigital (LON:DOTD) not concern you?
Yes have been watching STM (LON:STM) for a buying opportunity, the update does not sound that promising, broadly inline, after Edward Roskill's comments I was expecting a bit more, wide spread also and difficult to trade.
Fairpoint (LON:FRP) update today, at last some figures re whiplash claims about 8% of revenue. Must say the format of the statement could have been better.
Re Tristel (LON:TSTL) very surprised how much that dropped, I can't see why China problems would affect them, did not top up but should have done.
I own some STM (LON:STM) too and agree the fall seem overdone, but in this market anything even slightly negative is getting hammered.
Hi Paul -
Re. STM (LON:STM) I recall that this stock was a particular favourite of Edward Roskill in your last podcast with him. You will be interested to note that it has dropped 15% on the day on the announcement that the CEO has resigned.
Having read the RNS carefully the parting is amicable and he is serving his 12 months notice period to ensure a smooth transition. So to me the fall looks overdone and presents a buying opportunity. I took a small stake this morning.
If the revenue is up 29% and the average revenue per client is up 31%, does that not mean the number of clients has dropped ?
I ran a screen yesterday on small caps to find out how many companies' share price had fallen by more than 15% since Jan 4th and the number astonished me. I found 78 companies between market cap £10m - £500m, with the sp dropping between -15% to -37%.
Considering that the AIM100 index has dropped 8% since Jan 4th, that suggests the standard deviation around the mean to be very wide.
Many of the shares are those you would expect to fall further than most, such as story stocks, debt laden ones and loss making ones. But there are quite a few which IMO have simply been washed away with the tide.
But I am sitting on my hands with cash in hand as I think this market has further to fall.
All IMO and please DYOR
Financial controls of the day: Unilever
http://www.investegate.co.uk/unilever-plc--ulvr-/rns/final-results-2015/201601190700062451M/
This sprawling FTSE 100 conglomerate has taken just 11 working days from its year-end to prepare its annual results.
And to think some smaller companies will take until May to issue their 2015 figures.
(PS nice to see an early SCVR!)
DOTD delivering organic growth yet again. Seems to be off PI radar, perhaps because email marketing is somehow deemed to be ordinary and boring? Yhe likes of TUNG more exciting :-)
I increased TSTL yesterday too.
CLIN poor organic growth, underperforming division with management change and the usual orders biased to next half shows that large, multiple management sales do signify an overpriced share.
Growth by acquisition.
Large director sales. Oct 15 at 685p when price was 700+ drove price down.
I look forward to your view on this company. I've put it on reduce, but might be over reacting.