Small Cap Value Report (19 Mar 2015) - FRP, RGS, TFW, CLL

Good morning! Running late again today, after the first decent night's sleep in weeks. I'm back to civilisation in Hove thank goodness, after a fortnight in North London - where everything stinks of cigarettes, dogs bark constantly, and people shouting - there always seems to be someone shouting incoherently out on the street, 24 hours a day. Ghastly. Still it's convenient for getting into the City.
Fairpoint (LON:FRP)
(at the time of writing, I hold a long position in this share)
Webinar - click this link to view the recent results webinar from Fairpoint. I haven't watched it yet, but results webinars are an excellent way for investors to get a similar experience to attending an analyst presentation in the City.
Regenersis (LON:RGS)
In a similar vein, Equity Development are doing a webinar with management TODAY at 2:45pm for recent results from Regenersis. Link to participate is here. I'm always happy to provide links to information & events that will be useful to investors, for proper companies (not speculative junior resources sector stuff though), whoever is running them.
FW Thorpe (LON:TFW)
Share price: 150p
No. shares: 115.7m
Market Cap: £173.6m
Interim results - for the six months to 31 Dec 2014 are published today.
This is a conservatively-run family business, which also has a listing. This is emphasised by the touching tribute to one of the co-founders in today's report;
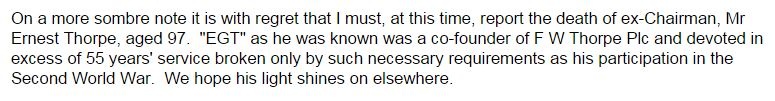
The figures are absolutely clean - there are no adjustments, or invented accounting definitions such as HOPS or adjusted EBITDA. Just straightforward EPS of 3.92p for continuing operations, which is up 9% against H1 last year. Note there is an H2 seasonal bias to trading, so it looks as if the full year (ending 30 Jun 2015) might come in around 9p to 9.5p. I can't find any broker forecasts on the company. You get the feeling this company would probably regard broker research as a waste of time & money!
An under-performing subsidiary called Sugg Lighting was disposed of on 6 Feb 2015, so that is positive, in getting its losses out of the group accounts.
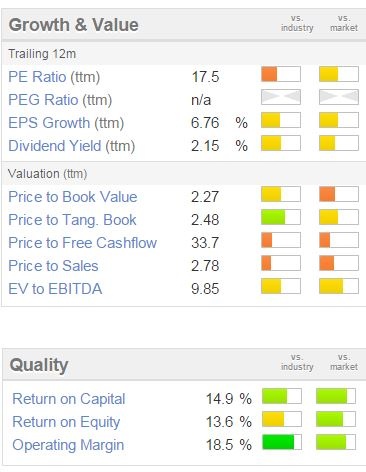
I like the strong operating profit margin at this company, which stood at 16.9% in these interim accounts, slightly down on the 17.2% achieved in H1 of last year, but still a very respectable number that demonstrates the products must be good quality, and in demand.
Dividends - the interim divi is up 5% to 1.1p, and continues the perplexing policy of paying out small dividends, when they have scope to pay out far more, given the strong finances. The full year divi looks to be heading for about 3.4p, a yield of 2.3%, although it is comforting to know that the company has the capacity to pay a lot more. So you'll get the divi, even in a bad year, in future, I would guess - there are probably quite a few elderly Aunts in the Thorpe family that rely on the divis!
Balance sheet - always a joy to behold! Net assets are £77.3m, of which £6.7m are intangible, so that's an NTAV of £70.6m. The current ratio is spectacularly good, at 5.61! This includes £33.9m in cash & on deposit. I wonder what they will eventually do with all the surplus cash? There's plenty of scope for a big special dividend, or a sizeable acquisition, so sooner or later they might create some value with all that cash.
My opinion - nearly all the profit comes from the main subsidiary, Thorlux. So the main risk is that competitors start to eat their lunch, and force them to lower prices & hence profit margins. At the current valuation, and given pedestrian growth rates in recent years, I would say these shares look priced about right. Even allowing for the cash pile, I wouldn't be chasing this valuation any higher personally. Smashing company though!
On the upside, I suppose the things to look out for, would be new product launches. Plus acquisitions - if a really strong acquisition was announced, using cash, then that would enhance earnings considerably, and could make the shares look a bargain. Sitting on a pile of cash, doing nothing with it, isn't a great strategy in my view.
Cello (LON:CLL)
Share price: 89p
No. shares: 84.9m
Market Cap: £75.6m
Final results - for calendar 2014 are out today. This is a marketing group, which has a particular focus on pharmaceuticals (that division makes most of the profits).
The headlines look reasonably good - turnover up 6.4% to £169.9m, and adjusted profit before tax is up 9.9% to £9.4m. My reservation here is that there are a lot of adjustments to profit, and note how some of them are not one-offs, but happened in both 2014 and 2013. Note also the scale of the adjustments, which materially improve profit in both years;
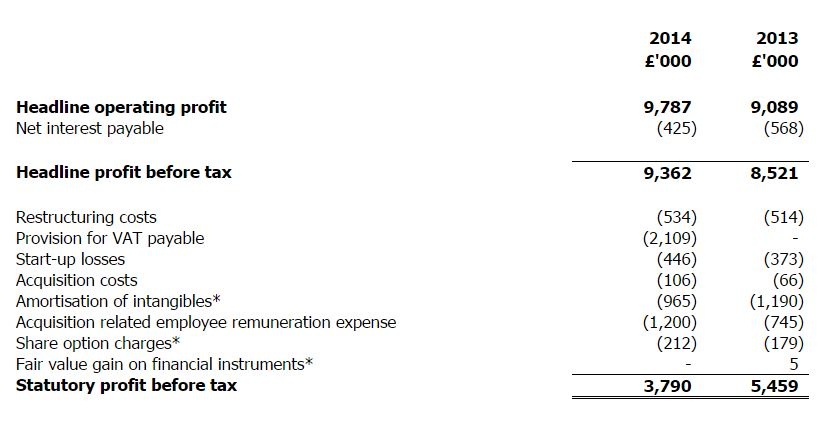
Several of those items look questionable to me. It all creates a sense of unease - am I being steered in the direction of inflated profits, and hence over-valuing the shares? I'm not sure, but it feels a bit like that.
If you do accept the adjustments, then EPS came in at 8.14p, which looks to be a bit ahead of consensus (7.8p). With the shares at 89p currently, that works out at a PER of about 11.
Dividends - the company has a good track record of steady dividend growth over the last seven years. The forward yield is reasonable, at about 3%.
Balance sheet - not great.
Once you take off the £74.9m intangible assets, NTAV drops out slightly negative, at -£5.4m.
The current ratio is 1.12, which is just about OK, given that this is a services business, and therefore does not hold any inventories.
Given the fairly weak current ratio, having another £12.4m in long term borrowings doesn't help.
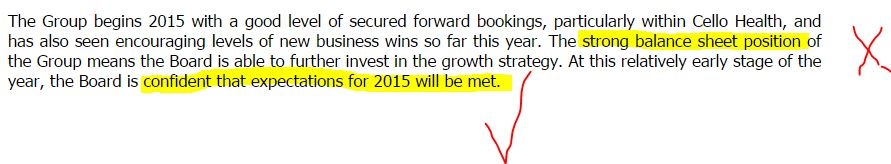
Outlook - memo to Mr Allan Rich, Non-Exec Chairman: you haven't got a strong balance sheet! However, I am taking his confidence about 2015 at face value, even if he needs a few lessons in balance sheet analysis (my rates are very reasonable!).
My opinion - it looks priced about right, on balance. This type of business generally doesn't attract a high rating, and with its weak balance sheet, and a PER of 11, I think the price is probably about right.
Gotta dash. See you in the morning!
Regards, Paul.
(of the companies mentioned today, Paul has a long position in FRP, and no short positions. A fund management company with which Paul is associated may also hold positions in companies discussed)
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

9 comments
"...the 3 most important things about small caps investing were "management, management, and management". "
Bang on. I made a resolution last year to ignore or ditch any company's shares run by dodgy or bad management. Yes, you may lose a good opportunity or two, but it will be more than made up by the losses you avoid in the process.
The Aim market has more than its fair share of charlatans and crooks in management out to make a fast buck at the expense of PI s like you and me. The best way to deal with these companies is simply to drop them in Room 101.
Best wishes, Ram
I know its a couple of days after the event, but just wondered if anyone had any thoughts on Newmark Security (NWT). The Reid family sold half their stake to institutional investors at 2.6p on Tuesday. The shares took an inital hit but have come a booming back today, up 8.5%. From the rns:
Commenting on the Placing, Marie-Claire Dwek, CEO, said: "I believe this is a positive development for the Company as it improves both the liquidity of the shares and builds upon our existing institutional shareholder base."
Definitely a stockrank favourite at 99/100, seems to tick all the boxes despite its small market cap. Looks a good one to my novice eyes but happy to stand corrected.
Thanks
James
Re Webinars and analysts attending meetings. I recently spoke with Dr Matt Bamber, who is an academic at Bristol University. He has done some research on "if no price sensitive information is given out at analyst meetings, what are they for?" - He concluded that it was all about claims of "superior knowledge" for marketing purposes, rather than getting genuine insight.
Certainly many professional fund managers market themselves as doing lots of meetings with management. It is debatable though whether they do get any valuable insight. I don't think that there is much evidence that meeting management leads to outperformance and makes you a better investor?
If anything there is a lot of evidence to the contrary, and stockopedia's quantative screens work much better than being sucked in by charismatic management presentations?
Hi Bruce,
I totally disagree. For me, meeting management is absolutely key in working out what type of people they are, and also giving a lot of additional understanding about the business. But you have to maintain a complete sense of detachment. The moment you get to be pals with them, it's very dangerous.
A very charismatic CEO is for me, usually a bear signal - e.g. when I saw the video of John Roberts of AO World (LON:AO.) I completely "got" why the stock was so expensive, and added to my short! He is a remarkable salesman, and has obviously sucked a lot of people into his story. When you stop and think carefully about the business, it's just a low margin box-shifter.
I think what you're saying is that if you go to mgt meetings and lap up everything they say uncritically, then it's a bad thing - I totally agree with that!
I could name numerous other companies where meeting management, or seeing them in a webinar, has completely put me off buying the shares.
Regards, Paul.
Also, I used to have a "one in five rule", which helped me discipline myself after company meetings. So I only allowed myself to buy shares in one company out of every five that I meet. This really helps focus the mind, and makes you hold back on marginal buy decisions, especially whilst you still feel cosy about things within a couple of days of meeting management.
PP.
Richard Rose seems to be the flower of the year, and he is behind AO World, isnt he? Just got involved with Quindell, to his profit! Just cashed a lot of shares elsewhere, as you noted recently for around £10m. Also, the chairman behind Crawshaws, sparkler of the year in 2014, or was it 2013. I was certainly impressed with him at Mello last November in Derby. His encouragement for management to think much further ahead - say what can be achieved in 10 years rather than next year I found stimulating. Maybe he was taken in by the Roberts story - also heard at Mello last November - though he doesnt seem to me to be the sort to be taken in very easily. Seemed to do a pretty good job at Booker and Whittards, though maybe in the right place at the right time?
Hi Bruce,
One other thought struck me. How successful is Dr Bamber (of Bristol University) as an investor? Academic studies are all well and good, but they don't necessarily make you a good investor (and they are very rarely written by a good investor!)
I keep a very close eye on about 50 people that I have met over the years, who are incredibly successful private investors, mostly in the small caps space. These are guys who year in, year out, out-perform the market.
If I had to pick on one single, common attribute about them, it's that at least 90% of them like to meet management. At a recent master class, run by ShareSoc, David Stredder said the 3 most important things about small caps investing were "management, management, and management".
Lord Lee made a similar point at the same event - he likes to invest long term in businesses where management are custodians, often of family firms, and he meets them and forms quite a close relationship with them.
Both Lord Lee, and David, have spectacularly good track records of picking winners. Sure they get some wrong too, as does everyone, but their hit rate is far higher than most of us. So by concentrating on management, they're obviously on to something. Or at least, they have some highly effective way of weighing up and separating good, and bad management.
So for me, it's fine to listen to what academics say, but I place far more emphasis on noting (and trying to emulate) what the most successful investors do in practice.
Finally, look at Buffett. Above all, his whole approach is all about backing the right management teams, and letting them get on with it.
Regards, Paul.
I don't know how good an investor Matt is, or if he is an investor at all.
Management is clearly an important aspect, particularly small caps. Your 1 in 5 rule sounds like a very good heuristic.
You clearly believe that you are better than average at spotting "wrong uns". Maybe you are.
But the industry as a whole can't be better than average - and fund managers and analysts spend an awful lot of time in meeting management. For a start, it is more fun to spend the time meeting management than reading the annual reports. I also know some very good fund managers who refuse to meet management - Patrick Barton for example.
How much time does Buffett spend in meetings with Chief Execs compared to sitting on his own, reading annual reports?
I suspect Matt is on to something.
Paul, now that you have emerged from your non-toxic Synety cloud (boom-tish), any thoughts on Puricore's news today?