Small Cap Value Report (19 Nov 2014) - VNET, AVON, OPTS, AGA, MYX, BLUR

Good morning! Today's report is going to have to be a bit briefer than usual, as the first version has just disappeared due to a computer malfunction, and I have to go out for a lunch meeting shortly. So will rattle through as best I can.
Pubcos
There was big news last night, when a rebellion of some MPs saw an amendment passed, against the wishes of the Govt, to allow tied pubs to buy drinks on the open market. This has put a massive spanner in the works for pubcos such as Punch Taverns (LON:PUB), Enterprise Inns (LON:ETI), and others. Will the takeover of Spirit Pub (LON:SPRT) still go ahead I wonder?
If this measure is not reversed, then it could kill off the tied pub, and would be disastrous for pubcos profits. So this sector could still be a good area to think about putting on some short positions perhaps?
Vianet (LON:VNET) shares have also dropped in sympathy, as their main profit earner is the beer flow monitoring equipment used by pubcos to monitor that only expensive beer bought from them is being served, and not cheaper beer from the open market.
Avon Rubber (LON:AVON)
Results for the year ended 30 Sep 2014 are out today, and look good on a brief skim.
Company results seem to be getting more & more complicated, with companies seemingly inventing their own definition of profit to give the most flattering result possible. Check out this complicated table;
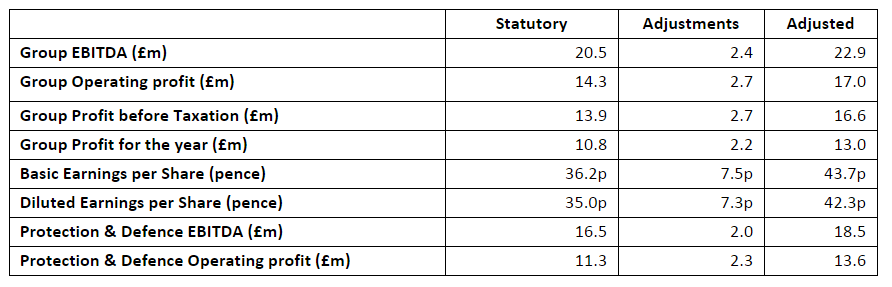
Broker forecast seems to be 40.3p, so using the 43.7p adjusted EPS figure above, the company seems to have beaten expectations.
The company has also moved into a net cash position, of £2.9m, which is good.
There is a pension deficit, but the overpayments are less than 10% of profit, hence it's not material in my view.
Outlook sounds positive;
Our strategy has significantly improved the shape of the Group, reduced the risk profile and improved margins. This is providing continued growth and the outlook for the future remains positive.
Dividends - at under a 1% yield, the divis are very small, and over 7 times covered, which strikes me as being unnecessarily cautious. Shareholders should be reminding management who owns the company, and demanding a greater slice of the cake, in my opinion!
My opinion - I've missed the boat on this one, and don't know enough about the business to determine whether higher profit is sustainable or not. If you think the profit growth is set to continue, then the shares might be worth a look?
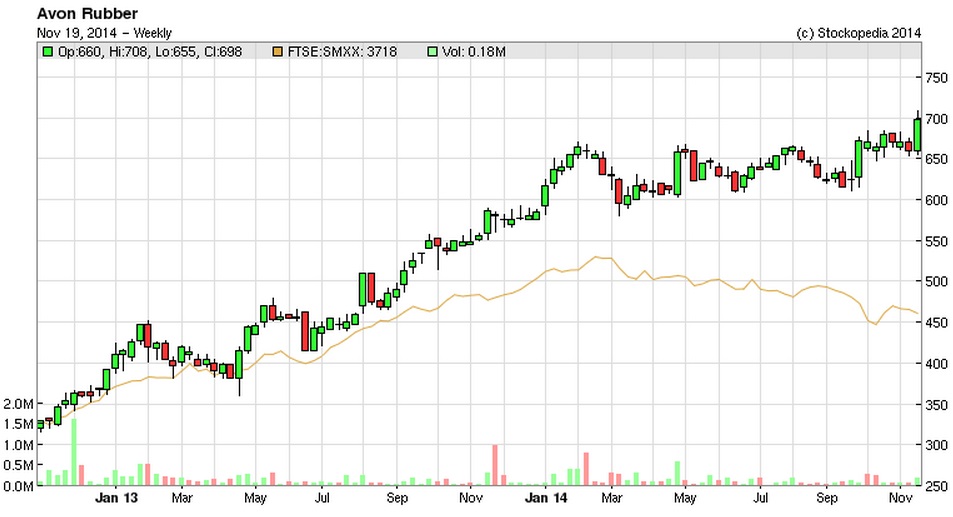
I imagine broker forecasts will be increased, so if maybe 50p EPS is achieved this year, then the shares being priced around 700p currently would put it on a PER of 14 - which doesn't look expensive, if that profit growth is sustainable. So worth a deeper look perhaps?
Optos (LON:OPTS)
Results today from this retinal imaging company look impressive.
The outlook comments also seem upbeat;
We expect to see continued new customer growth similar to FY14, delivering low single digit revenue growth in FY15. This would have been higher if not adjusted for the early corporate account renewal in FY14. Gross margin for the full year, on the basis of the anticipated mix of capital sales and rentals, is expected to improve to around 60%, exiting the year at a higher rate as we benefit from the new products. In future years, we anticipate further incremental improvements in gross and operating margins as we benefit from the new product platforms, as well as continued customer growth and continued renewal opportunities. As with previous years, revenue is to be heavily weighted to the second-half of the year with a consequential impact on profit and cash.
With strong sales of Daytona, our new products progressing well, the increasing body of clinical evidence and a broadened geographical reach, the Board is confident that Optos is well placed to drive customer growth, continued improvements in profitability and sustainable cash generation in FY15.
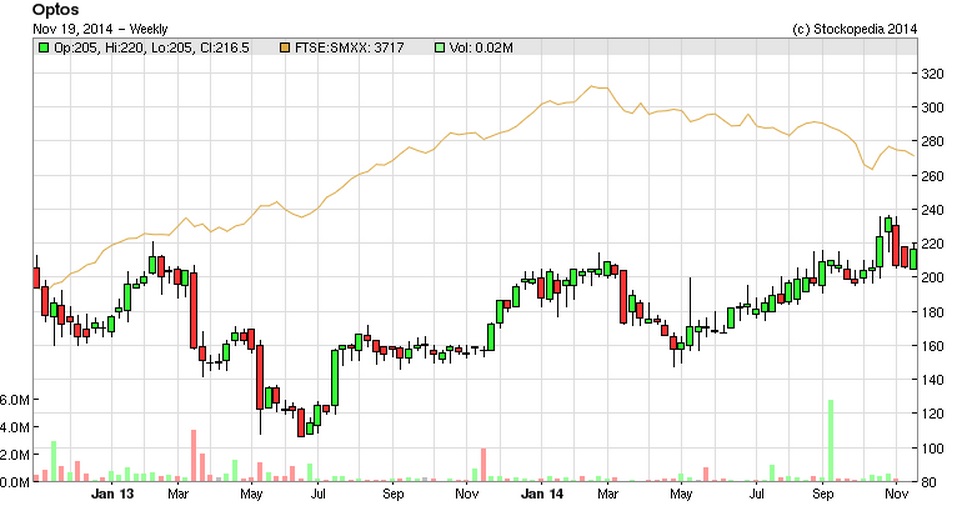
Adjusted profit before tax has doubled to $18.5m (note this company reports in dollars), which is impressive.
Stockopedia shows the forward PER to be about 15, which seems reasonable.
So this one gets another cautious thumbs up from me - looks worthy of doing some more detailed research at least.
AGA Rangemaster (LON:AGA)
Trading update - saying that the company is doing well in the UK, but less well in Europe.
The company doesn't seem to mention anything about profits, so a bit pointless putting out a trading statement without saying how profits are going! I am assuming therefore that there will be no change to market expectations.
I consider this share uninvestable, as the pension deficit & associated overpayments are extremely large, and are likely to consume any cash the business generates for the foreseeable future. Arguably that makes the equity worth little to nothing, since only token divis seem likely.
MyCelx Technologies (LON:MYX)
A fairly grim announcement today, flagging a potential revenue miss, and worse still a need for more cash;
The Company believes project award notifications in regard to three projects are forthcoming in the near term. The total value of these projects exceeds $20 million. However, the award process is specific to each customer and project resulting in unpredictable timing. Should no revenue from these three projects be recognised in the 2014 financial year, the Company would expect the revenue to be no less than $16 million.
The Company remains confident about future prospects in spite of short-term forecasting challenges. Given these prospects, the increased project sizes and the working capital requirements that flow from these, the Company is exploring possible funding options to finance continued future growth.
I'm surprised the shares haven't dropped a lot more actually, they're currently showing a fall of 7%.
Blur (LON:BLUR)
Trading update - which is rather confusingly worded. It starts off sounding positive, then goes on to say that large projects are delayed.
The company says it has $20m cash, and indicates that breakeven is within sight;
...all indicators that EBITDA breakeven will be achieved in Q4 2015 along with positive cash flow from Q1 2016.
I remain sceptical about this company's ability to reach profitability, but who knows? At least it has enough cash to fund losses for the time being.
Shares have lurched down 16% to 61p. The story feels stale to me.
I have to leave it there for today. See you tomorrow!
Regards, Paul.
(of the companies mentioned today, Paul has no long or short positions.
A fund management company with which Paul is associated may hold positions in companies mentioned)
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

12 comments
ship that's fine but i'm interested in the knowledge, yes it's complicated but that shouldn't deter us as investors from trying to understand the numbers imv. So i gladly accept someone with an accounting background explaining the principles of OPTS lease revenue etc.
Agreed - but not much chance if the management plods along at its current pedestrian pace.
Paul
Your views on Dialight and Carclo would be appreciated. Meanwhile thanks for your column
Paul,
Thank you for your above report on Avon Rubber (LON:AVON). I just had a good look at the new company report, and the Stockreport too, and concluded that they are likely to keep growing. I concluded they are doing well, and have the following economic moats in place:
Expertise. Brands. Intellectual property. Military approval processes.
I also note that they are not associated with Avon Tyres.
I just bought some Avon shares.
Thanks,
Paul.
On vnet i really cant see that this issue is their fault, they are anyway using their technology on petrol and vending machines and am not sure that the pub trade was reslly doing what they wanted it to do, but of course it may affect cashflow and profits in the near term, but on a longer term view I always got the impression that they wanted not to rely on pubs so much so maybe this will just accelerate that process. Have to say its a bizarre decision as many pubs have entered into long term leases and are probably now in the dark stuff although it should have little effect on pubcos like marstons whose share price has held up well. Clearly rents will now rise dramatically and there will be an option for the likes of green king to make big gains in revenue, could bring beer prices down, but to be fair to the pubcos there should be a long notice period, i am not a great fan of goverments getting involved with business but no doubt those that paid the best lobbyists won the day. As for vnet it may be an opportunity to buy lots more just need to get a handle on what this could do to their biz plan and the potential affect on dividends.
With Vianet the investment case seems to me whether the core traditional UK business buys time to allow them to successfully diversify. No position
Paul, do you still follow Dialight? Do you have a recommendation on it at the moment?
Paul when you have time, if possible, would you mind explaining the OPTS finance lease receivables and how they are accounted for in the P&L, Balance sheet and cashflow statement.
I've considered investing a few times but haven't due to a lack of knowledge of how the leasing system financials operate. It doesn't look very cash generative.
thanks
Woody
Woodcutter
I looked at OPTS a couple of years ago, and back then it was transitioning from selling the machines outright to leasing them. I can remember spending considerable time trying to understand whether the reported lease income was something that I could rely on and understand.
I gave up and decided why bother risking the disconnect between cash flow and profits.
If you're saying that it now doesn't look very cash generative then that's probably all the knowledge you need to apply here.
If it's too complex - you don't have to understand it, you can just walk away.
Must be honest and say that Vianet (LON:VNET) has been something of a serial disappointment for me. Each time I buy some it seems that within a few weeks or so something is announced that knocks the price.
I do like the company, it pays a good yield and is on a P/E of about 6, so it's cheap in that respect, but I'm starting to think it's probably cheap for a reason. Perhaps it is just accident prone.
Or perhaps I am just a bit crap at timing my purchases (more likely).
Oh well, will hold for the time being ahead of the interims in a couple of weeks.
Steve
to be fair to vianet, it seems to me that a fair proportion of it's problems are caused by external issues, such as this. This is a very tricky situation, I can understand the backlash against stories of brewerys overcharging, pubs closing and landlords being unable to make a profit.
However, how would this work ? presumably the idea is they would be allowed to buy in cheap beer and then that would force the breweries to lower prices of their beers ? surely they will just make up the difference by putting up rents ? Perhaps that's a better way overall anyway ?
Its pretty tough if your main business is selling systems to monitor beer sales, you've just had the market stalled for 12 months while the government investigated whether to ban your main product, having got past that, now mp's pass another measure that would effectively make your systems pointless. Goodness me the companies or shareholders must have done bad things in a past life !
Like you I'm just wondering if perhaps this product which only exists for the breweries to monitor tenants, has any future at all one way or the other.
K
PUB and ETI are still loaded down with private equity debt so this vote may well precipitate the restructurings needed to get these two companies on to a sound long-term footing. The vote is perhaps a reaction to companies like these having pushed the "tied house" model just too far, particularly as regards the prices of drinks supplied to the tied pubs. It's a reaction to the greed of the pubcos and the private equity companies.