Small Cap Value Report (19 Nov 2015) - PLND

Good morning!
Poundland (LON:PLND)
Share price: 224p
No. shares: 268.7m
Market cap: £601.9m
Interim results to 27 Sep 2015 - It's not a small cap, but there are some interesting nuggets in these interim results. Its shares are down 19.5% to 224p at the time of writing, giving a market cap of £603m. Do remember that, in common with most financial websites, Stockopedia data is updated overnight, not in real time. So the market cap of £748.6m shown for Poundland is as of last night's close. Clearly it's essential to manually adjust that figure, so I just took off 19.5% to arrive at the current market cap of £602m. It's sobering to think that £146m of shareholder value just vanished on publication of interim results.
Poundland joins the long list of recent IPOs (Mar 2014 in this case) where shareholders have been disappointed. Furthermore, a Placing at 280p was done less than 2 months ago, to finance the acquisition of 99p Stores Ltd - which looks to have been a cracking deal, based on the figures given in today's announcement - a 3-4 year payback is not to be sniffed at.
Although the Institutions who backed the Placing must be livid, at a profit warning following so soon after, leaving them 20% underwater from the Placing price.
J P Morgan Cazenove, and Shore Capital were the bookrunner and co-lead manager.
LFL sales fell by 2.8% in the 6 months to 27 Sep 2015. That's no good, because retailers are seeing cost pressures - so they have to drive sales & margins up, just to stand still. In particular, the Living Wage is going to be a serious problem for many companies in retail, hospitality, healthcare, etc, as not only will the minimum wage for over 21s rise from £7.20 ph to £9.00 ph by 2020, people above this level will be seeking to maintain differentials. Thus a domino effect of rising wages is likely - bad for profits, but good for aggregate demand in the economy (although much is being offset by the Govt reducing so-called Tax Credits).
The company refers to "highly volatile trading conditions so far in the 3rd quarter", and that the 6-weeks leading up to Christmas are a very important busy period, as with many/most retailers.
Note the mitigation comments here, which have read-across to other low wage employers. Thinking about how, and to what extent, employers will be able to improve productivity is a key investing theme over the next few years.
The National Living Wage
New National Living Wage ('NLW') legislation requires employers to pay £9.00 per hour by 2020 with the first stage increase effective April 2016, when it rises to £7.20 per hour. Naturally, this impacts on our cost base.
Although Poundland is not a minimum wage employer, we need to maintain pay differentials when new rates are introduced. Without mitigation, the increase in wages attributable to the new NLW is estimated at £4.3 million in the 2017 financial year.
We are mitigating this additional cost. We have accelerated investment in the current year in productivity including the trial of hybrid self-scanning checkouts, new sales based ordering systems, shelf ready packaging, the installation of LED lighting and other operational measures. We will spend an additional £2.0 million this year in these areas, as we seek to fully mitigate the additional costs of the NLW.
To put the above into context, Poundland made a £44.4m underlying operating profit last year, so £4.3m of additional costs (before mitigation) in 2017 is not going to break the bank. Although there will be further, significant additional costs in each subsequent year. So the impact could get quite nasty by 2020.
It's certainly worth thinking about not only the companies that will suffer additional costs from NLW, but also which companies will benefit from supplying the equipment needed to raise productivity, and lower costs.
All in all, a key area to get our collective heads around. There's also the cost of the Govt's newish pension scheme too, to further increase wages cost. I'll certainly be treading carefully when weighing up new positions in companies with a lot of low paid employees.
Johnston Press (LON:JPR)
Share price: 47.4p (down 10.6% today)
No. shares: 105.9m
Market cap: £50.2m
Trading update - covering the 17 weeks to 31 Oct 2015. The key part says;
The Board expects underlying profit and net debt for the full year to be in line with expectations. We have retained our focus on cost savings, delivering strong cashflows and debt reduction.
Underlying total revenues for the 17 week period to 31 October fell 8.8% year on year, having fallen 7.6% in the second quarter.
Underlying digital revenues were up 8.4%, whilst Publishing revenues fell 10.8%, with print advertising revenues down 14.7%.
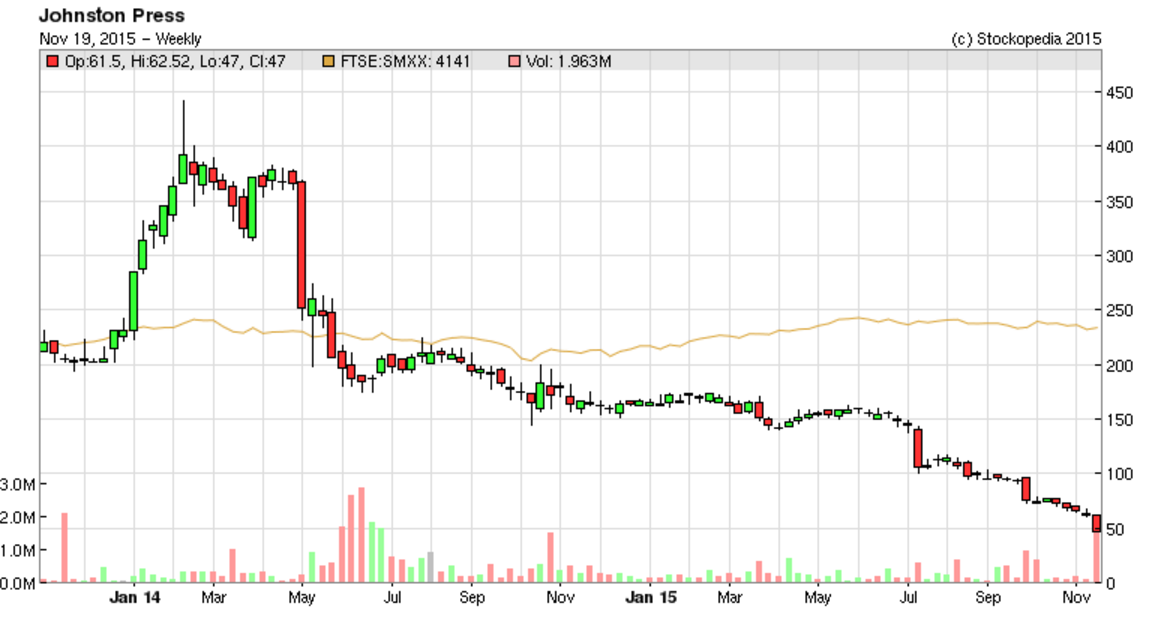
My opinion - I'm kicking myself for not having shorted this share, as I've been saying consistently, for several years here, that the equity was probably worth nothing. The reason is that the company still has a large burden of debt, plus a pension deficit, and just servicing these debts is consuming so much cashflow, that there is unlikely to be enough to fully cover liabilities. Especially given that the core newspaper business is dying.
Therefore management are really just managing the decline, and clutching at straws (the way I see it) for digital initiatives. The 14.7% decline in print advertising, which I have bolded above, is a key number to me. In my opinion, this shows that we're probably now getting into the end game, where even local advertising moves online.
Small businesses I talk to, have mostly worked out that business improves for them, the more they spend on Google ad words. The next big area is engaging with customers on Facebook & Twitter. Whether there is much ad revenue left for local papers, who knows? It's clearly in steep decline, and the newspapers are now in a vicious circle, where the more they cut costs, the worse the product becomes, giving customers less reason to buy it. Customers are literally dying out - how many people under 40 buy a local paper these days?
I suspect JPR could be quite near a tipping point where revenues just go into freefall, costs can't be cut any further, and it's game over. Note how the previously key categories of ad revenues, - employment and property, fell by 22.4% and 20.8% respectively. That's a structural move of ad revenues away from newspapers, and it won't be coming back. It's gone online - to Rightmove, Zoopla, and Onthemarket.com .
The most recent balance sheet is a car crash - NTAV is £313.3m negative! So actually thinking about it, the shares might well still be a good short? Although shorting is dangerous, as you can get caught out with a sudden spike in price, or someone may come along and bid for it. With so much debt though, and a now rapidly declining core business, I very much doubt it.
The bondholders will end up calling the shots here I reckon, unless management can get another equity fundraising away. So it remains a complete bargepole stock for me, indeed it's been on my Bargepole List since Aug 2014, and is down 77% since then. It amazes me how long it takes sometimes for really very obvious bargepole stocks to unravel.
Note that the StockRank is rather low, at 44. It's only that high because the Value score is very high at 97 - although of course this stock is a value trap, as it's technically insolvent, doesn't pay divis, etc, so the PER is meaningless.
I keep telling Ed that the Value ranking needs to be changed, to take into account the balance sheet, as it's utterly bonkers in my view to have a stock which is technically insolvent (and very likely to become actually insolvent in the not too distant future) scoring 97 on a Value ranking system. Value is all about balance sheet strength - that's absolutely core to value investing - that box has to be ticked before you can move on to consider low PER, divi yield, etc. Or alternatively, you can just manually screen out weak balance sheets, as I do - after all, it's quick and easy to do.
Just to stress, in all other respects, I absolutely love the StockRank system, but this balance sheet issue is very important to think about, as otherwise you can end up being sucked into value traps. Although that's my job really, so I'll warn you of the risks whenever I find a company that is high risk.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

25 comments
I have to make another interjection here:
We bang on endlessly about stocks with precisely Johnston Press's kind of Ranking profile. Just last week Ben wrote an extensive article on the subject "Value Traps - how to avoid stocks that might never recover".
The key to interpreting the StockRanks is to understand the Taxonomy I've set out. A high Value Rank, low Quality Rank and low Momentum Rank is the Value Trap profile. One should never buy a stock just because it's cheap - it always needs confirming factors.
Value Traps
Q: low, V: high, M: low (junk, cheap, deteriorating)
The great modern value investor, Seth Klarman, has warned “Value Traps are a dagger through the heart of value investing". This is the domain of broken business models, sectors in decline and generally one of the worst places to be in the market. The key lesson to learn is to give loss making, out of favour, cheap shares a wide berth unless they start to show confirming factors. Learn more about avoiding value traps here.
- See more at: http://www.stockopedia.com/content/towards-a-taxon...
Ed, that is an absolutely succinct and superb diagram of the way to classify stocks!
I'm loving the flak I'm getting this week. :-)
The poor old Value Rank. All he does is shine his light into the dark parts of the market that classy investors daren't tread. Not for them to hang out with the grubby, breaking business models, outcasts and rejects where he communes.
He's like a social worker really. He's got faith in them. He knows he can turn them around. It's so depressing for him that nobody else helps.
What is sad for the poor Value Rank is that many of the companies he tries to help don't make it. But what depresses him even more is that when some of his recovering companies do make it out of the poor-house, all those classy investors forget from where they came.
It was ever thus for the Value Rank. Poor, misunderstood and endlessly wishing his work was loved.
"Thus a domino effect of rising wages is likely - bad for profits, but good for aggregate demand in the economy (although much is being offset by the Govt reducing so-called Tax Credits)."
And strengthening the argument for some inflation protection of one's portfolio, ideally indexed to RPI not CPI. I use INXG and IL gilts.
I'm in favour of adding 'Sub-ranks' behind the main ranks - for example the Quality rank captures many different aspects of quality like, Franchise Strength, Earnings Quality, Financial Strength. To rank these all together misses some nuances of investing e.g. I may reject a stock with a low earnings quality rank even if it seemed to have a strong franchise wheras the overal quality rank may be high. Obviously this won't catch every dodgy stock but may help people understand the components of the StockRanks better (and stop them complaining to Ed.)
I also think that there are a number of quant factors that have strong academic evidence for success that are missing from the current stockranks. Having the sub-ranks would enable these to be expanded to better capture the full canon of academic evidence without making any one rank too complicated.
Here is a mind-map that I've shared before showing how this could be acheived. Bold is a factor I would add in that doesn't exist in the stockranks today:
It doesn't have to look exactly like this but I think there is a strong argument that sub-ranks are the way to go to improve flexibility and understanding without the complexity of everyone creating their own ranking system.
Also I think there is a strong argument for including more earnings quality and financial strength metrics in the Quality StockRank and in the screener. For example Ed has said that the CHS model of financial distress is available in the database but we don't have access to this in the screener - surely if these exist behind the scenes then making them available is relatively trivial?
Paul
Pound land is on my personal bargepole list. But an unknown for a retailer such as they is how much the min wage will help their sales line by putting more £ into their customers ' pockets. I suspect management will lay less emphasis on that!
I think everyone has been telling Ed about the ranking system. Dasv has made some good points recently as well. It is about time Ed took onboard some of the criticism and got it changed. You can have more than one ranking system, so call the new one Beta or whatever.
Don't we go round and round and round in circles on this? Here's my previous reply ... and another reply on the same subject here.
There's are hundreds of research papers that measure 'Value' as plain old cheapness. The Value Rank has a long lineage - it stands on the shoulders of giants. You might prefer to think of 'value' as cheapness adjusted for quality measures like balance sheet strength, profitability or whatever... but that's just your personal preference. There are other semantic interpretations.
The StockRanks are a set... they are to be used in conjunction with each other and are better together. The Value Rank is a pure cheapness score - designed so that it can be used standalone (which is foolish), in conjunction with quality (QV), or in conjunction with momentum (VM) or as a triad QVM.
The ValueRank works as it is designed to. If you don't like it or want to build your own - there's nothing stopping you. You can of course come up with your own using a Google Spreadsheet and fill it with the data you prefer. Most people don't want to go to that effort... we're just automating the manual work required with our own methodology - a bit of elbow grease and you could create your own rankings any way you want it.
At some point everyone will be able to make their own rankings using Stockopedia's tools. If you don't like ours you'll be able to come up with your own. Then there will be nobody to blame for an anomalous score - which will always happen. I can't wait really !
" The Value Rank is a pure cheapness score"
Ed, for the avoidance of doubt, why not simply change the term "Value Rank" to "Cheapness Rank" or "Price Rank"?
That would make it very clear to everyone that this ranking is not a measure of "Value", in the sense that most people who are not finance professionals would use and understand that term (as in "good value" which could be inferred from a high ranking) but that it is simply "Price" you're referring to, rather than "Value", a word that has a very different meaning, surely?
Then, people can work out "value" for themselves, using whatever criteria or screening they wish and according to their own notions of what that means.
Actually it will be pretty cool when we can make our own ranks Ed although the problem might be that an adhoc rank will look fine in back-testing and then fail in practice because there's no basis behind the rank metrics.
Either way a Solvency Rank might be useful as it could include, and automate, the type of balance sheet criteria that Paul mentions above.
Damian
"At some point everyone will be able to make their own rankings using Stockopedia's tools. If you don't like ours you'll be able to come up with your own."
That reminds me of Groucho Marx's immortal words:
"Those are my principles, and if you don't like them... well, I have others."
Hi Ed
I sympathise, I really do ... but you're trying to do something very difficult, to make the academic research on investing available to a non-academic user base, most of whom will struggle with statistical concepts and some of whom just like the idea of a nice simple number that obviates the need to do any fundamental research. I include myself in both groups ...
The trouble is that terms like 'value' and 'risk' are overloaded - the fuzzy, commonsense, everyday understanding of what these things are is not the same as the specific, academic, research based understanding of them. And that the latter is predictive and the former isn't is not relevant if you want Stockopedia to be the success it deserves to be.
The fact that this issue keeps on coming up, time and again, should be telling you something. Either you need to stop using these overloaded terms in favour of something else or you need to find a different way of presenting the data. Or possibly both. But you definitely need to start pulling together some tutorial videos or other presentational material. Stick 'em on YouTube and use them as sales collateral - and reference them every time these problems present themselves.
Stick to your guns - please - but make sure they're pointing in the right direction first :)
timarr
A wise person once told me that it is not what you know, but how you know it that counts. I like empirically derived, tested knowledge, not rules of thumb. Keep it up please.
Re: Aldermore (LON:ALD) debt now looks very high? Also involved in buy to let loans, not flavour of the month, since budget.
welcome comment on Somero but also Aldermore. both seem to have recently issued good reports but are declining in price quite dramatically.
As far as Aldermore (LON:ALD) is concerned:
The Finance Bill received Royal Assent. Clause 24 of the finance bill has destroyed the "business model" for highly leveraged landlords.
The Assured Shorthold Tenancies and the Deregulation Act 2015 will help tenants slightly and introduce new obligations on landlords. It doesn't give tenants anything like the sort of protection they have in other countries, but it should prevent things like revenge evictions.
There are now quite a few Buy To Let landlords who will not be making any money in the near future. The sensible ones will be selling now. Most won't be. The medium term will not be pleasant for BTL lenders like Aldermore.
I'd expect more pain to come for Buy To Let. In the short term from the Autumn Statement. I suspect Landlord benefit (housing benefit) will be subject to further cuts, since it seems Tax Credits won't be.
Further out, Basel III is also coming down the track. Clause 24 means it will be worthwhile for HMRC to start chasing landlords who haven't been declaring their income.
The question for the UK housing bubble is when it will pop, not if.
BlueFrew
You could also say that what is a pain for highly leveraged bods is an opportunity for those who aren't highly leveraged or those sat on the sidelines waiting, with low interest rates the pool of potential Landlords to me appears to be higher than ever - i doubt any of the current tax changes will alter what is for most average bods (1 or 2 BTL's) the best way of saving for a pension if you take the viewpoint that house prices go up in line with inflation and interest rates will be reasonably benign.
The hmrc have for some time now had a reasonably large pool of untapped bods who haven't declared their rental income or capital gains there is no real Urgency to go after them - although i would be interested to here what changes with Clause 24 as far as hmrc is concerned.
With regard to bubbles prices here in the North East aren't massively up here compared to the peak before the last recession so i see no reason for anything to pop unless the Economy tanks and interest rates rise - the last recession wouldn't been half as bad as it was if the banks hadn't overnight swapped from lend to anyone to lend to no one and lets have all out loans back - hopefully more prudent rules now will avoid a similar situation whereby entire industries (Housebuilding) ground to a halt almost overnight.
I would agree though there is risk here and knowing me i probably am underestimating the chances of everything going TU.
Be careful. Prices around my way (Cambridgeshire/Essex border) have gone mental, and prices are being set by maximum leverage BTL; as a rule of thumb if you take the expected monthly rent a property (do we have houses any more?) could be said to take and multiple by 300, then that correlates well to the final sale price. 300x is based upon 75% IO BTL loan and minimum required rental cover. Take away the most levered players from the market and capital values will drop. At the same time expect housing benefit to come under pressure in the Autumn statement - this will lower the rental floor.
It's true that HMRC haven't really pursued Landlords up until now. There are reasonably good reasons for that I think. Firstly because of the tax reliefs, they wouldn't get much money from them. Secondly, they've not necessarily had access to the information needed.
Clause 24 changes the first reason. All Landlords will now need to file a tax return, even if they only own one property. HMRC have been running an amnesty recently to allow Landlords to bring their tax affairs up to date. I'm sure the next stage will be to play hardball and get everybody into line before Clause 24 really kicks in.
One the second point, HMRC's Connect system should allow them to access the information they need. Rumour is it works reasonably well, unlike most Government IT.
On house prices. The prices pre credit crunch were crazy. Current prices are also. Admittedly I'm biased. I sold this time last year and moved to rented accommodation. Otherwise I'd have been looking at doubling my mortgage to buy something very slightly bigger. Luckily shorting Afren and Globo will pay my rent (on a much bigger house than I had before) for over 2 years.
Oh and since Ed is having to defend Stock Ranks I should say I've been happy with the returns on my long portfolio as well. My research has been concentrated on much better quality stocks. Special mention about Adept Telecom. I doubt I'd have bought it otherwise. Up well over 100% since buying it.
Hi Paul,
"Or alternatively, you can just manually screen out weak balance sheets, as I do - after all, it's quick and easy to do."
Apologies for my ignorance, but what is your quick and easy method if you don't mind my asking? Is it something that can be screened?
Thanks, James
Hi Paul
Do you or any other Stockopedia subscribers know why the Somero Enterprises Inc (LON:SOM) share price has fallen on relatively small volumes today. I know no trading news has been issued, but would be interested to get your thoughts. I thought the last set of interims were good, and the price has now dropped back to the level when FY results were issued in April this year.
Regards,
Imran.
Best wishes
Imran,
I believe this is probably a similar story to Lavendon i.e. there is some evidence that institutions have been selling down their holdings consistently this year, in particular Polar Capital and this is suppressing the share price. The recent director sales probably didn't help sentiment and the indication from the US Fed that interest rates may rise as soon as next month will not have helped given that SOM has such a large exposure to the US economy.
All the best, Si
Cheers Si.
Imran,
Looking back through the RNS'es it looks like the earliest we'll hear anything from the company is a trading update in mid January. The interims were only two months ago and all sounded very positive so I've put in a cheeky limit order in the hope a clumsy seller will hit it :-)
All the best, Si