Small Cap Value Report (19 Sep) - NXR, TMMG, ANP, NWKI

Good morning, and apologies for running a little late today. So, it's a very strong day today again, with the FTSE 100 up almost 100 points at 6,650, driven by strong gains overnight in the US, something to do with the Fed delaying tapering of QE. Surges driven by this sort of thing make me nervous, as today's euphoria could easily turn into tomorrow's gloom, once things reverse. Anyway, as mentioned yesterday, I'm in careful mode at the moment, top-slicing some things that have gone up a lot, and generally playing it safe, as I want to have spare capacity to buy things on the next dip. Markets feel far too buoyant to me, especially in small caps, and it's very hard (but still possible) to find good value.
I see that the Indian overhang in Norcros (LON:NXR) has unexpectedly cleared, and the Non Exec, Vijay Aggarwal, connected with that former major shareholder (Lifestyle Investments PVT Limited) has resigned. This is good news, as it was a big overhang, and has also increased the free float hopefully, although we'll have to wait and see who discloses themselves as the new holders of the shares. Its re-rating continues, with the shares now up to 20.5p, and still cheap in my opinion. Patience has really paid off here, so I'm pleased to be still holding.
Next I am reviewing the interim results from Mission Marketing (LON:TMMG). This one almost made it into my portfolio, and I reported positively on it here on 10 Jul 2013, given that their profits warning on that day looked fairly mild, but didn't get round to researching it in more detail unfortunately. Pity, as it's gone up about 30% since then! I also noted on 12 Jul 2013 that the Chairman had spent almost £29k buying shares, which is useful in restoring confidence after a profits warning.
At the current price of about 29p the market cap is approx. £22m. So, turning to their results for the six months to 30 Jun 2013, the P&L doesn't look too clever, with turnover up 12.9% to £67.6m, but pre-exceptional operating profit down 30.0% to £1,934k. A £1,486k exceptional item wipes out most of the profit, and financing charges of £380k gets rid of the rest, to leave earnings at just above breakeven for the six months.
In fairness though, this should not surprise anyone, as it was pre-warned about on 10 Jul, when they announced the loss of a major client (B&Q), and another (Aviva) cutting back on their marketing spending.
In his quirky narrative, Chairman David Morgan describes the outlook like this:
With the difficulties of Addiction and Aviva now behind us, profitability is much improved and tracking in line with last year, no mean feat given the volatility in the market. We anticipate a strong second half and expect a similar result to that achieved last year.
So they made about £3m operating profit in H2 last year, so add that to the £2m made in H1 this year, and that means they should be on track to make about £5m operating profit this year. That's bang on what they said back in July, so it's good to see no surprises there. One feels more confident putting a valuation on a company when they demonstrate being able to forecast their own performance with reasonable accuracy.
Stockopedia shows the current year broker consensus at 5.5p EPS, which makes the PER very low at 5.3, but that consensus earnings figure doesn't look right to me, as it's too much of an increase on last year, when they actually look to be heading for a year slightly below last year, so I reckon a more plausible estimate for 2013 would be in the range of 4.5 to 5.0p per share. That makes the PER still cheap, at between 5.8 and 6.4.
It's also good to see them reinstate a small (0.25p) interim dividend, after a 5 year gap from paying divis.
Overall, I'm very tempted to buy, and this share looks like it will probably go higher, especially in a recovering economy, as marketing is just the sort of thing that companies will increase as things become more buoyant.
Chartists will probably like the bowl developing on this chart:

However, I just can't push the button, as it fails my Balance Sheet testing. There are negative net tangible assets of £8m. Also, current assets are less than current liabilities, being just 89% of current liabilities, which is a long way below my usual preference for at least 130% on that ratio. Although one could argue that a marketing company doesn't hold stock, so I should be more flexible perhaps?
Net debt has come down nicely by £3.5m, to £8.8m, but I suspect that's probably a seasonal low, so their £14.7m of bank facilities might be used to capacity at other times of the year perhaps? That introduces too much risk in my opinion, and even though I think money will probably be made on these shares, the Bal Sheet just isn't robust enough for me to put my dosh into these shares. It's probably an opportunity that I'm missing, so more risk tolerant investors might want to look at this one, doing your own research as usual, but it's not for me.
One final point. With the market cap at £22m, and net debt at £8.8m, round that up to say £10m to perhaps be a more typical average throughout the year, and that means an Enterprise Value here of £32m. Although the Balance Sheet shows total goodwill on acquisitions of £70m. So one could argue that the shares represent good value, in that you're effectively buying a group that cost over £70m to put together, for less than half that price. A simplistic way of looking at it, and of course it depends whether the purchase prices paid were reasonable or not, but interesting nonetheless.
A reader has asked me to review today's results from Anpario (LON:ANP). Checking back in our archive here, I mentioned that the shares looked "reasonably priced ... but not a particular bargain" on 1 Feb 2013, when the PER was 12 at 128p per share.
I'd warmed to it by 17 Apr 2013, when my review of their 2012 results concluded:
"Readers might want to take a deeper look at this one, it looks promising, based on my superficial glance at the headline figures. I'm too busy today to spend any more time on it, but I would welcome any reader's thoughts on it, if you have time to do some research on it. Could be a GARP share, if that growth is sustainable?"
Then most recently a positive AGM trading statement was noted here on 27 Jun 2013, although again I concluded that the price was probably up with events at 167p.
So any readers who completely ignored my caution, and just bought the shares, would now be sitting on a fat profit, as they've now risen to 197p! So perhaps the lesson here is that good growth companies are more expensive, and you just have to pay up if you want to be part of it.
Anpario is a specialist animal feed producer. Their interims to 30 Jun 2013 published today look good. There's a 32% increase in underlying EPS to 6.94p (2012: 5.25p). Of the 20% increase in sales (to £13.0m), 13% was organic growth, and the balance due to an acquisition. So it looks like a proper growth business (you always have to be careful not to overpay for growth, if it's come from an acquisition, since that element of growth is obviously a one-off step up in turnover & profit, as the new subsidiary's figures are consolidated into group results for the first time).
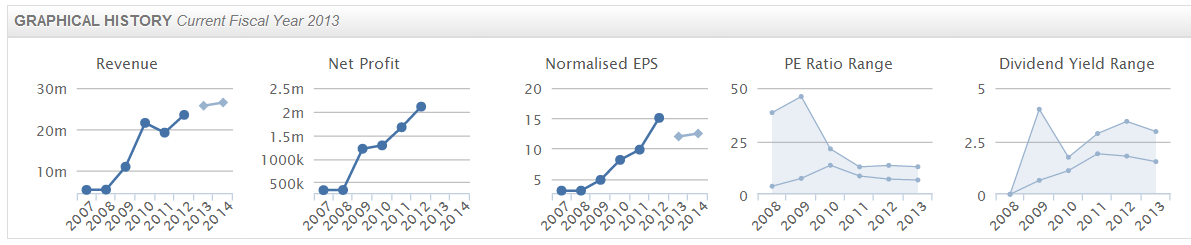
The outlook statement is positive, saying that H2 has "started well", and that "we expect this growth to be maintained". So assuming a similar H1/H2 trading split to last year, then it looks as if this year should produce around 15p in underlying EPS. Although I note that broker consensus is only 12p, so perhaps H2 last year had some one-off gains? I'm not sure, that would be a key question to ask, because if they are heading for 15p EPS this year, then the shares are probably still good value at 197p, which would be a PER of 13. That's not an expensive price for a growth company, particularly one which as in this case, has a very strong Balance Sheet. There is no debt (in fact it has net cash of £5.6m).
So overall, I like the look of this. If anyone knows any more about the EPS query above, then please let me know through the comments below (NB, it is free to register to leave comments - there is an option for a free a/c with Stockopedia, but you have to look for it closely on the registration page, as that drives people towards paid accounts, for obvious reasons).
Finally, results from recruitment firm Networkers International (LON:NWKI) might be worth a look. I've had a very quick skim, and nothing very exciting going on, their interims are essentially flat vs last year's H1. The fwd PER is only 8.7 based on broker consensus forecasts, and their Balance Sheet looks reasonable, and the outlook statement says they expect a strong finish to the year, so looks potentially interesting.
That's it for today, I'll be on time tomorrow, promise!
Regards, Paul.
(of the companies mentioned today, Paul has a long position in NXR, as does a Small Caps Fund to which Paul provides research services)
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

30 comments
I am always looking at companies and try to see why they are successful. Regarding the garage trying to sell me an expensive car, I noticed H R OWIN on the number plates. From that the actual company is HRO , a franchising operation, and the shares are still going up. Someone has recently bought over 50% of the shares , so yet another opportunity for someone to look at.
My local garage owner was also at the expensive Owin dealer & he does the MOT's for them & said "It's only another car" , & he is right. For him another MOT for £40.00 irrespective of the car price. This Norcross looks good to me, but my problem is how many stocks do you hold in a portfolio? I am holding 20 at the moment, and wonder if that is too many. The reason for that is safety in numbers. Weightings are another thing I have been juggling with, trying to catch the timing right.
Some interesting figures from my favourite 700 club comes 4684 letters, 6338 telephone calls, 167,985 tex messages, which seems to signify not so good news for Royal Mail shareholders. Also available from the club this month is a CD discussing money & how we should live. I know I am not supposed to advertise, but joining the club is the best thing I have ever done. For £15.00 you can get one if you want to. Some more lifesaving figures. 13,858 water wells have been dug and operational throughout the world for people with no fresh water. Food & shelter provided from disasters from 5,514,467 people. Regarding value, with only 3 trades last week my commission charges were £53.06 including in that figure is £17.21 stamp duty tax. Now assuming we all pay income tax, any money that goes to the club gets an immediate 25% gain on it because of gift aid. Can we afford that £17.21 tax?. we have to pay it unfortunately. That same £17.21 gift aid becomes immediately £21.51,and does a load of good. Another tip from the club was dividends and where to get the best returns. With a bit of time researching I managed to get 7.9%, which is better than The Royal Mail I think? Based on the figures loads of people are communicating with e-mail & telephone, the telephone comes out with more usage. From the stockopedia ADT,my first stockopedia trade looks good for me. We have a choice, buy sell or leave it. Again from the club comes information where the best tech stocks come from. With Stockopedia I have just come across what I am looking for. Sometimes you have to act fast, but I always like to do some research first. For me there is too many red screens in the oil sector currently. Information for the club is accessed via my profile.
Cheers from Lightningtiger
No that is the truth, the garage is in Pangbourne Reading Berkshire. From a practical point of view that sort of car is not for everyday use & is difficult to get in & out of. Who in the world is Al Murray or Borat?
Cheers From Lightningtiger. Anyway it is only a car.
I am new to this stockopedia and still finding my way round it having made a few blunders on the way. I have and still do use stop losses.Hello Stop loss Sue. When to sell seems to be one of the most difficult things to do. We cannot be right all the time. I have held ARM for many years both top slicing it, selling all & buying back again. The stop loss works well for me. When it hits the mark sell it & get out. Drummed into my head is cut your losses and let your profits run. If you can double your money & sell, well done, leave a bit for someone else. I did that with OXIG this year, & re invested into CLIN & ASOS , Having sold a big chunk of TEP (that has doubled for me as well) as well, to do this with. There is plenty of fish in the sea. Have I done the right things? Looking back I could have left ARM alone and just added to it as time went on & left TEP alone & not had CLIN & ASOS , but TEP did breach the stop loss. The director Wigidor , of TEP has never sold any TEP shares since he started the company. It is all buy, buy, buy. The key to his business works. In a nutshell .......Do you want to save money? or do you want to make money? This system over the years works consistently well for him.There is safety in numbers, & for me has done well. You can look at these screens and say yes but, what if etc. At the end of the day we have a choice. Look at PTO, can this still keep going up at this rate of knots? If in doubt ,leave it out. On my travels around Stockopedia I noticed OPAY last night had one company of the year award. So today I have done a third increase to my holdings in OPAY. It still looks good to me, but I might be wrong. My tip ,Buy on an up, sell on a stop loss, if in doubt leave it out. I could not believe all the chat with SOCO! It, is not my kind of share. My preference is tech stocks and pharmaceuticals generally, but you may well prefer something else. Hope this is of some help to some of you. I have sold my Royal Mail shares ,but you can still buy or sell if you want to. Have I sold to soon? I am happy with the profit. Cash is king .'Had a look at a lamborgene (spelt wrong sorry) today second hand for £118k. any discount for cash? £1000 only, so no deal. The new one over£300k I think. Anyway my Hyundai is more comfortable.
Cheers from Lightnintiger
Hello lightning tiger
I don't wish to be rude but I've got to ask , are you a creation of some post modern comedian?
Think Al Murray or Borat.
Paul,
ANP, your EPS query, no one offs. They had quite a lot of carried forward tax losses. Tax charge will increase I.e they will have to start paying some. That won't be all the 3p difference in your eps figure vs consensus but some. What I like is the degree of operational gearing they have. A good stock, and good people.
I have been reading your reports Paul for about 3 weeks and I'd say you've got the balance right. I have created a "tips from Paul" page on my IPad..........but it does't include any stocks ! It is simply snippets of what you look for (positive and negative) from Financial Reports. For me, you are source from which I can learn and improve my own skills when it comes to reading Company Reports. We all make mistakes, and ultimately, we learn from those mistakes. Those investors out there who want to follow buy/ sell recommendations lack confidence, and perhaps are looking to make big profits quickly and avoid losses ! It is much more satisfying when you DYOR and buy on that basis.
Paul
Interesting comments on both sides. I personally think the more information the better. Take helphire its up around 50 odd percent since you bought in, is that one for top slicing or is it the market re-rating itself? I bought Smiths news and sold 80% when the shareprice doubled now its doubled again so clearly I sold too early, so there is a scenario to keep adding as share prices tend to re-rate themselves over time. I bought Anpario at around £1 however the reason why I bought the share has not changed so should I top slice, or should I add more now others are seeing the story behind the share? I know that you can't answer these questions but I am just giving scenarios.
I like to know what others think, even if its wrong, so for example, you saying "I sold 50% of my shares in stock X as it has moved up 40%" or "stock y is falling for no apparent reason so am adding as it comes down" (maybe ZIOU or VNET are good examples). If a new investor goes to your stock pick excel sheet could they look at it and buy the shares and not know that you have already sold a percentage of your holding.?
I agree you are not a Tipster and DYOR is vital but on balance I would much rather know how you are currently thinking rightly or wrongly as if I were an investor in a stock that you top sliced it would make me look at my reasons for investing again.
Many thanks for all your thoughts and analysis far better than most of the rubbish one reads in the financial magazines!!
Hi Cleeve,
I'm constantly adjusting my portfolio, so it's safe to assume that if a share I hold has gone up a lot, then just assume I will have top-sliced some of my holding, as that's what I normally do in order to keep my portfolio weightings right (i.e. not to become too overweight in a stock that has gone up a lot).
I'm not going to get into publishing a blow-by-blow record of exactly what I buy & sell, and when I do it, as then some people will just slavishly copy those trades, and the point is we're trying to encourage everyone to Do Their Own Research, not blindly follow tips! Also I find that level of detail into my own financial business too intrusive.
As regards the daily reports, I'll always disclose in every report if I have a long or short position in a stock, and will always tell it like it is, as regards that stock - it never even enters my head to skew the commentary according to what I might be planning to do in terms of buys & sells, I just don't think like that, and in any case have not seen any evidence that my reports move share prices anyway.
So my reports will continue to shoot from the hip, and try to cover the good & bad points as I see it in terms of every company. The litmus test is this - I'm often critical of companies that I hold stock in, which can't be said of many commentators - most people relentlessly pump their own stocks, whereas I at least try to be even-handed, although obviously if I hold a stock then it stands to reason that I like the company, or I wouldn't hold any stock in it!!
Also, you've got to remember that all my commentary is free, not a paid-for service, so it's just presented warts & all!
Cheers, Paul.
Paul, just to add my voice: every now and then you come across an investment commentator whose analyses and opinions just seem to make sense.
That's how I feel about you. There are no black and white decisions in investing, and anyone who thinks otherwise is a fool. But your experience in analysing financial reports, and your personal interpretation, based on what is important to you, I find really helpful in arriving at my own decisions.
I am perfectly happy with the level of information you provide about your own holdings. It's just one more piece of the jigsaw.
Keep up the very good work.
Kevan
To change the topic slightly, I've just been doing some digging on 21st Century Technology (LON:C21) and in particular the investor who bought over 4% the last week. The chap is John Watkins, who appears to be the now Executive Chairman of Trakm8 Holdings Plc Trakm8 Holdings (LON:TRAK) (http://www.trakm8.com). It has complementary products to 21st Century Tech in the rail market, and he had this to say in the final results announced on 1 July 2013:
"With its strong balance sheet, good cash generation, and robust business model Trakm8 is in a position to consider augmenting growth through selective acquisitions alongside its current organic growth strategy."
This could just be a private investment or it could be a prelude to something more interesting.
Hi Paul,
I agree with Cig, I think it’s important to update readers with sales and reasons for those sales. The information you provide on here is invaluable and gives novices like myself a much better understanding and chance of survival! I’m sure “StopLossSue” started out with some help and guidance!
That said, if top slicing you obviously still have confidence in the stock and understandably wouldn’t want to cause a loss of confidence in that.
Thanks for all your hard work here Paul, it’s very much appreciated.
Hahaha classic. Those moments are always awkward - great that she took it so well.
I concur on the unreasonableness. It seems that many these days are quick to take their investment frustrations out on the person that gave them - they also tend to have far shorter time horizons which often increases the chances of the aforementioned disappointment occurring.
Enjoy the daily updates - and your insights into the small cap sector are appreciated.
Ah the Pump and Dump brigade. Yes, I'd go further than your "It's just plain dishonest" and have the perpetrators walked through the streets of London with a placard saying such stapled to their chest and back! :)
Hi Paul,
I don't really mind if you say what you are doing, it is interesting though to know what you hold, why you hold them and why you take action. Anything that threatens your frank sharing of information I would vote against. I know from moderating TMF boards in a prior incarnation how careful you have to be.
Sometimes I agree with you, sometimes I disagree but more often I think. Its the latter I value. I personally get much more value from your opinions and reasoning concerning the balance sheet and outlook. Only last week a company (ISG) persisted in getting through my filter (forcing me to evaluate it) and today your prior comments about its wafer thin margins resulted in me tweaking the filter to eliminate it and others like it. Far easier than actually taking any action :)
Seriously, I'm in the camp of give a man a rod and he'll snap it into kindling to cook the fish someone else gave him and he'll be able to catch his own fish, possibly sharing in the future.
I also like the fact that you are relaxed about the timekeeping. I'm often several days behind in reading your comments and have learnt to not make hasty emotive decisions, so the more you stay away from the 'instant' response, which is almost de rigueur in most social media and news, the more comfortable I am!
Andrew
Hi Andrew,
Thanks for your comments, very interesting.
I'm also wondering about talking to the boss (Ed) about timing, as having to do morning reports means I can't really take holidays. So I'm wondering about maybe taking the odd week off, when I do an evening report of the days news, which would give more time to digest & think, rather than rushing through a tidal wave of news every morning.
On the other hand, deadlines & some adrenalin really get the motor pumping, and it is nice to be able to take the foot off the gas at 11am, and have a kip on the sofa!
Anyway, bottom line is that most people seem to like my output, and I really enjoy producing it, so let's keep going!! I'm very grateful to Stockopedia in giving me a platform to hopefully put out useful stuff.
Cheers, Paul.
Hi Paul, I think disclosing when you hold / no longer hold a stock is one thing (guess you may have to for regulatory reasons), but I agree with you that it's up to others to time their buys and sells.
Your commentary is extremely informative and always appreciated (even if your view is different to that of the reader!), but it should be no substitute for an investor to do their own research, and they shouldn't slavishly follow exactly what you say (although that would make a good guru screen - take note, Ed!)
Not sure what investor event you went to last night - was it proactive investors hydrocarbons in Mayfair perhaps?
Hearing 4 pitches at the event reminded me how poorly some tiny E&P companies have performed in the past 6 months; whilst they are right in the speculative corner of investing, some (I'm thinking those that already produce) look quite cheap. e.g. Trinity Exploration and Production (LON:TRIN) (not a presenting company yesterday, but an example of share price underperformance, who issued interims this morning) produces circa 4,000 bopd, share price just over 100p, market cap £100m, possibility to double reserves with their drilling programme in the next 6 months etc and the share price has come down from an equivalent of nearly 600p (if memory serves correctly).
And when you scratch the surfce with stocks like this - you sometimes find that production is being held back by temporary issues, when (and if) resolved the share prices could appreciate dramatically.
Not advocating anyone to have a portfolio stuffed with companies like this of course...
The bottom line is that I'll always give my honest opinion on every share, including being critical of companies that I hold (e.g. I've written some pretty scathing stuff about FCCN, VNET, and quite a few other shares that I hold. If they disappoint, they disappoint, and one should never gloss over that just because one holds the shares personally). - See more at: http://www.stockopedia.com/content/small-cap-value-report-19-sep-nxr-tmmg-anp-nwki-77406/#sthash.AXb5HBxV.dpuf
Sums up my position succinctly as well.
If people want to BUY or Sell after reading your musings then that decision is theirs, and theirs alone.
As for "StopLossSue" I'd suggest that it sounds as if you should just put your money into a tracker. You probably wont as that'd mean you wont have anyone to blame for your own failings.
I'm sure you dealt with her diplomatically PP - I'd personally have told her to get stuffed and do her own homework. :)
Hi Fangorn,
LOL, Oh I like StopLossSue, she's barking mad, but great fun to chat to!
We had a hilarious exchange when we first met, when she politely pointed out that I'd called her a "cretin" on advfn's bulletin board! So I went bright red, profusely apologised, then we got on famously after that.
However, I do think she's being a bit unreasonable blaming me for a share price falling. I can only give my honest opinion on it, and as you correctly say, it's up to each of us to decide if & when to buy or sell in our own portfolios.
One thing that does cross the line, in my view, is if people are talking up a stock, whilst selling out at the same time. That to my mind is just plain dishonest. Although a bit of top-slicing from successful positions is absolutely fine, and good practice IMO.
Regards, Paul.
I was amused this morning when reading the Mission Marketing (LON:TMMG) H1 results to see the chairman starts his report by saying:
But reading on I find although turnover has gone up the margins have come down so they made less money in H1 this year, on a higher turnover, compared to last H1 last year, and then there is an exceptional item on top of that which wipes out all the profits.
Paul Would be very interested to know which stocks you are taking some profits on, the ones that you feel have run ahead of themselves a little. Kind Regards Steve
Hi Steve,
I don't really want to get into that level of detail, because it then gets into being share tipping - i.e. saying when I've bought, when I've sold, etc, and that would potentially cause regulatory problems - and the whole ethos of this site is for investors to DIY, and take responsibility for their own research & finances.
It's very difficult - I always try to be honest & just tell it how I see it, and so instinctively I want to say so when I've sold something. However, that then leads to me getting flak from one or two people (e.g. StopLossSue, who cornered me at an investor event last night & had a go at me for saying that I'd sold my Cohort shares, and she blamed me for the share price going down!).
So I can't win really - damned if I do, damned if I don't.
So on balance, I think I'm happy disclosing what positions I hold in every article, but other than that I think people should make their own minds up about when to sell, it's not for me to decide that. And in any case, I always sell far too early, so you'd be wise to ignore my selling anyway!
Assume that I will always top-slice any holding that has gone up a lot, because that's just good practice to re-adjust one's portfolio weightings.
The bottom line is that I'll always give my honest opinion on every share, including being critical of companies that I hold (e.g. I've written some pretty scathing stuff about FCCN, VNET, and quite a few other shares that I hold. If they disappoint, they disappoint, and one should never gloss over that just because one holds the shares personally).
But let's have a debate about it. What do other people think?
Cheers, Paul.
Hi Paul
Personally, I'd love it if you made sell recommendations. I know you always say do your own research, but effectively your readers are interpreting your daily analysis as buy/don't buy, therefore it would be great to have the other half of the story. I suppose we'll just have to go on reading between the lines, just like we do now in deciding whether your comments about a company point toward a buy or no buy situation.
Hi Clive,
Hmmmm, that's not really what it's all about though.
This Blog is only ever one person's personal opinions - so I'm not infallible by any means, and only have time to have a very cursory glance at most company results. So you really do need to take these as ideas for further research only, that's all they are ever intended as. They're absolutely NOT buy or sell tips. Just ideas for research, to hopefully flag up interesting-looking ideas for people who perhaps don't have time to spend 4-5 hours every morning ploughing through RNSs & interpreting them.
Cheers, Paul.
You appear to have the balance correct at the moment. i.e. saying you bought or sold (Cohort) or top sliced (Vislink) is helpful. It gives the complete picture.
OK, sometimes if the price then falls (and you are a holder) then it can be painful. But in the long run I think people gain from understanding when you consider a set of results worthy of selling your holding. This is very informative, particularly if you give the reason.
I don't think this should just be a buy side discussion forum. I very much enjoy reading your reports both buys and sells, it is informative and educational.
Rick
I think you should disclose your sales, if only for consistency: either disclose nothing, or disclose both. Disclosing only one side makes you open to criticism you manipulate the other side -- even if we know you don't!
Besides I suspect non-disclosure wouldn't remove all complaints, these people would probably still find a way to blame you for talking "positively" or "negatively" about a stock (see Quindell Portfolio!) or blame you for imaginary trades (if you don't disclose, you can be blamed for holding something you don't).
Also, once disclosed, people can just shadow you if they really think you move the market predictably. Even if it's not what you want them to do, the option is there for them, so they have no ground for complaint: either they're right and they can laugh all the way to the bank, or they're wrong and there's no reason to whine in the first place.
To people like StopLossSue, simply tell them that, as you've noted yourself many times, your sales are often too early, so in some quarters they are highly regarded as a bullish signal. For instance, you told us you sold Begbies Traynor (LON:BEG) due to impatience back in May, which reinforced my conviction it was good to hold (I may have got in or added to it had I not been on a full allocation already). It's up 20% since.
Hi Paul,
I'm quite new to this investor m'larky and I really enjoy reading your daily thoughts. It is much more useful to hear why you like some stocks/scenarios and stay away from others. IMO it's then up to the individual to determine whether they feel the same and want to put their money in (after doing their own research of course!). This is soooo much better than the yells of 'Buy Buy BUY!' that a few other bloggers seem to churn out without giving much explanation of why...
One thing that certainly comes across in your blog is an honesty and openess about your thoughts, your holdings, your mistakes... I was quite surprised that it was like this and is the main reason why I'm a daily reader.
Sure, it might be great having your recommendations but if i follow them all then i'm basically having someone else manage my investments and it would be easier for me to just invest in the fund that your provide research to...
Keep up the great work, we appreciate it
Hi Paul
I'd much prefer you said when you are buying and when you are selling and the reasons for those decisions, just like you do at the moment. Then it is up to the individual reader to decide whether they act in unison with you or not. When you are commenting on a share it helps to know when you are "in" and when you are "out".
Good meeting you on Monday and hope to continue our conversation on roll-out formulas another time.
Regards, Andrew
Thanks Paul,
I am happy with my investment in Anp. Looking next for JDG next week.
Cheers
So, is that a similar FY result at TMMG or a similar H2 result? It would help if the Chairman could express himself clearly.
Regards, Martin
Would be grateful for your thoughts on Anpario interims, Paul?
Regards
Hi hedley05,
Right you are, am looking at Anpario results now. Will report on them in a few mins.
Cheers, Paul.