Small Cap Value Report (2 Jan 2015) - HRIP, AFR, RST, RUR

Good morning, and welcome to the first SCVR of 2015. I hope you are suitably refreshed from the festive break, and raring to go!
Unfortunately it doesn't look like many companies are raring to go today, with only one set of results, and no trading statements coming up on the RNS. So whilst everyone else was singing Auld Lang Syne, only the Directors of ISDX-listed Hot Rocks Investments (OFEX:HRIP) were signing off their accounts, although the figures look poor.
It's a tiny investment company, in junior resource stocks. Net assets were only £1.06m at 30 Sep 2014, so presumably the value of their investments is likely to have fallen considerably since then, given the carnage in the sector.
With £49k operating expenses in six months, that means that administration costs in a full year would be just under 10% of funds under management. How can that possibly make sense? The market cap of £1.7m looks too high in comparison with net assets, unless the company has some hidden assets that are under-stated on the Balance Sheet?
I'm only really mentioning it because there's nothing else to write about today. Although talking about the ISDX market, I have been meaning for some time to review every stock on this market. The reason being that in the past I've spotted one or two interesting companies on ISDX (it's a very small market, formerly called Plus Markets, and OFEX). As very few investors look at ISDX stocks, you are more likely to find pricing anomalies - i.e. usually stocks which are completely overlooked. A good example some time ago was Sprue Aegis (LON:SPRP) - a friend flagged up that company to me when it was listed on ISDX and was about 92p. It was a stonking buy at that price, and the value was obvious, but hardly anyone knew it even existed. Those shares have since more than tripled, and the company has moved up to AIM.
As someone wisely mentioned on Twitter the other day, a good way to make money is to find an illiquid market, and then become an expert in it. To a large extent that sums up my approach, although you can still find plenty of pricing anomalies in fairly liquid small to mid caps too.
Afren (LON:AFR)
It's not a sector I follow (resources), but the very unusual nature of today's RNS from this oil producer is noteworthy;
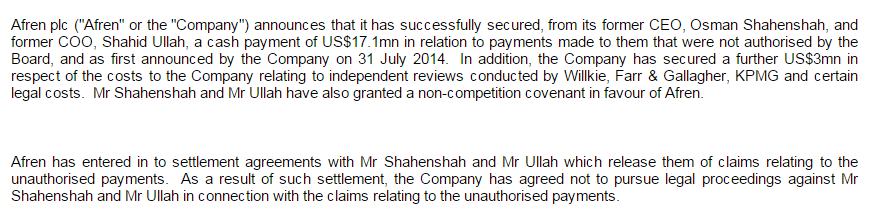
So a good result for the company, but what a bizarre situation where Directors apparently helped themselves to a big wad of cash.
This stock looks cheap on a forward PER basis, but as with all oil producers, you have to wonder if analyst forecasts have been cut back enough to reflect the roughly halving of the oil price in recent months.
I'm very tempted to pick up some oil producers at current depressed prices, as surely the economic development in Asia and Africa, is bound to increase demand for oil, such that any short term over-supply issues are likely to reverse in the not-too-distant future. I'm not an expert on this area at all, but frankly that doesn't matter, as it's abundantly clear that experts haven't got a clue what the price of oil is going to do either! After all, how many experts predicted the recent collapse in the price of oil? It seems to have caught out almost everyone.
Restore (LON:RST)
Announces a very small acquisition (just £500k), for cash.
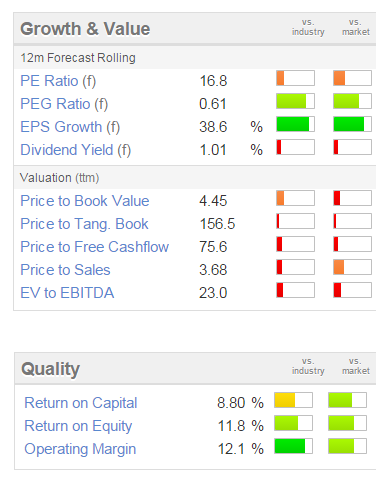
Looking at the Stockopedia graphics, this share looks rather expensive for what it is, on a forward PER of 16.8 times. I can't see how a document storage company is likely to be a growth area, as offices will be reducing the amount they print as things become gradually more electronic. It's surprising that the paperless office has been so slow in happening. I can remember ceasing to print out huge reports that nobody ever looked at, in about 1999, instead just copying the files onto a spare hard disc, just in case someone ever asked to view the reports (which never happened).
Also the 1% dividend yield is unexciting.
On the other hand, bulls such as Mark Slater point out that Restore has reliable recurring revenues, as once documents are stored with them by clients, in e.g. a disused nuclear bunker, or a salt mine, then a monthly fee rolls in reliably, for no additional work. I can see the attraction of that, but sooner or later the market is likely to start factoring in reducing earnings, and I can't see that supporting a high PER in the long term.
Rurelec (LON:RUR)
This is an AIM-Listed company focussed on electricity generation in South America. As you would expect, the shares have been very poor performers, it almost goes without saying - if it's overseas and listed on AIM, it's safest to keep well away, in my opinion.
The company announces today that a hydroelectric project it majority owns has come into service;
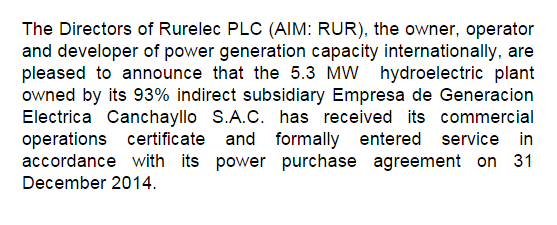
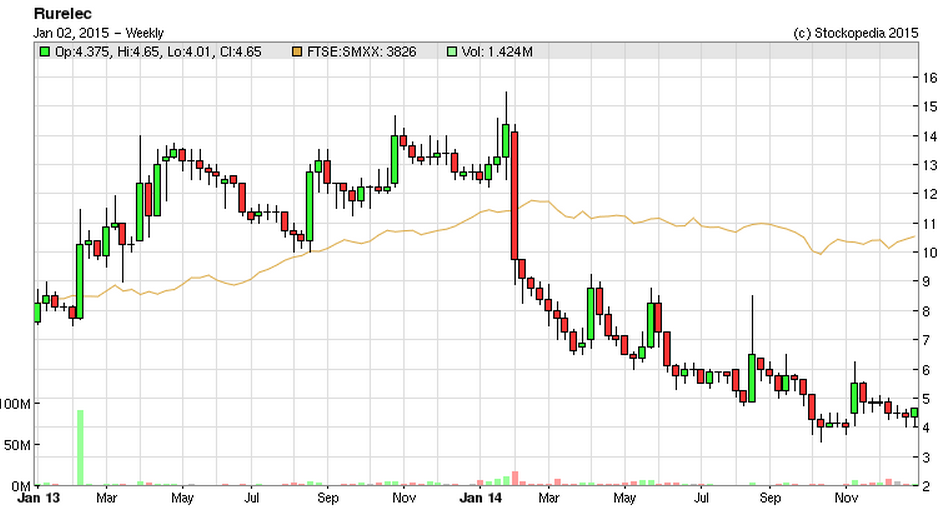
I suppose with oil now halved in price, alternative sources of power are looking less commercially attractive. Although looking at the chart here, something serious seems to have gone wrong in Jan 2014. Checking the last set of results, the issue in Jan 2014 was the devaluation of the Argentinian Peso.
Looking at the company's Balance Sheet, it isn't too bad actually, and at the operating profit level, it only made a small loss in the interims to 30 Jun 2014. Also, with net assets at £54.1m, and the market cap at about half that, the valuation seems quite modest.
On balance though, it's not something I'd be interested in buying.
I shall sign off for today & this week. Next week we'll start to get the trading statements from retailers. The John Lewis figures suggest that the push by retailers to promote Black Friday (yet another Americanism we seem to have forced on us!) may have blunted sales in the days immediately after Xmas. That's bound to happen really, as people only have a certain amount of money to spend.
Incidentally, for anyone interested in history, I've been reading a wonderful book on Churchill, by Boris Johnson, called "The Churchill Factor", and highly recommend it. As you would expect from this author, it's a fast-moving and entertaining read, which rather than following a dull, chronological format, instead dips in & out of key moments in Churchill's life - more like a collection of linked short stories, told with great flair.
See you back here on Monday.
Regards, Paul.
(of the companies mentioned today, Paul has no long or short positions.
A fund management company with which Paul is associated may hold positions in companies mentioned)
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

19 comments
Hi Bsharman
Thank you for the reply. Yes have already found this one and there are few others featuring him which I intend to watch.
I have held RST since 80p some 3 years ago. My key reason for investing was in following the CEO Charles Skinner who previously held similar position at Brandon Hire - which I also made nice money on. I had a strong conviction that he would not have joined RST unless he saw an opportunity - which has proved to be the case. They operate in a fragmented market and acquiring companies cheaply has proved a winning formula - like Mark Slater I see absolutely no reason to sell..
Talking about books, came across The Intelligent Investor: The Definitive Book on Value Investing by Benjamin Graham which gets good reviews, no doubt many of you know it, is it any good?
I see my library have it so I will reserve it.
Paul, just on John Lewis, it looks likes the -1.4% dip in the week to 27 Dec was driven by electricals (-14.7%) with uplifts in fashion (+8.1%) and home (+3%). So perhaps fashion is holding up even after the Black Friday surge.
http://www.retail-week.com/sectors/food/infographic-john-lewis-weekly-sales-fall-to-12624m-as-retailer-toasts-click-and-collect-record/5067573.article
I've been struggling to find the source statement unfortunately.
HP
Thanks for the comments! I've just downloaded the Guy Spier book, so will report back on it once read.
Regards, Paul.
Paul, you need to be careful with oil stocks. Part of the valuation is based on reserves which is the amount of oil/gas which can be economically produced. This is assessed by specialists often annually.
The amount of oil that can be economically produced at $60 is going to be much less than at $110. Reserves will therefore be written down leading to further value destruction.
It's a multiplier on the way up with a reverse effect on the way down.
I'm not saying don't invest in oil, there is plenty of value out there, just be aware of the pitfalls.
Happy New Year Paul
Thanks for the New Year book tip. Mine is Guy Spier's The Education of a Value Investor; just a brilliant, inspirational book in my opinion.
With regard to Restore (LON:RST) It is up 15% since late October when Jim Slater tipped it and I bought £2k worth just to see how his tips performed. So at least it's up. With regard to the paperless office, I think it is legislation/regulation that will drive that. I believe for example, that if a lawyer prints something, he/she is not allowed to do destroy it even if the soft copy exists and indeed since the time computers became mainstream more rather than less paper is consumed/stored.
That said Restore (LON:RST) is definately not a value play and probably one I will convert to cash now and wait for someting better to come along. Also see that Restore (LON:RST) head office is in Mayfair a stones throw from the American Embassy! Does a document management company really need to occupy such an expensive piece of real estate accept to give directors nice places to lunch or am I being too much of a Puritan?
Something in the oil servicing sector looks interesting and I read this morning that Berhshire Hathaway have made some investments in this sector.
Thanks for the column and here's to a successful and prosperous 2015.
I second this recommendation for Guy Spier's book. It is refreshingly honest. Thanks also to Paul for your daily commentary. Hope you have a good year.
I have a 8Hr road trip to Scotland next week so have treated myself to; "The Education of a Value Investor" recommended above, as a Amazon audio download. Perhaps I too will be influenced by Warren Buffet without having to buy a $600K dinner. Will feedback the outcome.
Ian
Hi, Thanks for the book recommendation. This youtube video of Guy Spier is definitely worth watching: https://www.youtube.com/watch?v=ifDCmRBElPY
I'd be very intrigued if you started covering and picking up resource stocks Paul!
The other day I read an interesting point on a commodities investment trust which was trading at 10%+ discount, and the writer argued that it was a great way to pick up bombed out resource companies at an even deeper discount.
Hi Hutch_Pod,
Trouble is, there are too many resource stocks for me to cover, and so many of them are dross really (the junior explorers anyway). Plus you can't rely on broker forecasts now, as they could be wildly wrong, given the collapse in oil price.
That said, I am interested in looking for cash-rich oil producers with low cost production (so that they can withstand this current downturn). Hedging (forward selling of current production) is another problem that muddies the waters. Plus there is considerable political risk with a lot of overseas producers, that many investors ignore at their peril.
I did pick up some Bowleven (LON:BLVN) again recently, after reading that both Paul Curtis & Was Shakoor have it as their biggest holding.
I'm not interested in looking again at any other (non-oil) resource stocks, as my experience with Zanaga Iron Ore (LON:ZIOC) was a good demonstration of how an excellent project can become unviable if the price of the resource itself collapses. I've never quite "got" Gold either. It's just a shiny metal after all - to see it as a currency seems archaic to me. Again, the price movements seem totally unpredictable, so why even try to guess them?
Oil is more interesting though -with Chinese now buying more new cars than Americans (20m p.a. vs 18m), then it's not likely to be long before the excess oil supply is absorbed by increased consumption. Also of course, Americans have always had a penchant for wasting oil in gas guzzling cars, so it halving in price will encourage them to buy bigger capacity, burbling V8-engined cars, and drive them more.
Regards, Paul.
Hi Paul, that makes sense on the underlying resource price risk, which is of course harming the gold miners too.
But this does make it tempting to pick up the quality companies at seemingly low prices!
Thanks
HP
I won't be surprised if the Chinese ban (at least non-hybrid) petrol cars within a decade.
Hi Paul, completely agree about small illiquid stocks.
I also think this is one area where retail investors have an advantage over fund managers. Fund managers charge a % of funds under management, so there are incentives to get big. But as they get bigger, performance inevitably suffers - even if a fund manager identifies a small cap stock like Sprue Aegis (LON:SPRP) that he thinks will treble, it is likely to be a small part of his portfolio and have minimal impact. Hence fund managers spend far too much time trying to second guess what BP, HSBC, Vodafone etc will do - but these companies are so large and mature already well understood, they are unlikely to be able to grow faster than the economy.
Thanks very much for your updates - they are really great.
Hi Paul
I may have said it before, but it is worth remembering my old man's definition of an 'expert':
ex = a has been
spurt = a drip under pressure
(My guess is that oil will slip lower still, and someting else in the Middle East may push producer prices lower in panic. I agree they look cheap at the mo, but they may get cheaper still)
http://www.isdx.com/forcompanies/ourcompanies/default.aspx
Hi Paul
How can I see what companies are listed on ISDX? Can this data be obtained from the Stockopedia database?
Regards,
Imran
Hi Imran,
Yes, Stockopedia does have details of ISDX listed stocks on it. Another interesting one is Daniel Thwaites (OFEX:THW). I held for about a year, but then got bored as the price never moved, and sold out. Of course they began rising the next day, and put on about 25% in a few weeks, sod's law strikes again!
Regards, Paul.