Small Cap Value Report (2 Jul 2014) - BLNX, JSG, MTC, TPT

Good morning!
Blinkx (LON:BLNX)
This is on the cusp of what I define as a small cap (upper limit in a grey area between £200-300m - other people use varying figures), but I suspect it might be coming down more firmly into my territory. The market cap at 66p is around £262m.
I've never quite understood their business model, nor how they managed to generate such strong growth in turnover & profit. It seems to revolve around online videos, and the selling of associated advertising.
You may recall that this is the company that was the subject of a critical blog from a Harvard Associate Professor, Ben Edelman. He also presented at the UK Investor Show in April 2014 in London. I freely admit to not having a clue about the technicalities of what he said, but it sounded credible, and he is credible - you don't get to be a Harvard Associate Professor if you're daft. If his allegations were untrue, then he wouldn't have risked his career by making them, is my reading of the situation.
That's why I have avoided buying shares in Blinkx - on the no smoke without fire principle, even though as noted here on 6 May 2014, they appear reasonably good value - with strong profits that look real (i.e. not created by accounting tricks), and piles of cash on the Balance Sheet.
Also I am suspicious of situations where the share price does not rebound when it should, if all was well. That again makes you feel that there must be some substance to the bearish case against a company.
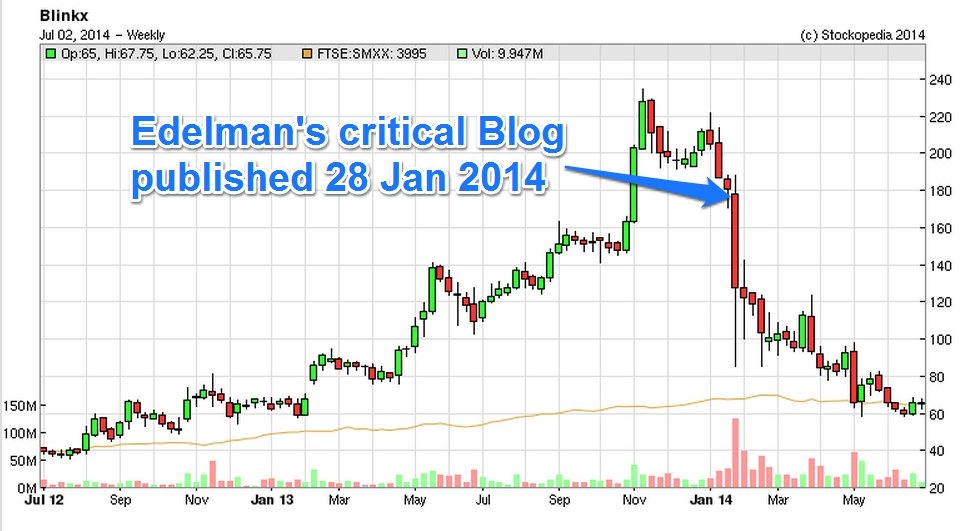
Anyway, this morning the situation seems to have got a lot worse for Blinkx shareholders, as a trading update is issued which is clearly a profit warning. The company refers to H1 trading to date, but seeing as they have a 31 Mar year end, then this looks like a Q1 update to me (Apr-Jun). The key figures are not good;
...As a consequence, while revenues grew c. 5% year-on-year, EBITDA will be c. $5M below management expectations for the Period, based on the Company's internal models.
"the period" presumably is H1 rather than Q1, i.e. expectations for H1, based on trading in Q1, that's how I read it anyway.
Interestingly the reasons given for the profit shortfall specifically mention the attack by Edelman;
Historically, blinkx's business has been back-end loaded toward the latter part of each quarter, with disproportionate growth toward the end of each calendar year. During the last three months, which are seasonally the smallest quarter of the year, we saw lower than forecast demand - specifically within Desktop - with a corresponding shortfall in revenues and EBITDA. The shortfall was exaggerated toward the end of the quarter. We attribute this performance to industry-wide issues of efficiency and effectiveness, which, in our case was compounded by the lingering effects of the disparaging blog about the Company. This resulted in a slower than expected return of demand, despite earlier signs of normalization.
In my view a disparaging Blog might make life a little difficult for a company, but if their product is good, then customers won't take any notice.
In this case there is clearly a more serious problem, so I'm glad my instincts told me to keep away from this share. It's been smashed in the market this morning, currently down 47% to 35p. I'm tempted to buy for a bounce, but am not sure how many bulls will still be bullish now, after tangible proof that the business model is struggling.
My golden rule with investing is to ask, "are profits sustainable?" If there is any doubt over that, and/or the business model is opaque, then it's nearly always best to keep away from the share, because bumper profits might well be a flash in the pan. Also note that the recent trend of shorting/Blog attacks (Blinkx, Quindell, Globo, etc) always goes for companies with opaque business models, and/or where the accounts are suspect (large debtors & poor cashflow usually - although that doesn't apply to Blinkx). So another good reason to avoid such companies, in my opinion.
Although the shares are now (this morning) into value territory where the Balance Sheet may well start to lend some support. The last reported cash was about £75m, and the market cap is now £155m at 39p. So nearly half the market cap is now cash in the bank. So it could get interesting if the shares keep going down. I'd only be interested now at a very low level, more-or-less where the market cap is entirely cash (20p per share), as at least then the existing business is valued at nil.
Johnson Service (LON:JSG)
There's a good update from this textiles group (mainly dry cleaning & workwear rental) this morning.
The Group overall, and in particular our Textile Rental business, will deliver a strong result for the first half of the year. We expect the full year results for 2014 to be slightly ahead of expectations, delivering another year of good progress.
It is anticipated that net debt will be approximately £32.0 million at 30 June 2014 (31 December 2013: £34.0 million on a pro-forma basis).
The shares are up 6% this morning to 62p, which looks an appropriate move for a slightly ahead of expectations trading statement.
On valuation, Stockopedia shows broker consensus forecast as 4.83p for this year, so if we assume that the outturn might be c.5p per share, then the PER looks reasonable at just over 12.
Reported net debt of £32m is just under 20% of the market cap, so in the simplistic way I look at things, that would take the PER up to ballpark 14-15 if the business were debt/cash neutral, which is the way I like to look at valuations. That's about the right price in my view. This company should do well from a recovering economy, so I can see a case for it in a long term portfolio. You would pick up divis of around 2.6% p.a at the current rate, but the divi has been rising by about 10% p.a., and that growth might accelerate as the economy improves?
So overall I've been gradually warming to this share over the last year, and think it could be a nice one to tuck away for the long term possibly? Not exciting enough for me, but it's the type of thing I would look at buying in the event of a general market sell-off.
Mothercare (LON:MTC)
An interesting situation seems to be developing at this troubled retailer. - its specific problems are a weak Balance Sheet - too much bank debt, and a pension deficit, also a loss-making UK operation with significant problem shop leases. Although its overseas operation trades well.
Mothercare shares are up 11% this morning to 255p. The rise has been triggered by a statement from NASDAQ Listed (DEST) Destination Maternity Corp, which says that it is interested in a merger with Mothercare. The proposals are detailed, and they seem to be close to a bid for Mothercare, but two proposals have been rejected by Mothercare, one of which is for a cash bid of 230p for Mothercare, and 70p-worth of shares in the new combined group holding company (to be based in the US).
Mothercare shares have risen further to 260p now, so this looks potentially interesting. I suspect that the bank might well see this as a good opportunity (which it is!) to get off the hook, and might force Mothercare's board to accept an offer or raise fresh equity.
I've had a quick look at Destination Maternity's accounts, and it's not clear how they intend financing a bid for Mothercare, as their 2013 accounts show only $24m in cash. Also the market cap is relatively small at $312m (£182m), which makes it a little smaller than Mothercare. So it's not clear how credible this takeover or merger approach really is? Although presumably DEST would have arranged the finance for the deal before proposing it, or at least have an indication that funding would be available.
So things could get very interesting here. I'm going to watch from the sidelines, and thankfully closed my small short position on these shares a little while ago, when it was rising, when it should have been falling. That struck me as odd, so I closed.
Note that in today's statement DEST reserve their right to make an offer lower than 300p. So combined with uncertainty over how they intend funding a deal, this one is not in the bag. Providing DEST can raise the finance, then I reckon a deal here is likely to go ahead, as the bank (and a lot of shareholders too probably) will want an exit, and could force the Board to accept.
The other consideration is that a third party might get involved with a bid, given that the company is now in play. I'm toying with the idea of going long, but not sure at the moment. Note also that companies with pension deficits are difficult to take over, as a deal would require the clearance of the pension fund trustees I believe.
The announcement from DEST is here.
No doubt MTC are frantically working on a response now, explaining how great everything will be if shareholders reject the approach. The MTC Board have little credibility in my opinion, and a merger/takeover would make obvious sense. So I suspect their days are numbered.
EDIT: The response from Mothercare has been published. It raises some good points, one of which is that there is a question mark over the deliverability of the proposal - i.e. where is DEST going to get the money from? (as I flagged above earlier). I can't see a trading angle on this, although I wouldn't want to be short now, just in case another bidder appears. The DEST proposal doesn't look particularly credible, but on the other hand the bank might well force the issue, so who knows?
Topps Tiles (LON:TPT)
I was right about shares in Topps Tiles having run well ahead of events late last year, and early this year, where they peaked at just over 150p. That was far too high, although the company has been reporting strong LFL sales increases for a while now. So with operational gearing, that could lead to a big improvement in profitability.
Broker forecasts have been creeping up and are now around 7p EPS. I'm wondering if the company might exceed that, so perhaps 7-8p could be the likely range? That's just a hunch based on my previous crunching of the figures here.
Today's Q3 statement is good, saying LFL sales were up 6.3%, which is excellent - clearly the company is gaining market share.
On outlook for the full year (ending 30 Sep 2014) the company says;
The third quarter performance is in line with management's expectations and we remain comfortable with market expectations for the year as a whole.
So to my mind I think that means 7p+ should be in the bag for the year.
With the shares now having come down to a much more realistic share price of 107p, I'm tempted to have a nibble. They could do 10p+ EPS next year, so the forward PER could be as low as 10. That would be an attractive price if it had a decent Balance Sheet. Trouble is, net debt is still far too high here, and it has a horrible Balance Sheet.
That said, the market has disregarded their Balance Sheet issues before, and debt has been refinanced to May 2019. I can't bring myself to disregard the debt, but for people who are more risk tolerant than me, this could be a good entry point at 107p, in my opinion only - NB as usual, not a recommendation, just a view. So vital to do your own research as always.
You know what? I've changed my mind. I think there's a possible 25% profit to be had here, and it pays a dividend, I've bought a few at 108p. Not a big position, just dipping my toe in the water.
On that contradictory bombshell, I shall sign off for the day.
Thank you for reading & commenting, and see you tomorrow!
Regards, Paul.
(of the companies mentioned today, Paul has a long position in TPT, and no short positions)
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

16 comments
Interesting!
Paul, I was quite keen to get on the JSG train, but the directors not holding many shares and their frequent selling scared me off...
Some interesting comments from Cantor's posted on ADVFN regarding the credibility (lack of) to the MTC bid:
http://uk.advfn.com/cmn/fbb/thread.php3?id=16851608&from=892
I think BLNX might have lost clients or failed to attract future clients. One of BE's allegations was that adverts were not actually viewed by persons (but were billed to BLNX clients). If I were a (prospective) client of BLNX I would want to know more about that before paying BLNX any £££.
Also note "The shortfall was exaggerated toward the end of the quarter". This suggests current business is worse than the average of the last quarter.
Hi. I would much rather own Norcros (LON:NXR) than Topps Tiles (LON:TPT)
Blinkx: As I understand it, adware itself isn't illegal in the US, it's getting people to install it by subterfuge. Edelman says that Blinkx affiliates and sub-affiliates do use subterfuge.
See my blog on Edelman's talk http://cheapskateinvestor.blogspot.co.uk/2014/04/blinkx-ben-edelman-is-not-backing-down.html
"Please can we keep the discussion about shares, and avoid getting into disparaging remarks about personalities."
You're quite right Paul, wouldn't want to be disparaging of "The Sheriff of Aim" as he narcissistically calls himself.
I've not seen anything either to evidence it's not a real business.It's throwing off cash. Edelman accuses the company of engaging in illegal activities - we all know how litigious the USA is. if Blinx were engaged in such surely they'd be in the process of being dragged across the burning coals?
It's without doubt that all the negative publicity, Edelman's blog(which was edited daily to retrospectively erase any errors) and the public salivating of prominent shorters has impacted on the business.I'd have been surprised if it hadn't - Technology is a fickle business to be in and things change so rapidly.
Offset against this is the fact that this is the company's quietist quarter is it not?
With the AGM only 10 days away or so it sure will be an interesting event.
The fall looks overly harsh and is, I'd wager, the result of it being another one of the PI favourites - many no doubt with their Spread/T+20/ CFD positions getting caught out in the precipitous drop this morning.
Wasn't sure to put this comment here or in your previous commentary on Networkers International (LON:NWKI) but in light of the c.23% gain over the last few months and a jump up this morning, I wonder if anyone had spotted any news on this. Do you still hold?
BLNX
In essence BE's criticism was that BLNX was using adware which is illegal in the US and led to the collapse of Zango and the purchase of part of its assets with some staff by BLNX. Adware is a programme that is introduced into a PC by a user downloading an apparently helpful programme which carries additional programmes leading to pop up ads which if acted upon can result in an merchant paying for the introduction when it would have got the business at no cost. Zango was fined for doing this leading to it being put into administration. BLNX has denied that it is breaking US law. Guilty or not BLNX would appear to be having difficulty in contracting new business. There has been no report of a pending prosecution or enquiry. If the principal reason for the PW is as a result of BE's blog then Blinkx has to show that it has done all it can to prevent abuse together with evidence of the measures that it has taken to avoid adware being used either directly or through third parties similar to those used by Google. Surprisingly in its previous report regarding the blog BLNX issued a denial and then said it was getting on with business, clearly that wasn't enough. BE was criticised for producing a report commission by potential shorters. Incidentally the recent statement only refers to problems with PCs and not mobiles which is a huge growth area.
Hi Paul. Re Blinkx and Ben Edelman.
I have an immediate urge to check a person's credential these days ever since i recruited a few years back a candidate who claimed to be a fellow of the institute of actuaries only to find out a month later that his qualifications were bogus. Ben Edelman is a genuine article and has a very impressive background. In the past he has taken on Google, Facebook and other major corporations in the US and exposed their dubious practices.
Here is a link to the relevant Harvard's website.
http://www.hbs.edu/faculty/Pages/profile.aspx?facId=417579
Paul, You looked at Concurrent Technologies (LON:CNC) on 27 Dec 2013. I noticed that yesterday they RNSed that BIS would be announcing a relaxation in export controls in 2 weeks' time. As I recall, CNC have blamed export controls for recent sales difficulties.
I remember reading that CNC is a long term holding of John Lee's.
Paul, do you have any plans to write a book on investing and financial analysis?
Thanks.
Fair enough Contrarian. Same outfit though - does the left hand not know what the right hand is doing then?
Fangorn,
The site that you refer to often has opposing opinions on particular shares from different writers - which is very healthy in my view, that's how it should be.
Also I think to describe Edelman as anyone's sidekick is ridiculous!
Please can we keep the discussion about shares, and avoid getting into disparaging remarks about personalities.
Many thanks, Paul.
PP,
Interesting comments PP. Even more intriguing you'll be surprised to hear that Winnifrith, the arch proponent of Blinx having a failed business model recently went positive and rated the company as a Buy given how far it had fallen.
Now call me old fashioned but if a Business model is a busted flush , as he, and his sidekick Edelman claimed, then surely it wouldn't be a BUY at any price? So why the sudden turnaround in his opinion -other than him engaging in his usual charlatan behaviour..
Took advantage of the dip myself and added a trading tranche.
Winnifrith still bearish on Blinkx, it was one of his writers who said the charts say buy. LOL. http://www.shareprophets.advfn.com/views/6199/blinkx-i-disagree-with-gary-as-it-is-a-sell-my-top-three-stocks-to-short-on-aim