Small Cap Value Report (2 June 2017) - PHTM, RBG, ALY

Good afternoon,
Myself and Paul got our wires crossed today. So that makes for an extra-late report. Apologies!
There were plenty of requests at the bottom of yesterday's article. I'll try to cover a few of them today as well.
Cheers,
Graham
Photo-Me International (LON:PHTM)
- Share price: 169.75p (+2%)
- No. of shares: 376.5 million
- Market cap: 639 million
A thread has already been created covering today's update at this link.
This photo-booth/laundry business confirms that the year ended in April was an excellent one for the group.
This follows on from very strong interim results which I covered in the SCVR of December 9th. (It's true that this isn't really a small-cap, but it's a high-quality and widely-followed mid-cap, so I'm happy too make an exception).
Performance is in line with expectations:
The Board expects the financial year ended 30 April 2017 will be in line with market expectations, with significant revenue growth and record progress in profit before tax (+c.20% compared with 2016), supporting the Group's stated commitment to increase the total ordinary dividend by 20% year on year.
So PBT should be in the region of £48.1 million.
There is also good news in the photo-booth business.
Back in January, there were concerns that more relaxed rules from the Home Office meant that demand for photo-booth passport photos would be seriously undermined.
Checking the currently official rules for passport photos, it looks to me as if most people would continue to use a photo-booth in the UK, for convenience, rather than try to print a professional photo themselves.
Outside the UK, government relationships appear to be improving as Photo-Me has partnered with the Agence Nationale des Titres Sécurisés (ANTS) in France, so that photos and data can be uploaded directly to the driving license government database. A similar move is underway in Ireland. And the roll-out of the laundry business is going well too.
All in all, a great little update which confirms that Photo-Me is doing fine.
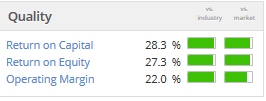
I wouldn't expect fast returns here since the valuation is already full enough (17x PE) but for a long-term buy-and-hold with a quality outfit, I'd say you could do worse.
Revolution Bars (LON:RBG)
- Share price: 126p (-1%)
- No. of shares: 50 million
- Market cap: £63 million
Appointment of Chief Financial Officer
This much-discussed group of bars announces that its interim Finance Director has become the Chief Financial Officer with immediate effect. He is said to have strong prior experience in accounting/CFO roles in various retail and leisure businesses, particularly with pubs and bars.
The prior CFO resigned in February for family reasons, having joined in August 2016.
Shareholders should now reasonably expect that financial performance will improve. To make a footballing analogy, if I was a shareholder, I would now be hoping for stability at the top, and for the new manager to stay for a reasonably long period of time, to implement his strategy! Though of course the influence of the CEO and Chairman shouldn't be underestimated either.
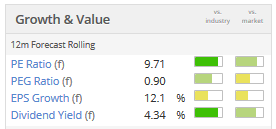
To be blunt, this is not an industry which I find attractive at all. That said, I could probably be tempted to invest if the rating was so low and the FCF high enough that it could be treated as a high-yield dividend cash cow. The metrics aren't a million miles away from that level now.
Laura Ashley Holdings (LON:ALY)
- Share price: 12p (-4%)
- No. of shares: 728 million
- Market Cap: £87 million
A reader has asked my opinion of Laura Ashley, the home furnishing and womenswear group.
This is a share which I traded in and out of in 2014-2015, being very fortunate to make about 4-5p in profit per share before I got cold feet.
I was lucky enough to sell out a few months before it was announced that the Malaysian management team (the CEO and the largest shareholder are both Malaysian) had organised the £31 million purchase of an office building in Singapore.
That purchase, for many investors, raised fundamental concerns about whose interests management were acting in.
While an 8-storey office block in Singapore is a fantastic asset, it didn't appear to make a lot of sense for Laura Ashley to own such a thing. Why not rent instead, and generate higher returns through reinvigorating the brand and expanding the franchise model? If Laura Ashley investors were interested in the more modest returns of property ownership, there were plenty of other investment vehicles through which they could do so.
Fast forward to the present, and the interim results to December 2016 showed LfL sales down 3.5% and PBT down 30% (covered by Paul in a February SCVR). The dividend was cut at last.
High historic dividends have been presented as good evidence that the majority shareholder is aligned with other shareholders, and I think that's a good argument, but it's also possibly indicative of management who don't have very strong ideas about how the brand could be refreshed and modernised for a fresh audience and especially for more recent generations of women. The dividend has consumed the vast majority of the company's EPS since about 2007.
Without wishing to sound alarmist, I might also point out another factor which might have dampened demand for the company's shares recently. In late April, it announced that it was changing auditors to the same firm which also audited a variety of suspicious Chinese companies (Naibu, Camkids and China Chaintek, all of which have been suspended and which wiped out British investors).
For all I know, they may be highly reputable accountants. But for investors who are increasingly nervous about losing their capital due to foreign shenanigans, maybe the optics of this overall situation are just too uncomfortable. The Malaysian links may also be troubling in the context of the recent Fusionex debacle.
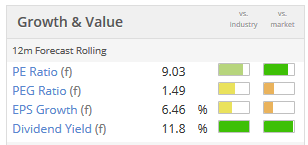
Needless to say, the shares are on sale for the brave. Stockopedia algorithms have classified it as a Value Trap.
That's it for today. See you next week!
Graham
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

17 comments
PHTM: speaking as a customer currently undergoing passport renewal, I did try a few photos with my iPhone but found it very difficult to get something I felt had the right light and background settings. And I mean I really tried. Ended up going to a PHTM booth yesterday and it was quick and convenient. I think many may have exactly the same approach as £6 for passport pics with no hassle is a price worth paying. Snappy Snaps wanted 9.99.
I did my passport last month - woman next to me at work took the photo on my phone with me just standing in front of the wall. Uploaded it. No problems and zero cost.
Comment on Photo-Me International (LON:PHTM). I agree that the possibility of Mobile downloads could impact revenues but what we don't know is by how much and when and the impact on overall group revenue at that point.
With the current terror threat and upcoming Brexit (enhanced immigration checks) validation of Passport photos are only going to get more stringent. If we are invested in PHTM we should all know the current rules on passport photos and physical checks will always be the backstop.
That aside, PHTM is diversifying, the selfie booth is a great idea. Have you been to a wedding / event where a bunch of cameras have been left around for you to snap away. The 24hr laundrette is revolutionary, how many times do you wash your quilt? I It's too big for your home machine. Imagine just being able to pop it into the washer / dryer whist you do your Big shop.
They are solving connivence problems with all the experience and connections of an company that knows how to place machines in others footprint. Buffett talks about Moats, PHTM has one and is creating a second.
The issue for me is more how do PHTM adapt to the mobile phone
Revolution Bars (LON:RBG): how does giving the interim CFO the full time role increase shareholder confidence? For me, that person was fully or partially responsible for the mis-calculation of rising costs that led to the profit warning. At the very least he or she was part of the finance team that made the mistake.
Hi d.
I think you're being a little unfair on the new incumbent. If you look at the timeline via the various RNS, Chambers' resignation is announced on Feb 7th and the new interim CFO was announced on May 5th. Paul Scott met with the CEO and leaving CFO and gave a glowing report on March 2nd suggesting everything, as reported by the company, was rosy. I don't think the new CFO was on the scene at this point and certainly not calling the shots.
The profit warning (or should that be less optimistic growth forecast) was released on or around May 19th. This suggests, to me, that the new CFO came in and shook down some of the accounting functions and assumptions being made and maybe took a less rose tinted view on some of the stuff he inherited. No surprise there as the new broom often kitchen sinks everything to give them a lower base to show improvement from. Credit to the temp for having the cahojnes to make such a call early on.
The fact that this "glass half empty" temporary appointee has now been made permanent is, perhaps perversely, a positive indicator in that it suggests the CEO and other directors acknowledge some of the worms he has unearthed and recognise the value in having a bit more steel in the accounting function. For me, I'll give the new incumbent benefit of the doubt for now but watch closely.
Best,
Gus.
Hi Graham
Just a point on Photo-Me International (LON:PHTM) with regard to U.K. Passport photos, when I renewed my passport I simply took one with my phone, uploaded it straight from the phone, and the system checked it would probably be accepted. I think it's then reviewed later by a person but mine was fine. Much more convenient and cheaper than using a photo booth. I would question why physical photo booths for security photos would continue to exist long term.
Thanks
Photo-Me International (LON:PHTM). Yes that's what I thought, just download photo, no need to print it off. Many visa now you can do the same, one reason why I thought photo booths would decline. Why pay £5 when you can just use a phone or tablet photo?
There is a straight to the point announcement today by Games Workshop (LON:GAW) (covered in these pages frequently)
"We expect the Group's sales for the year to 28 May 2017 to be approximately £158 million and the Group's profit before tax to be above market expectations at not less than £38 million."
I'm pretty please with this and the 15% jump up today.
Graham
In your write up of Laura Ashley Holdings (LON:ALY) you say "Without wishing to sound alarmist, I might also point out another factor which might have dampened demand for the company's shares recently. In late April, it announced that it was changing auditors to the same firm which also audited a variety of suspicious Chinese companies (Naibu, Camkids and China Chaintek, all of which have been suspended and which wiped out British investors)."
That seems to me to be an extraordinarily valuable observation. How did you spot it? If you have a list of advisors who have been associated with suspicious companies, is there any chance you could share it?
Hi FREng, thanks for saying so, it wasn't too hard really as I've looked at my fair share of suspicious companies and tried to work out what was going on with the auditors. If you just go back and look at the high-profile disasters it's very simple to see who the auditors were in every case. I don't keep a list.
Cheers
Graham
Keep up the good work "Sherlock"!!
Peter Barrett
I wouldn't get too excited about the permanent CFO. He was at Regent Inns which went bust. Then at Intertain ( a group of bars ) which underwent a creditors’ voluntary arrangement (CVA) in early 2015 and surrendered unprofitable leases. I believe he was also at BHS in his earlier years although you won't see that on his CV for Revolution. I am a holder still although much reduced at considerable cost as I not sure in the Board's ability to bring the costs under control. Also some director buys would help but that has been sadly lacking.
To add to Graham's comment regarding the high street pub/club industry, the clientele are often very fickle. Locations go in and out of fashion very quickly and for somewhere to become the "in place" again, they often need an expensive refurb. It's this continuous long term drag on cashflow that keeps me out of this industry too. I want my operating cash flow to expand the business, not maintain the existing franchise.
Hi Clive, thanks for the Q. To pay a high rating for a stock, I want it to have a long-term competitive advantage and to be able to grow without using leverage. I think it's tough for the vast majority of bars to achieve this: to achieve a competitive advantage which gives them a lot of pricing power against their competition (for any meaningful period of time). Furthermore, they have a nasty tendency of going bust when their leverage gets out of hand.
So I think of it as a commodity industry, for the most part. I'd still buy into it, but I just wouldn't pay very much.
Happy to hear your views of course.
Regards
Graham
From the jump in Vianet (LON:VNET) today, it looks as though someone has seen the results that are due next Monday and that they are ahead of the recent "in line" trading update.
I doubt that there will be an investigation, unfortunately. Yet it should be pretty easy to do something effective and clhep by using modern data analytics, because most offenders will do it more than once ...
"To be blunt, this is not an industry which I find attractive at all."
Graham, why don't you find the bar industry an attractive proposition? Very interested in knowing why.
Thanks, Clive