Small Cap Value Report (20 Dec 2016) - VLK, SPA, AVN

Good morning!
A very quick run through this morning, as I have to set off as soon as possible after 10am, for a regular investor lunch in Reading.
Paddington station is tricky to get to, from Islington. However, I do enjoy the free WiFi on the GWR trains from there to Reading. It makes the journey so much more productive, as you can do useful things on the way.
I do wish the Government would prioritise free WiFi on all trains, as I think that would be a good boost to economic activity - allowing people to work on trains more effectively.
Vislink (LON:VLK)
Share price: 13.27p
No. shares: 124.6m
Market cap: £16.5m
Trading update - the company reassures on current trading;
The Company continues to trade in line with the Board's expectations for the full year, with Q4 expected to mirror the usual trading seasonality uplift.
The original core business is being sold for $16m, which will clear most of the group's bank debt. This sale was expected to close by end 2016, but looks as if it's slipped into early 2017. If this disposal falls through, then the company is in big trouble, with way too much debt, and a loss-making business in aggregate.
Therefore I wouldn't even consider an investment here until the sale has gone through.
John Hawkins' disastrous, self-serving (in terms of excessive remuneration) stewardship here has resulted in the original business being sold off in a fire sale, to repay the debt he ran up making acquisitions. He's got form on this - a series of acquisitions ended badly when he ran Anite.
However, that's water under the bridge now. The only question is whether the remaining software business - Pebble Beach - is worth more or less than the market cap?
A table is provided today, which shows that Pebble Beach (i.e. future Vislink) is profitable. However, I've also flagged up the hefty central costs. So the key question is how much of the central costs will depart along with the main business that's being sold?
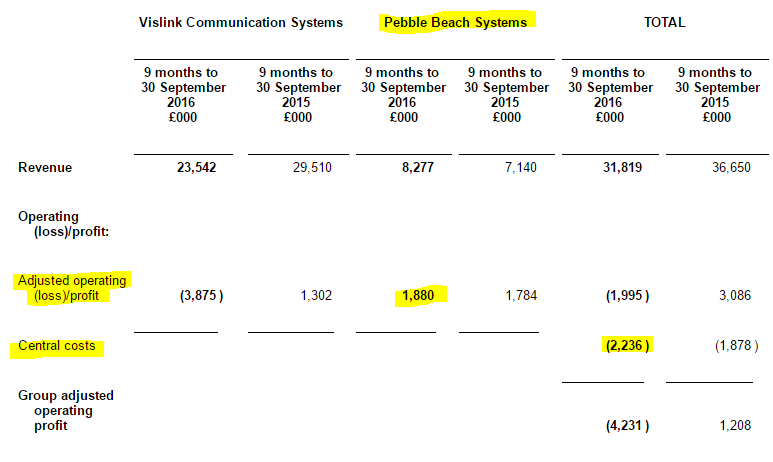
At a guess, it looks to me as if new Vislink (i.e. Pebble Beach) may make a profit of c.£1m after reduced central costs. As such, the market cap of £16.5m doesn't look particularly attractive to me.
I'd want to look very closely at the accounting procedures too, as I've always suspected that the figures might have been buffed up a bit, to give a nice shine.
Overall, Vislink has been a complete dog under Hawkins' tenure - just look at the share price chart. Therefore I wouldn't invest in it unless & until he's been sacked. Of course then you'd have the cost of a 12-month severance payment - a ridiculous and unjustified perk for rubbish Directors.
I feel that notice periods should be no more than 3 months for Directors. The existing 12-month norm is just another way in which Directors deplete the funds at companies they work for. All the more galling for shareholders, in that it's a reward for failure, for departing Directors.
1Spatial (LON:SPA)
Share price: 2p (down 27% today)
No. shares: 734.9m
Market cap: £14.7m
Trading update (profit warning) - oh dear, it's contracts slipping into 2017 that has triggered this warning;
While 1Spatial's sales pipeline and order book remain robust, due to a number of factors, including transitioning the business model to one of annualised revenues and the extension of the industry sales cycles, timing of certain key contracts are now expected to fall into 2017.
As a consequence, the Company now expects to deliver a marginal Adjusted EBITDA loss for the full year ending 31 January 2017.
The Company anticipates ending the financial year comfortably within its current banking facilities.
1Spatial has taken a proactive approach to the short term challenge it faces, assessing both the cost base and assets of the Company, as management seek to preserve cash and maintain its core focus.
It goes on to say that one business has been sold for an insignificant amount, and another has is being closed down.
My opinion - I've never properly looked at this company before, and on this update can't see any particular reason to change that approach today. I just wanted to flag it here, so that the profit warning is recorded in the archive here.
Avanti Communications (LON:AVN)
Share price: 22.9p (up 9.2% today)
No. shares: 147.4m
Market cap: £33.8m
(at the time of writing, I hold a small short position in this share)
Refinancing & completion of strategic review - the bondholders are in control here. They have allowed the company to continue operating, and have provided more cash for it to launch another satellite
However it seems very obvious to me that the equity (shares) are probably worth nothing. This is because debt ranks ahead of equity. So the poorly performing business (which struggles to get into the black even at the EBITDA level) stands no chance of generating enough cash to even service the (very high) interest on the debt, let alone repay the capital.
Today's refinancing sees the debt pile grow even greater, to a staggering $856m after this refinancing transaction. Bear in mind that the business only generated $7.8m EBITDA in the year ended 30 Jun 2016, and you can see what a complete pickle the company is in.
They tried to sell the business, but got unsatisfactory offers, so a sale is no longer on the cards.
My opinion - clearly the bondholders see more overall value in the business if the new satellite is funded, and the launch goes ahead. However, it's very difficult to see how new business is likely to generate enough value to make the business viable again.
However, as a friend pointed out to me last week, the bonds are actually trading not far off par value. So maybe the situation isn't quite as bad as it at first appears?
I remain of the view that the eventual outcome here is likely to be a big debt for equity swap, that is likely to essentially dilute existing shareholders down to virtually nothing.
The big problem with satellite capacity is that the selling price is constantly reducing. Existing satellites quite rapidly become obsolete, yet they cost a fortune to put in orbit. It seems a very unattractive business model.
Avanti has been a serial disappointer, so why is that going to change? I doubt it will.
There's nothing else of interest in my universe today, so I'll leave it there.
See you tomorrow!
Regards, Paul.
(usual disclaimers apply)
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

18 comments
Thank you for the report Paul.
I am still holding some shares with a profit of £1000. Will sale them tomorrow !
Hawkins has history, you can look at Anite one of his previous companies, you will find a similar story there, excess pay tumbling profits.
Re Vislink. Wow. Guys. Well done. Enough of the back slapping self congratulations already. Surely you're making the cardinal sin of looking backwards here and pricing the company on historical legacy issues. Having researched Pebble Beach Systems extensively I actually see a bright future for the new look VLK, with or without JH. Cemtral costs largely disappear with VCS. And profits for PBS likely to be £2.5 to £3 million.They are a fast growing software company and once the sale of VCS completes the market will spike the shares higher. I'm pretty certain the deal will complete so I've bought a holding at these levels to gain entry at ground floor level. Always look forwards, never look back.
I to got out at 59.75p, I was looking forward at the time, since then the LTIP was announced and the shares have plummeted. I see Hawkins is still on board and he got 2m free shares in August. There were some dodgy things going on with his remuneration, such as settling his tax bill directly with HMRC so it did not show up as in his pay.
I won't be getting involved again. Good luck with your investment.
But surely all of those people who sold out in the summer of 2015 were looking forward and that what they saw in the future was not very appealing?
Yes maybe a little bit too much back slapping but the point I was making was that I think one needs to assess the management qualitatively not just the numbers quantitatively.
Finally I would quote the great Ben Graham when he wrote in "The Inteligent Investor":
"Those who do not remember the past are condemned to repeat it".
Good luck with the investment but for now it is not for me.
Benjamin Graham may indeed have been great, but he certainly wasn't the original author of that quote!
I know (he does not claim it to be an original thought but attributes it to Santayana), but he saw the wisdom in the saying, which I believe many people today do not!
The trouble with Vislink (LON:VLK) is that the historical legacy issues haven't gone away, they're still running the company.
timarr
Where do you get "profits for PBS likely to be £2.5 to £3 million" from !!
I also got out of VLK due to the LTIP generously rewarding the directors. Agree with FREng that PI's are powerless and the institutions should act as the greed police.
Andy Roberts, ex Innovation (LON:TIG), is now running 1Spatial (LON:SPA) and he seems to have taken some radical action. The analysts at TechMarketView say that Avisen was loss making (I haven't checked the accounts, but they are a skilled and specialist team at TechMarketView so I assume they are right). If Roberts has kitchen-sinked the results, as you might expect a new CEO to do, 1Spatial (LON:SPA) may look up from here.
Vislink (LON:VLK) completely agree with Paul. I was lucky to get out in August 2015 with a £372 profit before Vislink (LON:VLK) dropped 85%. This was from no great insight as I did not know about Hawkins' "form" but the VCP just seemed over generous in relation to the size of the company and only in the interests of the management and not the owners.
It helped confirm my rule that I must like and trust the management (obviously I can only glean this from reports such as this) before I invest.
Vislink (LON:VLK). I too was lucky to get out in July 2015. My note says "Sold 30,000 at 55p because of the rapacious director reward package being introduced." and this has become a strong policy for me. If the institutions adopted the same approach they would protect their investors' assets and act as some deterrent to such greed. I don't think that PIs can have any influence at all.
Vislink (LON:VLK) I too got out immediately on 2nd July 2015 as a result of reading Paul's report. I had no idea JH was part-time and was shocked at the way in which the low hurdle was set for the obscene reward package. I bought at 34p in 2013 and sold my modest holding at 56.5p making a profit of £813. I was lucky. I have learned a great deal through following Paul's SCVR. One of the fundamental things I look out for now is quality management. If any doubts I don't invest - or if invested get out quick! Thanks Paul!
Vislink is now far too small to support Fatty Hawkin's greedy remuneration package - surely the non-Execs must see that.
1Spacial: I find it curious that they are selling one business Avisen - when in turned over £1.4m and generated a profit of £0.3m for only £0.1m - a third of what it generated in profit and receivable in 12 months time!! That deal requires more justification I'd say.
Surprised Avanti Communications (LON:AVN) bondholders didn't play hardball and grab most of the equity as well.
Dismal FY and Q1 results also released later.
FY rev fell 3%. Debtor-days more than double to 350d. Admittedly 1/3 of that is accrued income. Q1 rev $18m, EBITDA -$6m. No comps, unlike a year ago. In fact rev is up but EBITA loss doubled.
"The Group has sufficient cash balances to comfortably meet all of its medium-term financial commitments and management expects cash generation to grow swiftly as revenues exceed Avanti's largely fixed cost base." Oh, hang on. That was a year ago. A year is a long time in orbit.
Do these new bonds they are issuing have first call on the company's assets,at the possible expense of the other bondholders ?