Small Cap Value Report (20 Jan 2017) - BJU, CCT, CBG, BON

Happy Friday,
Today I'm looking at Brainjuicer (LON:BJU), Character (LON:CCT) and Close Brothers (LON:CBG).
Paul, who is on his day off but can't stay away, will be covering MySale (LON:MYSL) and Bonmarche Holdings (LON:BON).
Paul also made a couple of late updates to yesterday's report.
That report now includes all of ST Ives (LON:SIV), Revolution Bars (LON:RBG), FreeAgent Holdings (LON:FREE), Portmeirion (LON:PMP), Mission Marketing (LON:TMMG).
Best regards
Graham
Brainjuicer (LON:BJU)
Share price: 675p (+13%)
No. shares: 12.2m
Market cap: £82m
It feels like just the other day that I last covered a trading update from Brainjuicer. Indeed, I covered it in the Dec 9 report; the shares rallied 7% that day when the company announced that results would be "above current market forecasts".
Amazingly, the shares are up by a further 27% since then.
But this is a "juicy" statement:
For the 12
month period, Gross Profit, our main top line indicator, increased by
some 27% to approximately £25.6m, driven primarily by continued strong
progress by our US business and an encouraging recovery in Continental
Europe.
Besides improving fundamentals, the share price rise also reflects an effective short-GBP position:
Excluding the impact of exchange rate movements the increase in Gross Profit was some 15%.
For me, the best thing about this update is the success in the Ad Test/Brand Tracking services. As I've pointed out before, and as the company reiterates today, these are "comparatively high margin and scalable quantitative services". Well, their contribution rose by 80%, to make up 39% of the company's total gross profit.
Back in September, I thought we were in store for a pre-tax profit here of c. £5.5 million, which I revised to c. £6 million in December. Today it announces that it is going to achieve c. £6.2 million.
In December, I forecast that cash at year-end would be "possibly in excess of £6.5 million". Amazingly, it has achieved £7.8 million. So it has beat everything I thought it was going to do.
This is a share I've been watching for quite a while, but failed to personally participate in the share price increase, despite always having a positive view of the company.
Unsurprisingly, the Value Rank is now looking rather poor:
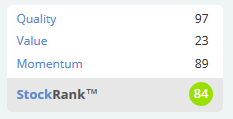
This is going to continue to be awkward for me, as I'll continue to congratulate the company on its success and laud its merits, while admitting that I don't really know if the valuation makes sense.
Higher tax rates apply to business in the US, so that net income might end up a little over £4 million. For me, the market continues to apply a fairly high multiple to a lot of contract-driven, B2B work, which is difficult to predict.
Character (LON:CCT)
Share price: 490p (-6%)
No. shares: 21m
Market cap: £103m
A short update for the company's AGM, held today.
Whilst we are confident that the market expectation for
the 2017 financial year shall be achieved, we expect the results for
the first half to be lower than those reported in the comparative period
last year. In the four months to December 2016, sales were marginally
lower than the same period last year and as expected UK gross margin was
adversely affected by the devaluation of sterling... We are expecting both
our international and domestic sales to grow in the remainder of the
financial year.
So the company is fairly confident that the results since August have just been a temporary blip.
This is another company I rate positively. Of course it's a very different industry to Brainjuicer (LON:BJU), but the rating on Character (LON:CCT) puts it in "value" territory for me. While both companies yield c. 3%, Brainjuicer's dividend cover is between 1.5-2.0x, while Character's is covered around 3.0x!
Which makes this sentence unsurprising:
Our balance sheet, including cash position continues to
strengthen considerably; we shall maintain our progressive dividend
policy.
It makes sense that the shares would fall today after a disappointing few months, but this could be one to buy and hold for the long-term.
Remember that it's not an intellectual property owner, so the valuation rating should probably never get too high.
Close Brothers (LON:CBG)
Share price: 1444p (+1%)
No. shares: 150m
Market cap: £2,167m
I hope Paul will forgive me for covering another big-cap, but financials are one of my preferred sectors!
It's a solid update from this merchant banking group:
The Banking division has generated strong returns and profit growth during the period. This was driven by both higher income, with a stable net interest margin, as well as a lower bad debt ratio, as a result of continued good underlying credit performance and provision releases.
The loan book was up 2.3% over the period
and 9.3% year on year at £6.6 billion (31 July 2016: £6.4 billion),
driven by good growth particularly in the premium finance and property
businesses.
If you've seen "WINS" making a market in securities you've been trading, you've probably been contributing to Close Brothers results, as it owns Winterflood Securities.
Winterflood delivered a good performance, with strong retail trading activity throughout the period.
The spreads in the small-cap market are a source of annoyance to me, but buying CBG is one way of accessing the profit stream they create!
Outlook
"Given our performance year to date, we are confident in delivering a strong result for the first half as well as a good outcome for the full 2017 financial year."
My opinion
I think this is a very solid business, which has proved its worth through good and bad times.
Return on equity is excellent, at c. 19% over the past two years, and with a very attractive net interest margin of more than 8%.
In general, the non-bank financials are far more interesting to me than the banks, because they don't waste capital on low-margin activities.
For example, Lloyds Banking (LON:LLOY) is guiding for a net interest margin (NIM) of c. 2.7% this year.
Barclays (LON:BARC) earns NIM of 9% and ROE of 18% in Barclaycard, but in the Personal & Corporate Banking division, it earns NIM of 3% and ROE of 12%.
So I generally stick to non-bank financials for potential investment opportunities, and CBG is one I'd consider. It's currently paying a yield of 4%, which is well-covered.
(This section is from Paul Scott)
Bonmarche Holdings (LON:BON)
Share price: 82.5p (up 4.4% today)
No. shares: 50.0m
Market cap: £41.3m
Trading update – covering Q3, and the year to date (the company has an end March 2017 year end).
This value ladieswear retailer has had a dismal year so far. So in that context, the update today is much improved;
Sales for the 13 weeks ended 24 December 2016 increased by 3.3% against the corresponding period in FY16, and store LFL sales increased by 0.8%.
Sales for the 39 weeks ended 24 December 2016 decreased by 1.3% and store LFL sales decreased by 5.3%.
So the trend for LFL has dramatically improved, back to slightly positive, from deeply negative earlier in the year. Remember also that the dismal Q1 & Q2 sales will present a nice soft target for the company to hopefully beat in 2017.
Gross margin has also improved noticeably, which is excellent news;
A less promotional stance was taken throughout the quarter and whilst this impacted overall sales volumes it resulted in stronger gross margin performance, with product gross margin in the quarter 2.2% higher than in last year's corresponding period.
Investors generally tend to pay too much attention to LFL sales, and not enough attention to gross margins – which can have a dramatic impact on profit. So this is good news, and 220bps on the gross margin is a hefty amount.
Outlook comments are positive;
The Company's financial position remains sound and the Board's expectation for the full year is unchanged, with our expectation being that the Group's pre-exceptional PBT is likely to fall within a range between £5.0m and £7.0m.
Hooray, the company has given a range of likely profits for this financial year – well done, and thank you – this clarity makes life so much easier for investors. Everyone should be doing this.
Valuation – given the above update, we can rely on broker consensus for this year, which is 12.0p EPS. Therefore the current year PER is 6.9. That looks good value, especially as the company does indeed have a strong balance sheet. So this is an exception to the usual rule that claiming to have a strong balance sheet often means the reverse is actually true, as we saw with 2 companies in yesterday’s SCVR.
Dividends – is the 9.5% dividend sustainable? Usually a yield that high is a signal that market expectations are too high, or that profits are unsustainable.
In this case however, my number-crunching suggests that the company actually could continue paying divis at this level. Providing trading doesn’t deteriorate further of course. Mind you, divis are a policy decision, so the company may decide that it’s prudent to lower the divis in future, which would probably be negative for the share price.
My opinion – I’ve got mixed feelings about this share. Today’s update is good – they have steadied the ship. However, the RNS notes that online sales are poor, and I generally worry about the survival prospects for retailers who have not managed to crack selling online as well as in physical stores.
The benefit from selling online is obvious – you get 100% geographical coverage, far wider than a store network. So even people out in the sticks can buy from a website. Also, there’s a chance of some overseas sales, although probably not material for a value retailer like this.
As we know, all retailers are up against serious cost headwinds, due to the lower sterling:dollar rate making imported product (basically everything that they sell), increases in staff costs, possible business rates increases, the list just goes on & on. To cope with this, retailers have to be generating LFL sales increases to absorb the cost increases. If they don’t, then an operationally geared fall in profits can decimate the bottom line.
All the while, online competitors are skimming market share from the High Street incumbents. That said, at the value, middle-aged end of the market in which BON operates, I imagine internet competition is less intense.
In normal market conditions, I would have probably hit the buy button today. However, I’m not going to, because we’re in a market that just isn’t interested in value shares, and declining sectors such as this. So how much upside can there be on this share? I don’t know, but maybe not much. That said, it’s bound to catch the eye of dividend income seekers.
Overall, I have to say it’s very tempting to pick up a few at this level. It depends whether the turnaround in trading continues, or not, and that’s the key bit of information which we can only guess at.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

22 comments
I would love to hear Paul's view about the MySale (LON:MYSL) update. The only thing that made me slightly nervous was there was no real update about how they are doing in the UK - perhaps because they will give that update in their full results but perhaps it is because growth is not as stellar as they'd like.
Also a pity they still haven't RNS'ed the fact that they are now running their own online clothing brand! Check it out here: https://www.londonchic.co.uk/ I am a bit disappointed with its website though as it seems to have a few bugs on Firefox and it looks a bit bland. Anyway the key thing is that could help margins if it's at all successful. The market cap is £195m (even less when you exclude its tonne of cash) which I don't think is massively demanding for a company that is improving its profitability and is still growing nicely, albeit not as fast as the likes of Boohoo.Com (LON:BOO). I'm long.
Thanks for your coverage of BrainJuicers results.
They did properly smash all expectations and I agree that it is the 80% growth in the "sticky" and not just "juicy" Ad/Brand Tracking services that is most encouraging.
Canaccord have increased their target price to £7.20 on the basis that they will increase PTP by 13% next year. I think there is a good likelihood that these targets will again prove somewhat conservative.
The company is on a roll - it has successfully established a strong niche providing a different kind of market research. In an era where disruptive businesses are hot property - BrainJuicer is well placed to capitalise on a total shakeup in the way that market research is undertaken.
Am I in love with this stock - a little, yes, I admit and probably more than I am prepared to admit.
Their shareprice has never really been cheap - this has put off many from investing. Perhaps falling in love can actually sometimes pay off!
Hi Graham
Just want to add my thanks for your coverage and views on 'financial' companies. Especially as some may stand to gain from the rise in interest rates. I hold Close Brothers so grateful for your take on that
Santa
Further to my post above and Gus 1065's comment, I have just read the N Brown (LON:BWNG) trading statement from 19th Jan. JD Williams up >10% - so the seniors ARE going online !! Bye bye Bonmarche!
Overall, I thought this was an excellent trading statement for N Brown (LON:BWNG), the best for ages. Normally, I rely on Paul Scott's thoughts on retailers but he missed this one (or it was too big). But 70% sales online now, mature business but growing online at double digit rates, Fit for the Future spending starting to fall away . If this was a sexy IPO company, it would starting to look good - and not be on a 9.5 PE with 6.5% share
If only they would sell the Specialist brands and cut the the debt, I think the shares would power away. Have been and remain a holder through some difficult times of late but think that an "internet butterfly" is now only a couple of years away.
(Blimey, just realised I am starting to have done DYOR and formed/acted on my own views - the training wheels supplied by this column and its contributors must be ready to come off. Thanks from another grateful PI graduate. )
On Bonmarche Bonmarche Holdings (LON:BON), I think it will be a value trap. Follow the consumer. Their average consumer is a female pensioner over 65 who walks in to the store and buys a (pretty sad !!) range of products of basic items. This demographic grew up and formed habits pre-computer. It is literally also literally dying off. It is trying new locations but I doubt the sales density and margins will be enough. In the short run having only the best stores out of administration makes everything look good. Long term I can only see it declining.
There IS a population bulge entering run up to and early pension age (baby boomers) but they are far more demading in terms of range and shopping experience and online shopping is not so scary or unfamiliar to them. The benefits of convenience and increasing ease of use make them a group likely to very rapidly migrate on line in my view, especially as the first digital natives come of age and command the economy. This is a great potential opportunity for JD Williams of N Brown (£BWNG) which is now revitalising its image to appeal to this group specifically and has spent 4 years in the wilderness and lots of money migrating its catalogue buyers online. (Disclosure. I hold (£BWNG) for this reason) and possibly at the top end for NEXT (£NXT) - instead of GAP Kids, how about Next Seniors. Bonmarche is too small to have scale and too weak a brand to justify aggressively moving.
If there is any value in Bonmarche Holdings (LON:BON) it lies not in the stores but in thevery specific database of 250,000 frequent Bonmarche users of their loyalty card. This will be a great buy for JD Williams in 5 years time when Bonmarche (as its parent Peacock did) goes in administration!
Graham,
It is vital to cover Financials because of Brexit.
(Employment, Euro-clear, Volumes, US firms using London as base, Property firms letting office space to them.)
Paul looks at it now and again anyway; e.g. CNKS, PMR
Hopefully this post will find echoes.
Despite 'Big Bang' (1986), there is still too much 'landed gentry' mentality among the 'chaps' in the City to my mind, especially when it comes to sharing information.
Technological platforms in North America are more more friendly to the P.I. through limit order duration (30-60 days) and commission rates (no stamp duty).
Nevertheless London is better placed in the time zone and closer to Europe and the Middle East. There is also a vast pool of talent.
So what happens politically over the next few years will have a huge effect on the performance of the sector. Any imput from someone who feels familiar with the sector can only benefit Stockopedia subscribers.
Great comment, aflash, I'll do my best!
I was recently checking Purplebricks terms for post payment of fees (trying to figure out how they ensure payment) & apparently the fee is owed to Close Brothers. So I suppose Purplebricks offload that risk ?
Yea, invoice factoring is a large part of the Close Brothers business.
They are in fact a bank, but a merchant bank rather than a high street retail one.
That's true and I hope people are aware that I am only excluding conventional high street banks when I say "non-bank financials". There are lots of other financial companies which borrow and lend (some of which have official bank status, and some don't).
In reply to Damien (post 1) re Synthomer, I was pleased with the update, some 23% over consensus forecast. The outlook for 2107 is moderately optimistic.
If after tax profit is about £100mn, and anout 340 mn shares in issue, the eps comes out around 30, giving a historic P/E of 14. There is a fair amout of debt plus a significant pensions deficit, so maybe fairly valued? However I am happy to hold as the company has tended to under promise and over achieve, and may buy more on a dip.
Richard
In reply to Herbie47 re Character.....is it also significant that in their RNS dated 1 December they stated "current trading is commensurate with the company achieving the Board's profit expectation"?..... no mention of the lower sales in the four months to December referred to today. Might this have lowered the share price prior to them selling their shares?
I held Character but sold this morning aggrieved.
Re: Character (CCT)
The best sales for a toy company should be the months leading up to Christmas. So why are sales down on last year? The RNS gives no explanation unless they have put up prices to cover import costs and suffered as a result. I almost sold after the December RNS but gave them the benefit of the doubt. This is one of the behavioural quirks that Ed Croft talks about. I assess shares I own more favourably than shares I don't own. Having made the decision to buy I find it difficult to change my mind. I need to keep reminding myself of Paul's motto - when the facts change, I change my mind.
I sold this morning. There are enough really good investments out there. No need to hold on in the hope that my optimism becomes justified.
"The best sales for a toy company should be the months leading up to Christmas. So why are sales down on last year?"
Well, presumably they're comparing them to the run-up to the previous Christmas, so it's not a given that they should rise. Having said that, a sales miss in the busy period will have a larger affect on the year than a miss in the quieter period.
I think it's reasonable to give shares one holds slightly more benefit of the doubt, since otherwise it's easy to over-trade and get hit by the dealing fee, stamp duty and spread each time. I take your point that it should be a dispassionate assessment though without any emotional attachment to the stock.
Personally, for me the update isn't nearly bad enough to sell, although I only have a small position in Character (LON:CCT).
Anyone got any ideas why Victoria (LON:VCP) is up today?
Joe
Hi Paul
Bonmarche Holdings (LON:BON)
"... and I generally worry about the survival prospects for retailers who have not managed to crack selling online as well as in physical stores"
The detail in today's retail sales data for December (https://www.ons.gov.uk/businessindustryandtrade/retailindustry/bulletins/retailsales/dec2016) adds still more weight to this view and your previous commentary about the plight of the high-street. Small retailers of Textile, clothing and footwear stores had a 13.9% fall, whereas online for the same segment had a 13.9% increase.
I agree with the general view that online sales growth is very important to share values both in terms of bottom line earnings and especially the p/e multiplier (i.e. No online growth story equates to a low market rating). However, I wonder for Bonmarche Holdings (LON:BON) if there may be a case for suggesting that their target customer demographic (ladies of a certain age with an eye for value) might be less susceptible to online offerings both in terms of having less access and less interest in online goods preferring to see and feel goods before buying and maybe enjoying the high street shopping experience with friends to a quick snatch via a phone app. My gut feel is based on the mere observation of my teenage daughters' predilection for Boohoo.Com (LON:BOO) online compared to my elder sisters' enjoyment of a good Saturday afternoon high street rummage.
Best,
Gus.
Hi Paul and Graham. No worries if you have't got the time but I'd be grateful if you could have a look at software small cap Elecosoft (LON:ELCO). The trading statement mentioned pre-tax profit to be 'significantly' ahead of expectation. It's up 23% as I write. Thanks
I have held CCT since they were 55p through good and bad. Not one that I plan on selling. As I was waiting in traffic this morning I just started to wonder if they might make a juicy morsel for a US based predator. Probably not
Character (LON:CCT) I'm really not surprised, 2 directors were selling in December. I would be more confident if the directors were buying.
Good morning Graham, first i would just like to add that i think you and Paul do a superb job covering the small/medium caps and any other news of interest so much so that it has become a part of my daily ritual checking in. And has been so for the last 3 years so thumbs up from me. Also i rarely ask for a share that intrests me to be covered as im more then happy to DMOR however i would very much like to hear your (or other readers) take on SYNT Synthomer. Market cap around 1.4B so not a small cap and i understand if you do not want to cover it here. The company dropped a cracking statement this morning stating a 'significantly ahead' ptp beat of £120M. Market consensus was for around 98M so this looks quite good to me.
I have never traded SYNT as i always prefered ELM (similar company) but i have had it on a watchlist for years and today it makes a new high.
Kind regards
Damien.
Hi Damien,
Many thanks for the kind words, I'm glad you enjoy these reports!
Honestly, I haven't looked at SYNT before, so I'd be afraid to make a comment which would destroy value rather than add value.
But thanks for bringing it to me attention - I can put it on the list of stocks which I will need to study at some point (unfortunately, this list is rather long, but everything gets covered eventually).
Maybe someone else can offer thoughts here.
Regards
Graham