Small Cap Value Report (20 Jun) - SID, HHR, PURI, GTC, CRX

Good morning! It looks like a fairly nasty open is in the offing, with the FTSE 100 futures indicating a 100 point drop to 6,252, on the back of some comments made by Ben Bernanke in the USA last night, about tapering QE later this year.
Silverdell (LON:SID) has issued a positive-sounding contracts win announcement. They go on to say that, "of the £12.1m of contract wins, at least £2m is scheduled to fall in the current financial year". All well and good, but in the context of £136m forecast turnover for this year (ending 30 Sep 2013) that's not material, so I suspect this announcement contains a strong element of getting some positive PR out there, to re-build investor confidence after the damage done by an ill-conceived Edison research note a little while ago.
I'm also intrigued by the announcement today from Helphire (LON:HHR) which states that the Court has approved their capital restructuring, designed to allow them to resume the payment of dividends. A special dividend of 0.165p per share has been declared, which is just under a 4.9% one-off yield.
They also include positive news on a further reduction in debtor days (which is the bane of companies in this sector, supplying car hire to insurers) to 127 days. It's not a company I've been following, but on a closer look Helphire has pulled off a remarkable resurgence. They have wiped out almost all of their debt, through the issue of new shares at 2.5p, and amazingly the Banks doing a debt for equity swap, and writing off almost all of the remaining debt. So it now looks financially strong, and is profitable again.
I suspect there could be good upside on the current share price, although I loathe this sector with a passion, having lost around £250k on Accident Exchange shares a few years ago. For that reason I won't be tempted back into this sector by anything, no matter how good it looks on paper. Although one has to admire the skill of management at Helphire having so comprehensively turned around an apparently doomed company. On that basis alone they are possibly worth backing.
Management have a target of £7.5m operating profit for year ending 30 Jun 2013, so at a market cap of £53m, with net debt of only £1.1m, the shares could still be cheap? DYOR as usual of course, I don't hold any, but am tempted to have a dabble here at 3.4p per share, because there could well be a positive reaction to the results announcement in Sep 2013, when people see that the Balance Sheet is now actually very strong, with effectively no debt.

I changed my mind on Helphire, and decided to buy a few at the open, for 3.5p. It's funny how your feelings can change quite rapidly as you're digesting news & figures, but in the end I suddenly realised that it being debt-free, and having got debtor days down to only 4 months, and trading in line with expectations & resuming dividends, was all pretty good considering the market cap is only £53m.
Sorry if that sends contradictory messages, but that's just how it is with shares - especially at the market open the position is fluid, and people who are able to digest information quickly and accurately, and make quick decisions, can end up doing very well. I think that is particularly the case with profits warnings, where it's often the people who move quickly to sell at the open who escape with the least damage.
Whereas investors who pore over the detail, and worse still dither when the news is clearly bad, or even worse still who refuse to accept that the bull case was wrong & become emotionally attached to their shares despite bad news (we've all done it!), end up nursing greater losses. Such investors usually also defer selling, and end up selling right at the bottom some time later (been there, done that too!).
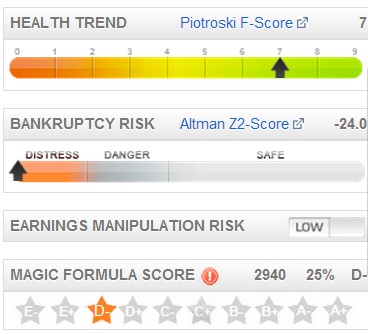
Shares in PuriCore (LON:PURI) have had a 10% boost this morning from a decent-sized contract win announcement. I like this one, and hold a few in the more speculative niche of my portfolio. It's risky though, and is showing a poor Altman Z-score, indicating potentially high risk of insolvency. I reviewed the accounts a while ago, and thought it looked reasonably OK, because they had converted their loan notes into shares, and done a Placing in Jan 2013. Therefore the poor Z-score is probably no longer relevant in this case, but it always pays to check the bank of 4 indicators on the StockReport (as shown in the picture on the right).
Getech (LON:GTC) has been on my watch list for a while, and I've taken the plunge this morning and bought a small amount at 57p. I like buying shares on days like today, when the market is heavily down, especially where that coincides with positive news from a company, as in this case. Getech have announced a "major data sale" which is only actually $962k, but this is a small company (market cap of £16.3m at 56p) and gross margins are very high. They sell exploration data to oil companies.
The beauty of buying on a down day, is that everyone else is hunkered down and not reacting to positive news announcements generally, so this means there is less competition, so it's easier to buy the quantity you want, at the price you want.
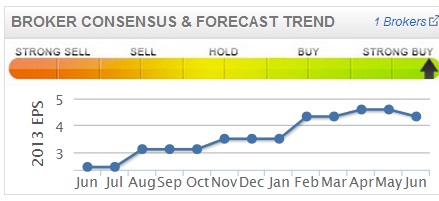
Note from the graphic on the left, how Getech has seen steady growth in broker consensus EPS forecasts for this year.
Since I've been following this indicator on Stockopedia, it seems to provide a very good pointer towards companies which might out-perform against forecasts. It generally points to companies which are on a roll in terms of underlying trading, and if they are also reasonably priced, then they could turn out to be good investments possibly?
So a steadily rising chart here indicates companies which are doing well, and hence seeing their earnings forecasts upgraded multiple times. Brokers will usually be fairly conservative in growing earnings situations, since they don't like anticipating sales growth beyond what has already been announced.
There is a positive trading update from Cyprotex (LON:CRX), a company that is new to me. They seem to be a specialist pharmaceuticals testing company, if that's the right terminology? Their H1 trading is ahead of market expectations, and with an H2 bias to their seasonality, total revenues of £9.5m, and operating profit of £0.8m are expected for the year. Top marks for a nice clear trading statement too, setting out the actual figures for what market expectations are - I wish all companies would do that. All too often it's a real struggle to interpret and unpick the meaning of trading statements, which is just wrong & results in misunderstandings.
Overall with a share price of 4.6p and 0.3p EPS expected for this year, the PER of 15.3 looks stretched to me, for such a small business. The trouble with things this small, is that they tend to be heavily reliant on a few large customers, so the risk of a profits warning is high. Also there is no dividend, so at a first glance it just doesn't appeal to me, despite solid current trading.
Right that's about it for today. I see that Gold is being massacred today, down $61 to $1290 at the time of writing. As I've always maintained, Gold is absolutely not a safe haven, it's actually a wild speculation. Of course fiat currencies will devalue over time, but at nothing like the rate that justified Gold rising multiples of its lows to anything like the current price. After all, it's just a shiny metal whose main use is decorative.
I did have a small flutter on some gold producers, but sold most of them first thing today, as my timing seems to have been excruciatingly bad. Anyway, no significant harm done.
See you same time tomorrow.
Regards, Paul.
(of the companies mentioned today Paul has long positions in: HHR, PURI, GTC, and no short positions)
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

17 comments
Paul,
Many thanks for the tips and suggestions,
K
Ah, good point - there aren't many numerical tickers in the UK but that's one - and we'll probably find more as we internationalise. We've added it to the bug list.
Don't know why it put in "Amundi" I didnt type it. Should be £500
I've always thought the use of the '£' symbol for turning tickers into links was a bit funny, especially on an investing site. Maybe they should use a different character.
Paul,
Unfortunately in PURI case its almost as bad as it looks. Iv'e used on-line and phone and for £.500, its 44.0p to buy and 41.0p sell. A real 7.1% spread. Coupled with the fact that their broker Cenkos doesn't make available earnings forecasts. The brokers are strangling this company to death for the average small investor. Hence an average of 1-2 small trades per day done on this share!
Compare that with IND. Similar Mkt Cap yet 1.5% real spread and 10+ trades daily.
I hear you Paul. although as a smaller less experienced investor using an online broker I actually find it quite disciplining however frustrating waiting for that right spread and dip in share price before pouncing!
Any ideas why Norcros (LON:NXR) is slow to catch up with its last results?
Hi Paul,
would you mind sharing who you use for a phone broker ? I've occasionally wondered whether I wouldn't get a better deal on some of these shares by having an account with one of these, what's the minimum sizes where it's worth using these ?
K
Hi K,
"Hi Paul,
would you mind sharing who you use for a phone broker ?"
Sure, I use W H Ireland as my main broker, as Richard Griffiths (0207-220-1682) there has done a lot of my broking for almost 10 years now, and I find him very efficient & helpful. Good price improvements on small caps usually. Their minimum fee is £50, which is expensive, but you get what you pay for. I find they usually more than recoup the fee in price improvement on small caps, and they add value in lots of other ways.
Also, you can get round the £50 minimum by opening a white label spread bet account with them, where the commission is only 0.25% with no minimum. So I put sub £5k trades on with them using spread bets, which is much more cost effective. A £4k trade would only cost £10 in commission that way, as opposed to £50 on ordinary account. But you get the same price improvement, as WHI source the stock cheaper, then put it into a spread bet wrapper - a fantastic product in my view. But obviously you have to manage the gearing carefully, or not use any gearing at all, you don't have to. No Stamp Duty either. But there is 3% p.a. funding cost, however, the divis normally cover that for the stuff I buy.
Their normal fees are much higher than 0.5%, so if you ring them, ask to be put onto Paul Scott's group tariff - a group of me & my mates all use the same broker, which is useful in other ways.
Obviously for larger caps, a discount online broker is more cost effective, so I tend to have a range of brokerage accounts, and use each one for where it's most suitable.
Cheers, Paul.
Hi,
Just another point re brokers - I've found that if you are holding quantities of micro/small caps that cannot readily be sold in one go, then I've found it highly advantageous to spread your holding over several brokers. The reason for this is that you can get locked in if something goes wrong.
I had a situation with Hargreave Hale a few years ago, several times, where I placed an order to sell and was curtly told that I would have to wait, as there were other clients in a queue in front of me. If the price is plunging because of a profits warning, and you need to get out quickly, that is no good at all.
Also the etiquette of brokers is that if they do one trade for you with a particular Market Maker, then if you come back the same day & want to sell more (which is generally considered bad form anyway), then your broker is obliged to go back to the same MM. He can then say no. So you again are restricted.
Hence why I've found it much better to spread a say £100k small cap holding equally between about 4 different brokers, so that if you need to sell, you can dump the stock through different brokers on the same day, with no restrictions.
I remember over 5 years ago, when I changed my mind on Volex, and decided to sell after a profits warning, my main broker at the time said they could only sell about £10k worth on the day. So I got the other brokers on the case (as I had spread the position across 4 brokers), one by one (so they are not fighting against each other & driving the price down fast), and dumped almost all of the stock in the one day. That would never have been possible if the whole position had been with one broker.
Cheers, Paul.
An absolutely ridiculous spread on PuriCore (LON:PURI) with this added volume, I don't know how they get away with it, and surely holding it back.
It's been around 400bps for months.
Hi it_trader,
Indeed the 40p/45p spread on PuriCore (LON:PURI) is absurd. But remember that's just the published spread. The real spread will usually be well inside that, but you need a telephone broker to sniff around for cheaper stock - I find that the 0.5% commission I pay to my telephone broker easily pays for itself (sometimes several times over) compared with a discount online broker, who can be tied to one Market Maker, which means whilst you might save on smaller deals (through them dealing via an RSP machine), you may not get the full range of market quotes.
Cheers, Paul.
Paul,
Being a shareholder in Helphire (LON:HHR), its pleasing to finally see reward for the faithful, do you see them as a takeover target as they now have very little debt and very strong cash flows, with an potential one off gain from the autofocus settlement.
May be Quindell Portfolio (LON:QPP) will buy them!!! ;)
Regards
Steamy
Helphire have improved around 6 fold since their lows in Sept 12 and just about achieved profitability. I suspect there may be some profit taking before the effect of even brilliant management re-asserts itself in the share price. Would be a good punt at 2p though.
Monty,
Whilst it is true that Helphire (LON:HHR) has 7-bagged from its lows 6 months ago, most of the shares in issue were issued this year at 2.5p in the refinancing. So at 3.5p the increase in price has not been particularly great for the bulk of the (new) shares.
Also the huge debt write-off added considerable value, so the shares should be a lot higher than they were. I tend to ignore all that, and just look at the value of the company now, and compare it with their profits & their balance sheet. HHR still seems good value on that basis.
Cheers, Paul.
I met the Helphire management team a few months back and was very impressed. Very different in both style and substance from the guys at QPP. They pulled off a real coup in getting the banks to write-off a massive chunk of debt without wiping out shareholders.
This is very much a turnaround play; stronger cash management, better cost control, a more conservative approach when accepting new business and the potential upside from an Autofocus settlement. Significant tax losses and lower interest charges will mean EBIT largely dropping straight through to EPS.
I'm not a great fan of the sector because it consumes cash and takes on more debt as the business expands. So the risks grow the more business you sign up. However, given the quality of management and the modest valuation there is significant upside to be had here.
Paul,
Much, much, much more exciting then Silverdell contract win is Puricores (PURI). This company is taking off. This is the second RNS annoucement in the last 2 months about a big new contract win. It really deserves a very close look as it is now certain to go into profit this year.
Hi mathewawood,
I have just written about PuriCore (LON:PURI) in the latest version of this morning's report.
I agree it looks potentially interesting, indeed I hold a few personally.
Cheers, Paul.