Small Cap Value Report (20 Sep) - TFW, TAN

Good morning! The FTSE 100 futures are indicating an open down 15 points to 6,608 this morning. The divergence between the main index, and small caps is becoming remarkable though. Check out the chart below, which shows that small caps (the beige line) began an astonishing bull run in Nov 2012, and that if it had kept pace with small caps in the last year, then the FTSE 100 would by now have reached 8,400! So that's a 27% out-performance by small caps vs large caps in the last year (the chart actually shows two years, but they were closely correlated until about a year ago).
So I suppose you could look at this two ways. Are small caps likely to continue out-performing, or are we now due a correction? In my opinion things are getting so frothy, a correction is both likely, and necessary, hence I continue to carefully top slice one or two of my positions, just to be on the safe side.

In a recovering economy, I do think one can be a bit more aggressive on growth assumptions, and hence be prepared to pay a little more in slightly higher PERs, but personally I won't go higher than about 13 for good quality businesses (adjusting them to net cash/debt neutral).
Another sign of a bull market is that IPOs are back with a vengeance, and are going to a premium apparently, although I've not really looked at any. IPOs don't generally interest me, as they are usually over-priced, why else would founders sell or accept dilution? London estate agents, Foxtons, is the latest, with a valuation of £649m at 230p a share - will be interesting to see that probably going to a premium too. I was a Foxtons tenant a few years ago, and they don't have a good reputation - in my experience tenants find them pushy, and landlords say they sit on the rents for months before paying them over. I would also worry about the need for Govt to act on excessive admin fees.
One of my favourite companies is FW Thorpe (LON:TFW), a family-controlled maker of lighting equipment. Their results for the year ended 30 Jun 2013 are issued today, and I like the chatty, but no nonsense style of the narrative. Not a great year for them though. Turnover is down 0.4% to £55.3m, although it remains a high margin business, with operating profit of £10.8 (down 9.3%), so that's a very healthy margin of 19.5% - indicating strong pricing power.
EPS dropped 3.8% to 8.16p. Note that there was a 10 for 1 share split from 19 Aug 2013, so the share price dropped by 90% when that was done, as the number of shares increased 10-fold. Losses within two subsidiaries, which have been named & shamed, and various other one-off factors mean that profits should rise again this year in my opinion, so I can see an argument for valuing the company on say 9-10p forecast EPS (although I can't find any published broker forecasts).
So at 115p these shares don't look expensive. Particularly when you take into account the amazing Balance Sheet. In fact, it's such a strong Balance Sheet, I have to show it to you - see below. If that doesn't give you a warm glow, I don't know what will!
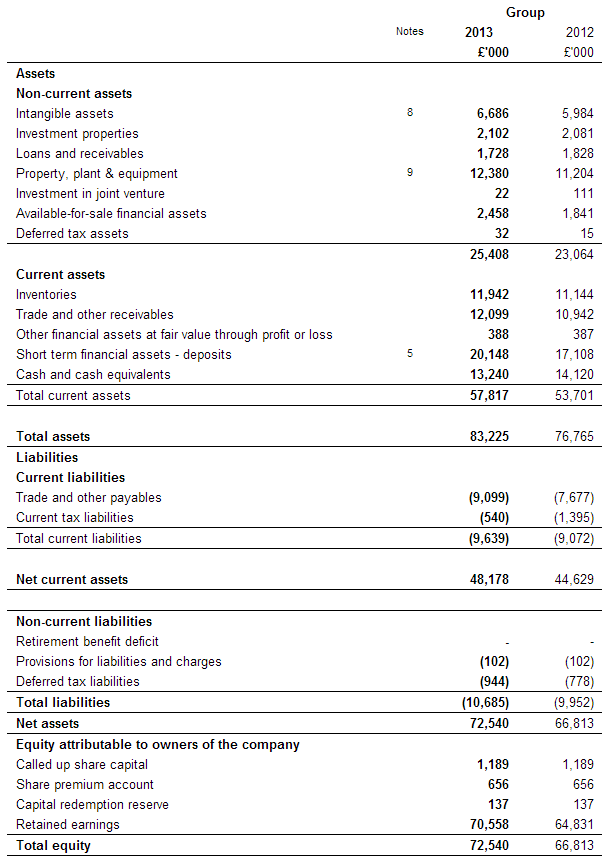
As you can see, Thorpe has net cash of £33.4m (being split into two lines, £20.1m shown as "Short term financial assets - deposits", and the balance of £13.2m as "Cash & cash equivalents"). That is 25% of the market cap, or 28.5p per share. Although one could argue that a company hoarding cash is not really doing a lot of good for shareholders - surely it would be better to put that cash pile to some use - i.e. value adding acquisitions, or just pay out the surplus element of the cash to shareholders as a special dividend.
With controlling family shareholdings, a share buyback would not be a good idea, as that will just make the shares even more illiquid, and there is already a punative bid/offer spread - they are currently priced at 112p Bid, 120p Offer, which is just ludicrous, and makes this uninvestable for me - pity, as I really like the business, Balance sheet, and management.
Tanfield (LON:TAN) has come up with an interesting solution to its ongoing woes - a staged disposal of their powered access division, involving a partner company refinancing it. Looks like quite a clever deal, with TAN having a Put Option to sell at an agreed price in future.
It will at least stop shareholders having to stump up more cash to fund the never-ending losses there. The market doesn't seem to like the deal though, perhaps because it's an admission of defeat, and takes away the upside? The shares are down 11% to 20p. I've never thought much of this company, and think they're on a hiding to nothing with their other division, an aging electric vehicles company.
I've not trawled up anything else of interest today, very quiet for news, as Fridays often are.
Even the laggards in my portfolio have started moving up strongly this week, so it really is a bull market! My stance remains - enjoy it whilst it lasts, but top slice or sell completely anything that is starting to look fully priced. There will be a pullback at some point, we just don't know when - and it's essential to have some dry powder to deploy on such a pullback, with some of the profits to date in the Bank.
As always, that's just one person's opinion, and readers may disagree - feel free to discuss in the comments below (there is a free registration option, but it's tucked away on the price plans page!).
Hope you enjoy the weekend, and see you back here at 8 a.m. on Monday.
Regards, Paul.
(of the companies mentioned today, Paul has no long or short positions)
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

4 comments
FW Thorpe:
Are we not getting a bit carried away by this "quality"share?.Yes, it has a fantastic balance sheet and high margins. But over the last five years its revenues have risen by just 6.8% and its operating profit by 2.7%. Over the last five years the shares have enjoyed a substantial re-rating, but at 125p the shares are trading on a historic p/e of 15.3 and a yield of 2.4%.
Could see very little in the chairman's statement to suggest that this company is about to be transformed into a growth stock.
FW Thorpe:
The issue I have is they are in an industry that has for the past 20 years been very boring, and thus not attracted much attention, or competition. However, with the LED revolution now in full swing, competition is continually increasing (esp. from China). I can't see how these operating margins/ROIC are sustainable. Where's there competitive advantage?
Re &TFW & a nice increase in the dividend, which Chairman says is to reinstate more in line with historic levels, presumably what they paid before the 44% cut in 07 according to StockReport. This and the statement below by the chairman about how they fared in the recession seems to indicate a fair degree of confidence in the future.
"I am often asked how we faired through the recession and I am pleased to be able to respond that your company has not really seen a recession apart from the "blip" in the spring of 2012. I proffer that the economic climate has, however, restricted growth."
Paul, I just took a look at FW Thorpe and am also impressed with the high operating margins and rock solid balance sheet. I also like the way the RNS does not seek to hide away the problem areas. This is a management team you can trust.
I was rather disappointed to see that Free Cash Flow runs someway behind post tax profits its counterpart in the P&L. FCF is £5.7m vs £9.5m for PAT. Spending on intangibles and CAPEX is running ahead of depreciation and amortisation £2.2m vs £3.9m - which partly explains the difference. Why a business like FW has intangibles relating to software and development I am not clear but the total now exceeds £6m in the balance sheet.
The balance sheet is if anything a little too strong. Returns on total assets and equity are fairly pedestrian as a result and I reckon I could probably get a better return on the "surplus assets" elsewhere. The problem is if you don't have a controlling investment you can't do a Warren Buffett and sweep up the surplus cash each year to reinvest elsewhere - you have to rely on management making the right capital allocation decisions instead. Anyway, at least the £30m of cash and the additional property backing allows you to sleep easy at night!