Small Cap Value Report (21 Aug) - DX., HEAD, SPSY

Morning folks,
I'm planning to look at Headlam (LON:HEAD), Spectra Systems (LON:SPSY) and DX (Group) (LON:DX.) today.
Graham
DX (Group) (LON:DX.)
- Share price: 8.65p (-9%)
- No. of shares: 200.5 million
- Market cap: £17 million
Resumption of trading in DX Shares
Lots of drama on the open here as this logistics/parcel distribution outfit finally returned to trading.
The shares had been suspended since March, leaving shareholders to chew over dribs and drabs of news from the company as it negotiated the terms of a potential reverse takeover with John Menzies.
In a July trading update, covered here, trading was reportedly in line with expectations, and the bank was supportive of the £19 million net debt position. The CEO and the CFO simultaneously stepped down from their positions after presiding over huge percentage declines in the share price.
That brings us up to last week, when the John Menzies deal fell through (link) over a failure to agree terms, leaving DX to work on its business transformation alone:
This approach has the support of both DX's major shareholder and its bankers, with discussions on new financing options for DX already underway.
The "major shareholder" in this case is Gatemore, who were previously shareholder activists in French Connection (LON:FCCN) (looks like they've sold up and moved on from that now).
"New financing options": does this mean an equity raise? Maybe the bank is supportive in the short-term, but needs DX to raise more capital for it to remain supportive? That's pure speculation on my part, but is how I'd interpret that paragraph.
With the takeover not happening, the shares are back trading. They plunged >30% on the open but are only c. 10% lower now.
Full-year results "will include the aborted costs of the Transaction and certain other expected non-recurring exceptional items, principally a non-cash goodwill impairment".
Lots of red ink then. More losses on the way.
I probably shouldn't spend any more time on this, because in my opinion this is uninvestable, and is only worth gambling money at this stage.
If you are Gatemore, you can at least get high-quality information from the Board and can negotiate on the terms of a refinancing. Small shareholders, on the other hand, have access to very limited information and won't have any say in the negotiation of a deal.
DX already had negative tangible assets and its intangibles are about to take another big hit. It's a crowded logistics market and while I've been reliably informed that DX's document delivery service, DX Exchange, is valuable, I can't see any good reason for private investors to put any more money into this.
Headlam (LON:HEAD)
- Share price: 575.25p
- No. of shares: 84.8 million
- Market cap: £488 million
My first time looking at this, "Europe's largest distributor of floorcoverings".
I like boring companies. They are the most exciting investments, sometimes. And this sounds pretty damn boring!
The results are pleasing - decent results in their own right, and explained in a very clear way.
For example, how many companies break down their operating leverage like this:
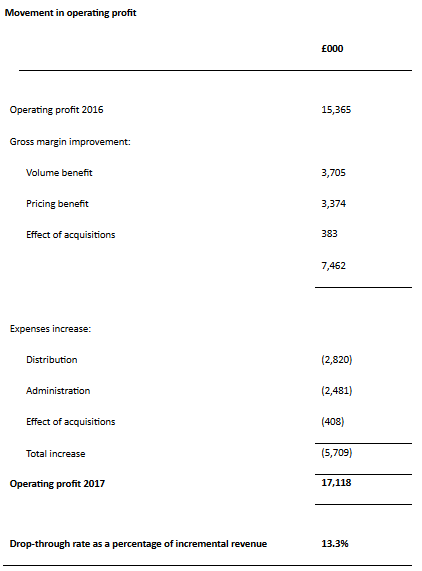
We can instantly see that volume was the biggest contributor to the gross profit increase, though pricing power also played a role.
Distribution costs didn't increase by as much as either of these effects, so total operating profit increased by 11.4%, or by 13.3% of the increase in revenue.
That's a handy statistic to have. Operating margin for Headlam is actually 5%, but was 13% of the revenue increase during this H1 period.
So to the extent it can make further gains in volume and pricing while controlling distribution and administration expenses in the manner it just did, those gains are highly valuable.
The improvement in gross margin during the period is attributed to "efficiency initiatives and more effective organisation and streamlining of the Company's businesses' practices". More of the same please!
I don't see any balance sheet issues: £72 million in gross cash and £50 million in net funds, after subtracting the value of the debt. There are large committed bank facilities, too. Such a large value of net funds probably means that the "fair" PE ratio should be reduced!
The interim dividend increases by 13% to 7.55p.
Trading is in line with expectations for the full year.
My opinion
I'm really impressed with this, so far.
The business model is simple: a big distribution network connecting floorcovering manufacturers with independent retailers/flooring contractors.
The dividend yield is 4.8% and I note that it has paid dividends every year since 1992!
Payouts have risen every year except for some significant cuts during the crash in 2009/2010.
And for the last two years running, it's been paying out big special dividends (rather than going on an expensive acquisition spree, as some companies would). Pretty much a dividend champion in my book, then!
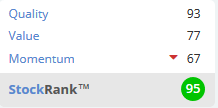
Stockopedia likes it too, and at a 14x PE ratio it seems to be offering a good deal to potential investors:
Spectra Systems (LON:SPSY)
- Share price: 91.5p (+22%)
- No. of shares: 45.4 million
- Market cap: £42 million
Trading update and interim results date
Another first time for me, Spectra makes products for authenticating high-value goods (banknotes, passports and others).
Spectra "is incorporated in, and its main country of operation is, the United States of America" - so we can have that old debate about investing in foreign stocks (albeit USA, i.e. developed market).
Strong update:
...trading in the current year has been strong. Unexpectedly high sales of our phosphour products along with a full year of higher margin in-house manufacturing have combined to produce a strong year todate.
As a result the Board now expects the Company to significantly exceed market expectations for PBTA and cash flow for the full year ending 31 December 2017.
Checking the annual report, I see that it started manufacturing "covert materials" for a G7 central bank in-house. Gross profits rose 35% as a result.
PBTA means Profit before Tax and Amortisation (Amortisation has been a large entry in Spectra's accounts).It recently paid its maiden dividend, having been listed since 2011.
The stock has multi-bagged this year as investors figured out performance was improving.
Despite the surge that's taken place in the share price already, this looks like one of those that could just run and run. Phosphour sales were up 211% in 2016, which was approximately half due to an acquisition and half due to a "new sales channel".
It's all rather mysterious.
I note that Spectra itself doesn't seem to know for sure who its end customers are. From the 2016 report, its important near term opportunities were said to include:
The continued sale of our specialty phosphour materials to a security thread manufacturer providing product to what we believe is a large Asian central bankHow interesting! I guess there are other industries where you don't know where your products wind up in the end, but not quite like this!
Since it doesn't know who its end-customers are, it also doesn't really know how long the demand will remain high:
Although we cannot be assured of the continued sales levels of the phosphour materials, we are confident that our proven ability to deliver large quantities of material in 2016 to a new customer will have lasting value which will translate into sustainable increases in our sales of these materials.
Seems likely to be worth a punt, but difficult to verify its claims and customers for yourself. Difficult to verify its products, too!
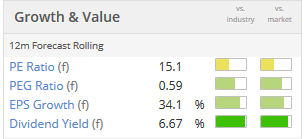
The valuation looks potentially attractive for a niche business with growth opportunities. It also has $8.8 million in cash and no debt.
Before today's share price rise, the value numbers were as follows:
I think that's it from me today.
Paul should be back tomorrow!
Graham
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

29 comments
Yes but its top secret.
Spectra Systems (LON:SPSY) I notice was up 11% yesterday, I can't see any news. I also have various cyber security type shares on a watchlist as follows: Defenx (LON:DFX), ECSC (LON:ECSC), Falanx (LON:FLX), all have gone up today by 6-10%, does anyone know why?
Hi Herbie
I was just following the Stockopedia's commentary trail for Spectra Systems (LON:SPSY) and had a second look at your cyber security watch list (above).
I'm sure you have noticed that Spectra Systems (LON:SPSY) is up again today (05/09/17) (+9.6% at time of typing), and Falanx (LON:FLX) is also up (+16.8% at time of typing).
I'm interested in both, not too sure about Defenx (LON:DFX) and not at all keen on ECSC (LON:ECSC) at present.
Has your interest developed further on these since your posting (21/08/17)?
Regards
Howard
I was still considering Spectra Systems (LON:SPSY) and of course the intermins are out today which look good and shares are up 10%, there were a few negatives raised in post 12 above. Falanx (LON:FLX) I had not seen, operation statement out today which also reads well. I agree at the moment it is between these 2, I feel it's an area I want to invest in as it will be a growing sector.
Hi Herbie
Thanks for the response.
I am currently digging into the people behind Spectra Systems (LON:SPSY).
Based on website list (22/09/16). Six major shareholders http://ir.spsy.com/drupal/?q=node/4
Board seems to have some rather illustrious people http://ir.spsy.com/drupal/?q=node/10
My interest is certainly pricked.
As an SP commentator, on a previous thread I looked at, noted the spread on HL is almost 2.9% so a bit steep, but not too off putting for me.
I'm going to watch this one for a bit but I'm quite interested I must say. But, wary all the same.
I'll look at Falanx (LON:FLX) in more detail as well.
Regards
Howard
Hi Herbie
Have you noticed the RSN for Falanx (LON:FLX) today?
And the resultant share price rise &%+ at time of typing.
http://www.stockopedia.com/share-prices/falanx-LON:FLX/news/rns/170911flx3009q.htm/?title=acquisition-and-appointment-of-cto
I bought a small holding. Having read up on Falanx (LON:FLX) I can see some potentials developing. I recognise its a Sucker Stock at present and it is a long way below my normal Mkt Cap. I shall see.
I'll keep looking into Spectra Systems (LON:SPSY) as well as per your original cyber security themed list. Thanks for posting such lists of yours up, I always have a look at your ideas.
Regards
Howard
Howard, thanks for your comments. No I had not seen that, thanks. I did not buy any, they are a bit small at £10m market cap. The acquisition is very small but is interesting about Mr. Morrell, if what they say is true.
I did take a small holding with Spectra Systems (LON:SPSY).
HI Herbie
Yes £10m usually too small for me and why would Mr Morrell cause a price lift?
I listened to their webcast interviewing him (about 20 mins). It's obviously a supportive perspective but it does add some context to what Falanx (LON:FLX) is purporting to be offering.
I found it to be quite informative, you might like to listen.
https://falanx.com/directors-talk-interview-richard-morrell/
All that said, I have heard similar views many times over the years in the IT/Tech sector, so I am cautious and sceptical but also cognisant of the notion that cyber risks are increasing rapidly but protections are not keeping apace.
Further, that cyber risks apply equally across the spectrum to any actors (people/organisations) or agents (devices) that access the net. Yet, most of these actors/agents have little idea of what is protecting them and to what degree they are protected.
If Falanx (LON:FLX) are indeed able to create an offering accessible by the smaller actors/agents as this webcast claims. Then I think there could be potential here.
I will watch with interest, but still with only a small holding and a flag to myself that this is a 'story stock' not a quants-based holding.
Regards
Howard
Howard,
Thanks for that link to Directors Talk, sounds quite good but I'm no expect in that field. Yes one to watch.
Hi Herbie
I don't know if you progressed with Falanx (LON:FLX) but if you did, this might interest you.
Falanx Group Ltd (LON:FLX) Coverage Initiated at Beaufort Securities
https://stocknewstimes.com/2017/10/22/falanx-group-ltd-flx-coverage-initiated-at-beaufort-securities.html
This is one of their paragraphs ....
Beaufort Securities initiated coverage on shares of Falanx Group Ltd (LON:FLX) in a research note released on Friday, October 13th. The brokerage issued a speculative buy rating and a GBX 12 ($0.16) price target on the stock.
They are putting a price target of 12 (it's 7.5 at time of writing this note).
I have a small holding. First buy was 7.26, then 7.67 then 8.46. Nervously watching it though. It looks like the 50MA is now going to go above 200MA, so it might just be gaining traction.
Just thought you might be interested as I know you looked at it n the past.
Regards
Howard
Hi Howard,
Thanks for the info. of Falanx (LON:FLX).
No I did not buy any Falanx (LON:FLX) in the end, decided they were a bit too small for me at the moment. I did buy a small holding in Spectra Systems (LON:SPSY), but sold out at 92p, despite a good trading update the price has fallen more, I don't really understand why so I will leave for now.
I just took a look at Headlams website to see what theyre about, could see nothing about the product or anything customer focused its entirely about investor relations.
It looks like they operate under 60 different brand names, but after over 10 mins of searching I havent found a single one
I'm a little uncomfortable with a company which is so investor focused instead of customer focused, reminds me of 'mission marketing'
I think that's because 'Headlam' is the holding company rather than a floor-covering brand that their customers would recognise.
There's a company directory link on the Headlam website that reveals all of the subsidiary companies, each with it's own customer facing website:
http://www.headlam.com/company...
I agree it's strange. If you Google "Headlam group subsidiaries" you get a long list though.
Their customers are the independent flooring retailers. I.e. The specialist shop in your town where you get traditional service typically. Those customers are used to dealing direct with a local wholesale distributor of floor coverings. So, as Headlam (LON:HEAD) have expanded by acquisitions and consolidating this wholesale distributor channel they have generally made the decision to preserve the local distributors brand name and identity and personalised service. So, they are aiming to achieve a customer relationship that blends the best of the local personal service from a respected local/regional distributor and brand with the purchasing, warehousing, and stock management efficiency of a national corporate.
In other words they do not want to be Headlam to their customers generally. They want to be A.N.Other & Son family floor coverings distributor. Thus their corporate website is deliberately not a customer website as such.
But if you click on the "Company Businesses Directory" tab on their website you can see all the local brands that they trade under, who have their own website.
Graham makes the point on Headlam that with
"£50 million in net funds, after subtracting the value of the debt. There are large committed bank facilities, too. Such a large value of net funds probably means that the "fair" PE ratio should be reduced!
The cash swings for Retailers can be significant, both intra-month and across the year..and many Retailers are canny enough to choose a Year-End Date at a point in the yearly cycle where cash looks strongest! I have recently read a Broker Note on Headlam which suggested the average cash balance across the year is closer to zero.
Cheers alan, yes, that could be the case. At least the ordinary & special divis give some comfort that surplus cash is being generated over and above what they strictly need for operations.
Spectra Systems (LON:SPSY) CEO takes excessive pay. $502k (£390k) last FY. Pre-tax was £840k after years of losses. Also a history of overoptimism.
There's hasn't been an AGM in 6 (IIRC) years - always postponed due to lack of quorum.
Uninvestable for me.
A bit more Spectra background information here:
http://www.pci-mag.com/contractors/brand-protection-and-anti-counterfeiting/spectra-systems-corporation/
Re DX (Group) (LON:DX.) the west London solicitors who handle business matters for me will no longer accept documents from DX from next month. If enough other solicitors do the same, the network effect will be lost to DX.
Hi, can you tell us why the solicitors have changed their policy?
I don't know, Graham, sorry. I noticed it in their standard email footer in an email I received last week. I'll let you know if I find out more.
Ten years ago virtually all lawyers used DX. They had a network of deposit locations and you would send someone down to empty your incoming box and drop things off in the outgoing. The locations in central London had a constant stream of people walking between law firms and the DX with boxes of stuff on trolleys - probably 90% of correspondence between solicitors went via DX. Postage costs were a significant overhead and the DX was cheaper than the post.
Now we all use e-mail, electronic datasites, memory sticks etc and my yearly post bag now is probably about the same size as my daily post bag ten years ago. Lawyers just don't need the DX any more in the same way that they used to. DX have tried to develop their services but there are lots of alternatives and the competition is consistently developing as well. I also doubt that they are well served by a legal services industry that is consolidating and is itself under pricing pressure.
I've not looked at their accounts or what DX say about themselves, but the above is based on my experience as a lawyer for the last 15 or so years.
I would be interested in any views on Frontier Developments (LON:FDEV). They are a video game developer and publisher that is up 15% today on an RNS announcement of a new game based on Jurassic Park to launch next year. Tencent took a 9% stake in them at the end of July.
I hold, and video games and e-sports is an area I am looking to add to.
I still own a few DX [groan].All that I will say is that it would be nice if Stocko could get their information feed working on this one,given that I have paid my sub.
Graham: here's an explanation of the two share classes that I found on ADVFN
Spectra Systems Corporation has two lines of Common Shares which trade on AIM, Restricted (SPSC) and Unrestricted (SPSY), and the aggregate market capitalisation of the Company is £9.89 million. these shares are now common stock available to trade. Only 691k left so another part of the tidy up will soon be completed.It has no bearing on the m'cap of SPSY as far as i'm aware. Here's an old piece of news.
Shares Not in Public Hands In the terms of the AIM Rules published February 2010 and insofar as it is aware, at 10 December 2013, 12.69% of the Company’s AIM securities were not in public hands. Restrictions on Transfer of AIM Securities 4,640,894 Ordinary Shares (AIM:SPSC) trade with the following restriction: The newly issued common shares, $.01 par value per share, of the Company ("Common Shares") which were issued pursuant to an exemption from registration under Regulation S promulgated under the US Securities Act of 1933 (the "US Securities Act") and certain previously issued Common Shares which were issued pursuant to an alternative exemption from registration promulgated under the US Securities Act are restricted securities as defined in Rule 144 of the US Securities Act and may not be offered, sold or otherwise transferred except pursuant to an effective registration statement or pursuant to an exemption from, or in a transaction not subject to, the registration requirements of the US Securities Act. The remaining 40,610,476 Ordinary Shares (AIM:SPSY) trade without transfer restrictions.
If you can make sense of that, I'd be grateful. It appears that the "restriction" doesn't interfere with free trading of Spectra Systems (LON:SPSC) on Aim, but makes the SPSC price lower and the yield a couple of percent higher than SPSY.
Hi FREng, it's a US company so I'm guessing they felt the need to issue some US-registered shares for whatever reason at some point in the past. And that leaves them having to deal with the US legal system for these shares.
There aren't too many of them outstanding so I'm not too worried about them.
Cheers
Graham
Solid results from Headlam. A well managed business, albeit cyclical. Will be interested in your views Graham.
Graham
When you look at Spectra Systems (LON:SPSY) please also consider the "restricted" version of the same stock Spectra Systems (LON:SPSC) . Same dividend, it seems. Lower price. Dreadful spread ...