Small Cap Value Report (21 Jul 2017 - Part 1) - LTG, EMR, KOOV, MIDW, PAYS

Good morning! Graham here.
Edit 1: Change of plan, as Paul is also writing a Part 2 report at this link!
Edit 2: This is the finalised list of stocks covered here in this report:
- Learning Technologies (LON:LTG)
- Empresaria (LON:EMR)
- Midwich (LON:MIDW)
- Koovs (LON:KOOV)
- Paysafe (LON:PAYS)
Cheers!
Graham
Learning Technologies (LON:LTG)
- Share price: 48.9p (+8%)
- No. of shares: 568.4 million
- Market cap: £278 million
A detailed trading update from this e-learning business, growing via acquisition.
It's an update for the half-year ending June 2017.
The Board is pleased to report that LTG has made excellent progress over the period delivering on its strategic ambition of building an international business with annualised revenues in excess of £50 million and strong operating margins. The Board expects the Group to achieve record revenues of not less than £20.8 million for the first half compared to £12.8 million in the first half of 2016, an increase of 62.5%.
That's interesting - the strategic plan is to shoot for a specific revenue target? I generally prefer to see objectives stated in terms of returns on capital, and I'd wonder about how the £50 million target was specifically chosen. I suppose the combo objective of revenue and strong margins is not a terrible substitute in theory (depends how strong the margins are).
The release includes a long paragraph about progress with the NetDimensions Holdings (LON:NETD) acquisition, which is going according to plan.
We also read there is strong organic growth in the group's other businesses and the period-end order book is at record levels.
Overall, it's a difficult picture to understand as there are a lot of different parts to it, as you'd expect with a company growing by acquisition.
The shares have risen so presumably the numbers are better than expected, but the update didn't actually confirm whether or not overall performance was in line with management or analyst expectations.
My opinion: I'm going to sound like a broken clock, and those of you who are long will not appreciate me saying it, but acquisitive growth strategies turn me off.
I wish LTG every success. It's simply too complicated and difficult for me, without devoting a very considerable amount of time to it.
There is a lot of contract-driven work, and net debt including defcon is now £10 million. The StockRank is also just 14 and it qualifies for James Montier's "Unholy Trinity" short-selling screen. I'm not feeling motivated to look into it any further!
Empresaria (LON:EMR)
- Share price: 154.5p (+5.5%)
- No. of shares: 49 million
- Market cap: £76 million
I've covered this UK & Int'l recruiter twice so far this year, when the share price was at 122p (January) and 148p (March), and written favourably about it both times, so I should have listened to myself and thought about buying a few!
It's a solid mid-size recruiter and tends to be rated (by PER) about half-way between the tiddlers and the giant recruitment companies.
That's still the case today, the PER about 10x:
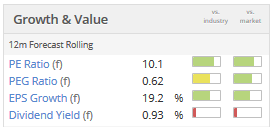
This trading update reads well but the share price arguably should have stayed where it was (if markets were efficient!), since performance is merely in line with expectations:
Empresaria has delivered a record first half performance, with net fee income up approximately 26% on the comparable H1 2016 period, with the strongest trading in the UK, Continental Europe and Asia Pacific regions. As such, the Board confirms that the Group remains on course to meet market expectations for the full year.
This is another business which is has allowed debt to increase (about £10 million at the annual results) as it has made investments into other, pre-existing recruitment businesses.
Again there is some personal bias at work here, but the recruitment industry in my opinion is somewhat predictable - yes, it rises and falls with the economy, but a well-run recruiter should continue to make money in good times and bad. Under-achieving consultants can be let go, and there is rarely a reliance on a single large customer.
So I'm a lot more comfortable taking risk in this industry, and wouldn't mind owning some Empresaria (LON:EMR), even after the share price rise this year.
Koovs (LON:KOOV)
- Share price: 39.75p (+4.3%)
- No. of shares: 175.4 million
- Market cap: £70 million
This Indian online fashion retailer is raising more funds.
Paul has covered this at some length before, writing about how it's inability to generate self-funding growth led to serious dilution for investors.
The share count was only about 24 million back in 2013.
This update is a significant capital raise. The plan is for £19 million in convertible loan notes, to be "primarily" used for more marketing of the brand.
The loans will fall due in two years and are convertible at a share price of 40p. Interest rate is LIBOR + 6%, which I guess is high yield in current conditions. They can be converted to shares at any time.
For existing shareholders, worst case scenario is that the loans can't be refinanced or repaid in two years. Best case scenario is that the company performs well and the loans are converted to shares at 40p.
By my reckoning, that would be an extra 47 million shares. So the loan note holders could own more than 20% of the company.
Koovs highlights that it is now making positive gross margins but since that is the most basic test of whether a company such as this might have a decent business model, I'm afraid I wouldn't be getting excited yet!
Midwich (LON:MIDW)
- Share price: 388.5p (+19%)
- No. of shares: 79 million
- Market cap: £308 million
This is a distributor in products for the audio-visual and documents markets - TVs, cameras, printers, projectors, etc. The very impressive list of brands it works with can be viewed here (new tab).
Results for the full year are anticipated to be comfortably ahead of prior expectations, thanks a very strong first half to June and continued H2 momentum so far.
The Group has traded well in the first half, seeing good top line growth across all of its geographies on a constant currency basis helped further by the continued weakness of Sterling. This underlying revenue growth has been delivered whilst maintaining overall gross margins in line with those reported for 2016.
So it's not just a fluke based on Sterling weakness, the underlying growth is good too.
And the Sterling weakness is just a bonus (perhaps a temporary one) on top.
I wrote positively about Midwich the one other time I've covered it. It's still fairly new to the market, having listed in May 2016.
But it seems to be worth of increased investor trust as it builds its dividend track record and a history of meeting and exceeding forecasts.
See how the earnings forecasts for 2017 have improved over the past year:
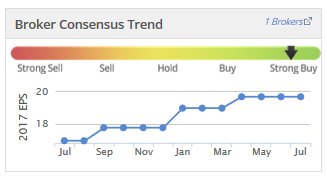
The PE ratio is not too bad, at 16x, for a company that is growing and has successfully executed a £20 million acquisition.
So it's one to watch, I think.
Paysafe (LON:PAYS)
- Share price: 579p (+7%)
- No. of shares: 485 million
- Market cap: 2,800 million
Statement regarding possible offer
Acquisition of Merchants Choice Payment Solutions
By request, I'm covering this big-cap payments processor.
It lived on AIM until moving to the main market in 2015.
Today brings a double barrel of announcements including this possible offer from private equity funds Blackstone and CVC:
Under the terms of the Possible Offer, the ordinary shareholders of Paysafe would receive 590 pence in cash per ordinary share in Paysafe. The terms of the Possible Offer represent a premium of approximately 34% to the volume weighted average price for the six month period ended 30 June 2017, the day prior to broad sector consolidation speculation.
There is no objective answer to what a "fair" premium is. From my point of view, it's ok to use the period before merger speculation begins.
But why not also use the endpoint of that period? On 30 June, the share price looks around 511p to me. The offer is only a 15% premium to that level.
Old Mutual are happy to accept the offer and have 10% of shares.
It must be emphasised that the offer is still not yet firm. According to stock market rules, it must be firmed up by 18 August or else the bidders must pull out.
Separately, Paysafe has announced it is paying $470 million for a Texas-based payments processor. Most of the funding is from its debt facility.
The target is already heavily linked to one of Paysafe's subsidiaries, so there will be a lot of inter-company transactions to be consolidated in the new accounts.
My opinion
On the offer, I would have thought that a 20%+ premium to the end-June SP was more appropriate. With Old Mutual signalling support for it, I don't know if the other investors will have the clout to get it raised.
On the Texas acquisition, I wonder whether it's in line with the strategy which the bidders would favour? I presume it must be, as the Paysafe team seem to be receptive to getting an offer.
The rating on the acquisition is 24x pre-tax income, as you'd expect in current conditions.
I'd be slowly and carefully cashing in my chips if I was involved here.
That's all for today.
Don't forget to read Paul's report too and have a good weekend!
Best wishes
Graham
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

20 comments
Paysafe (PAYS): I regard 590p as a very low-ball offer. The payments sector is hot at the moment and with the US online gambling market on the verge of opening up Paysafe is a very attractive potential player. the offer for Paysafe is at x15 forward earnings, whereas Worldpay are being taken out at x30 forward earnings and a mature business with no US exposure.
The attraction is that with a Private Equity owner the Management Team get a pay-day, get to keep their jobs and probably a highly attractive incentive scheme to realize the company's full potential - when it eventually comes back to the market loaded with debt finance.
I'm a holder and staying in, I'll be very surprised if Blackstone and crew manage to get Paysafe at this price.
Thank you for your expert comments on Paysafe (LON:PAYS) (when I asked for them in an earlier question I incorrectly put in PayPoint (LON:PAY) but I am sure you picked up the mistake!)
I am a little surprised that you did not comment on the fact that the bidders would require the sell off of so called non core assets before the takeover; that they were planning to use part/all of the funds released from that sell off to finance the takeover; that there was no comment from the Board of Directors on whether they were recommending the offer or not (something that is quite unusual?). If you can find time to comment further, I and no doubt Julianh would be grateful. Thanks in anticipation.
I’m not a holder of Learning Technologies (LON:LTG), but not for the first time I think the StockRanks are failing to accurately reflect the business here.
LTG came to market by reversing into a cash shell called In-Deed Online plc in November 2013. If you look at the Stockopedia page for Learning Technologies (LON:LTG) you can see the 2012 results listed there reflect the trading results of In-Deed Online, and not the actual LTG operating businesses.
The 2012 results of that unrelated business showed an operating margin of negative 8,519% and ROCE of negative 47%, whereas the actual 2012 results for LTG (then known as Epic) showed an operating margin of 8% and a ROCE of 39% (both figures positive).
For the 2013 results, the Stockopedia page is showing the trading results for the correct company, but the loss for that year reflects the costs of listing and the reverse takeover, amounting to £2.1m. Strip those out and a loss of £1.1m turns into a profit of about £1m, the operating margin improves from negative 12.3% to positive 14.9%, and ROCE improves from negative 62.7% to positive 75%
You might wonder why the results from 2012 and 2013 are relevant to today’s StockRank, but the Quality score uses 5-year averages for operating margins and ROCE so in my view two out of those 5 years are based on information which is either misleading or plain wrong:
Adjusting for the 2012 and 2013 results in those 5-year averages, I reckon the Quality score should be assuming a ROCE of +24% not negative 31.5%, and the 5-year average operating margin should be +5.6% not negative 1,654%.
Furthermore, because LTG doesn't report a gross profit line in its income statement, both the Piotroski score and the 'gross profits to assets' ratio in the Quality score appear to assume this means gross profit is actually zero, with the stock being downgraded accordingly.
I have no idea what impact all of this has on the overall Quality score, other than to suggest that the ‘true’ score is probably a lot higher than the reported score of 27.
Bestace - fantastic post - thank you.
Sorry, I gave Paul the credit for the write-up... it's Friday (zzz).... thanks GRAHAM!
Have a nice weekend all.
No worries andrea. Thanks very much for the comment!
Graham
Love your comment on Efficient Market Theory lol
Haha, thanks
Heaven forbid that markets become efficient or investors become rational. I would be a lot poorer.
But if anyone wants to believe in that stuff, please carry on!
I know its outside of your market cap limit Graham but any chance of a comment on punter fave Paysafe.
Cheers
Thanks for the write-up on LTG Paul, some really good points made. I looked at the accounts for the last finals, and there's an awful lot of "acquisition related deferred consideration and earn-outs" and the liabilities, especially long-term, have ballooned - perhaps one would expect all of this with an acquisition-led strategy. I'm tempted to watch, and maybe dabble with only a tiny position only when the price settles.
However, a strategy that I have started to increasingly apply to my investments is that I watch what happens to the share price of a company on the day of a trading/results announcement AND on the day after that, and I only buy if it is up on both days - I looked at EGS yesterday and was left undecided... and today the price is currently down 3%, due to profit-taking I guess, and so I won't be investing at the present time. I realise that this strategy won't always work and I also miss out on a bit of the price rise, but for companies with good momentum it seems like a safer investment criteria and can avoid short-term hysteria driven by market makers.
Hi Graham - Re Learning Technologies (LON:LTG) A quick glance at broker revenues forecast says £49.2m for the full year . So a £20.8m half year performance is not particularly exciting.
Overall I agree with you. Why the SP is up 9% beats me. I must be missing something.
I echo JulianH's question on PayPoint (LON:PAY).
Since Paul has commented on this in the past (2014), I have asked him for similar comment via the link given above. However I would be interested in your thoughts too. So here is broadly what I put on the Paul link today.
PayPoint (LON:PAY). I know they are probably way over your size limit now, but Paul's interest and insight in the past (2014) into this in some ways strange and controversial company make them interesting!
Today we have an acquisition AND a bid! The bid is complicated and I dont see any reference to the Board of Directors recommending it. One largish shareholder - Old Mutual with 10% - wants out, but nothing more than that. The only other largish shareholder on the website (Fidelity - again around 10%) makes no comment.
Your comments would be very much appreciated on the content of the bid and the exact timing juxtapoisition of the acquisition and the bid.
I think you may be referring to Paysafe (LON:PAYS) Paysafe here
Yes I am off course referring to Paysafe (LON:PAYS). A non-deliberate error, and thank you for pointing it out.
i too would like to here your points on pay safe paul [ i own shares in this company] but wonder if it could attract another bid from another foreign investor. thanks
The update from LTG looks really good to me Paul, so will look forward to your comments on them - you covered them in April and suggested they looked interesting at 46ish pence, and after today's rise the price is not much beyond that. Slightly summarised commentary:
...LTG has made excellent progress over the period delivering on its strategic ambition of building an international business with annualised revenues in excess of £50 million and strong operating margins. The Board expects the Group to achieve record revenues of not less than £20.8 million for the first half compared to £12.8 million in the first half of 2016, an increase of 62.5%.....
...the integration of NetDimensions... has been successfully completed on time. The transformation program will continue during the second half of 2017, with the full-year synergies and settled cost base being realised from the beginning of 2018 as planned. NetDimensions' customer support teams have been relocated to the geographical territories that they serve, hosting services are being migrated to our centre of excellence in Nashville, and we are investing in our core technology team headquartered in Hong Kong....
The strategic progress in the first half of the year has been underpinned by strong organic growth in LTG's other businesses and our period end order book is at record levels, demonstrating excellent momentum as we enter the traditionally stronger second half.
LEO, the Group's comprehensive solutions provider, has achieved 50% growth in sales compared with the first half of 2016 and built a strong sales pipeline for the second half of the year. The Civil Service Learning contract, being delivered alongside our strategic partner KPMG UK LLP, is progressing well and in line with expectations.
Preloaded, our 'games with purpose' division has performed very well... and Eukleia is seeing an increase in demand with the introduction of MiFID II regulations.
Our software licence businesses are performing strongly; gomo has won a number of key enterprise contracts with its industry leading cloud-based multi-device authoring tool whilst Rustici has continued to expand its recurring licence business at a pace beyond our expectations...
...the Group continues to build recurring revenues and to diversify our business outside of the UK.
LTG continues to drive strong operating cash flows. At 30 June 2017 gross cash was £11.5 million (31 December 2016: £5.3 million) and net debt was £6.1 million (31 December 2016: £8.5 million). After adjusting for funds due to remaining NetDimensions' shareholders and net payments due as a result of the exercise of share options just prior to the end of the period, adjusted net debt was £9.8 million at 30 June 2017.
Good morning Graham
Any thoughts on the takeover bid for Paysafe (PAYS)? The premium to yesterday's share price is less than 10% which strikes me as much too low for a high growth company on a forward p/e of 14.4 and a PEG of 0.67. Having said which, the market has always assigned a low p/e to Paysafe maybe because of the regulatory risks.
Thanks
Julian
Hi Julian,
I've thrown in my tuppence worth.
Best wishes
Graham
Hi Graham, check your email!! lol