Small Cap Value Report (21 May 2015) - AVAP, TUNG

Good morning!
I had a terrific day yesterday at the London Value Investor Conference. There was some difficulty in getting there, due to emergency repairs required to faulty signals in the Haywards Heath area.
So unfortunately, I missed the Charles Brandes presentation, but did arrive five minutes before the bell was rung for lunch, so I was first in the queue for a delicious roasted salmon in tomato sauce, with mixed vegetables, and spinach, tomato, and mozarella. Smashing! The venue this year was the QE Centre, opposite Westminster Cathedral, which was a very good location. The only niggle was the squeaky chairs - so every time any of the several hundred value investors adjusted their bottom, a loud squeak was emitted by their chair.
Going to LVIC each year is almost like a pilgrimage for me, having my value battery charged up again with the core concepts which work best, after a year of being confused by background noise & other competing, but inferior ideologies, such as momentum, etc.
I've taken about 19 pages of A4 notes, so have at least two good articles currently gestating. In particular, the Neil Woodford session was interesting, although the interviewer liked the sound of his own voice a bit too much - isn't that annoying, when an interviewer has a great interviewee in front of them, that everyone is dying to hear from, but the interviewer won't shut up?!
Just a quick review of a couple of RNSs, as I stumbled back to Islington last night, so have to catch the train back to Hove shortly, and pick up the Jag from the repair shop - it will be nice to be mobile again. She developed a misfire, so new coils were required.
Avation (LON:AVAP)
Credit rating - this aircraft leasing company has recently issued bonds at a 7.5% coupon. I queried this with their CFO, querying why they were paying such an apparently high funding cost. He replied that the new bond financing is in lieu of equity, so it only funds the c.10-15% equity element of the purchase price for new aircraft, leaving the bulk of the cost to be financed through much cheaper bank lending, c.4-5%.
This company is expanding at a rapid pace, and is run by experienced management, who know the sector well, and the inherent pitfalls. So quite an interesting company, in my view. Although it's not one I would want to be holding when the next recession bites.
S&P has given their bonds a B rating, stable outlook. I don't know anything about bonds, so don't know whether that is good or bad. Any readers expert in this area, and willing to comment?
Tungsten (LON:TUNG)
Market update - the company updates the market today on its funding crisis:
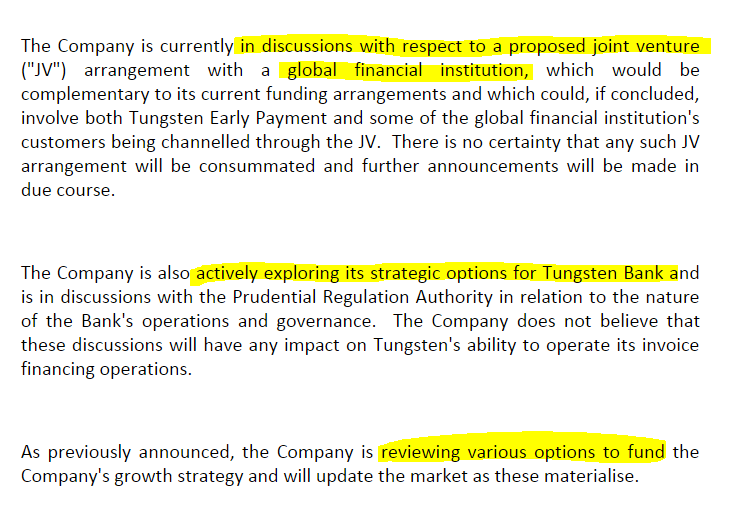
My opinion - I can't believe what a dog's breakfast Edi Truell has made of this. He ramped it to high heaven last year, throwing around impressive-sounding claims about hundreds of billions, even trillions, but made the schoolboy error of not raising enough cash to execute the highly cash burning business model.
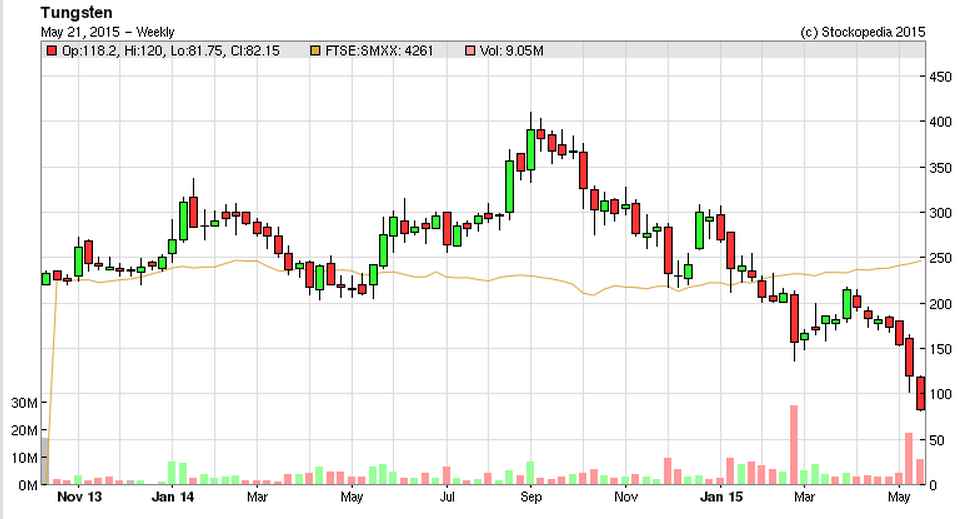
So it's now become a shorter's paradise, as the company has admitted it needs to raise fresh cash for operating purposes. The shares are in freefall, as you can see from the chart below.
I'm sure Truell will pull something out of the hat, but wonder what proportion of the solution will be owned by existing shareholders?
Interestingly, this share is a good example of how management making large share purchases immediately after bad news, is actually an increasingly bearish signal. They do it for all the wrong reasons - to try to signal confidence to the market, when things are going wrong. But actually it's just a PR stunt, as was clearly the case here when Truell went long 70k shares at 200.9p, rather appropriately, on April Fools' Day.
The shares are 78p at the time of writing, so 61% down in less than two months.
I am sorry for anyone who shared my misplaced enthusiasm for this share, although am relieved I recognised & admitted my mistake, and went bearish on it some time ago.
Am I tempted to catch this falling knife? In a word, no. Confidence in the company & management has been shattered, and it needs to raise fresh money, lots of it. That's not a good situation to get involved in, in my opinion.
... to be continued. I have to travel back to Hove now, and collect the car. So will update this article later this afternoon/evening, so pls check back later, if you feel so inclined.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

26 comments
Tung up 30% this morning. Plus500 down 30% and now suspended.
Re Tung I did get involved following Paul's report, but I soon became uneasy and got out around 180p so not too much damage, glad I did. Not sure which way Plus500 will go, it does look over sold if most of the accounts are unfrozen soon then sp should bounce up. As long as that is all it is, but what has prompted this action? Why was this not done before? Seems a bit lax by Plus500 and the FSA or whoever it is now.
Paul,
Based on the average S&P data from 1981-2014, a B-rated bond has a 6.49% of defaulting within a year. So, given that this ranks ahead of the equity, it's not great news, I would suggest.
It's now an active part of my investing checklist, to entirely avoid companies with CEOs who sing overly loudly, like demented canaries at the slightest whiff of gas.
I'm not close to Tungsten, but CEOs that ramp their story like there's no tomorrow are, IMHO, best avoided. People like David Lenigas, the chap who runs BLUR, all these big city folk with even bigger egos and proclamations about cornering multi-billion markets - most of it is hot air and amounts to nothing.
Far better to invest in quality, tangible business, that have a prudent track record, pay a dividend, and that are fiscally cautious.
These type of stocks have quiet bulletin boards, generally are under the radar of many investors, and just get on with delivering. Some would call them boring, I call them a bedrock of my portfolio.
Hi VegPatch
Your comments are appreciated and as you say Crispin himself is famously (or notoriously!?) contrarian and appreciate these may be held by various managers within the Odey stable. Just found it interesting that as a group they are heavily into both these stocks and increasingly so as PLUS 500 continues falling. Having been burnt a little in PLUS 500 and thankfully having avoided TUNG altogehter despite tracking it for a long time I'm just intruiged to see where both these stories end. I'll be honest these two recent events have made me determined to avoid AIM stocks from now on, no matter how good the story and more than enough other opportunities in the main markets for me.
Tungsten (LON:TUNG) placing just announced:
http://www.investegate.co.uk/tungsten-corp-plc--tung-/rns/accelerated-book-build/201505211556469717N/
They sound desperate.
Why repeat verbatim previous RNS's?
Hey I've just come back from a nice lunch and posted. ive now just read the other posts. how pleasing it is that Odey own 9.5% of Tungsten-it is a very great shame that they didn't own 29.99%. And they own Plus 500 as well. A man more pleased with himself it would be hard to meet -what a shame.
Thanks Paul. Some interviewers can get carried away with their enthusiasm so they rather miss the point that the audience want to hear the guest rather than the host. Well done on Tungsten . A mate went long here and is now paying the price despite warnings. The view of director buys is interesting-much more important in Director close period-more to be disregarded after a profits warning.
As mentioned by Paul above, Tungsten has attracted some very smart investors not least Odey Asset Mgt who have owned 9.5% since at least 21 Jan 2015 when the share price was around 280p. Ouch!! I notice having also owned a sizeable chunk of PLUS 500 prior to the recent price plunge they have been buying more and now own 15.6% of the issued shares. Given Odey's reputation it will be very interesting to see how those two situations pan out for them!!
Hi Loose Cannon
Be careful which part of Odey actually holds the companies. They have a number of different funds run by different managers. Crispin is famously contrarian but his Swan fund lost c.20% in April, being 150% short the Aussie dollar vs USD. In fact the Aussie only strengthened 4% vs USD in April...so he really must be leveraged into that trade.
Doesnt really feel a particularly diversified "hedge" fund to me.
Anyway not sure which part of Odey holds the Plus500 and Tungsten but may not be Crispin's fund
Plus500 is in Odey Allegra Developed Markets which is managed by James Hanbury, it maybe in other Odey funds as well.
Tung is in European and Allegra International.
Yes, Odey himself is actually running quite a different portfolio from the Absolute Return guys (who hold the vast majority of the Plus500 (LON:PLUS) position). Also, the name hedge fund is a misnomer. Some funds do have a fully hedged position but even then no-one (sensible) thinks that if you a run a net zero long position you are "hedged". Also imo, if you are paying 2&20 for someone to give you a return in the single digits then you are a bit of a mug (this is what most fully-hedged "hedge funds" run by UK institutions do). Anyway, from memory, volatility of the Absolute Return fund runs well over 10% so make of that what you will.
The yield on a company's bonds is what counts.If you do find a high yield on a highly-rated bond,there is always a good reason for it !
Hello Paul, Is there any chance of your opinion on Tristel trading update which looks quite good?
With regard to bond ratings. B is a very low rating, the lowest investment grade rating is BBB-, so this is a number of notches below this and is very clearly into speculative grade.
From S&P definition
‘B’—More vulnerable to adverse business, financial and economic conditions but currently has the capacity to meet financial commitments.
What this means in terms of probablility of default is that a single B rated bond has around 4.5% probability of defaulting within one year. (This is actually from Moody's but ratings are broadly comparable). The MTNs are B- so would be higher than this which makes sense as they sit below the secured bank debt.
I think you need to be very careful at looking at P/E for AVAP as they are highly leveraged so a low P/E can be obtained by increasing leverage. A better way to value this is using TBV as this is a finance company.
The other thing I am concerned about with AVAP is that they are vulnerable to a raising interest rate environment as lease rates are longer term than there debt profile so will eat up profit. As a counter to this raising interet rates should be a sign of increasing economic activity so should mean business is expanding.
In terms of context I work at a major financial institution which has the second largest aircraft leaser in the world as one of their divisions.
You might be interested in this recent note from Fitch, interesting in itself but which mentions their more positive assessment of the effect of possible future interest rate rises:
https://www.fitchratings.com/gws/en/fitchwire/fitchwirearticle/Aircraft-Lessors-Buoyed?pr_id=983729
"Fitch believes aircraft lessors would be net beneficiaries of a gradual rise in interest rates, as a rising interest rate environment would generally indicate that economic conditions were improving and asset inflation was present. "
As I said above, yes, caution is needed but at the same time it needs to be remembered that AVAP is a fairly new and small company and its bond rating will almost inevitably be lower than more established and much larger companies, including the one in the group you work for. One would expect AVAP's rating to improve as it grows and this company may well double in size over the next three years. One does need to compare like with like and then, as an investor, to weigh one against the other and make a personal investment decision. Btw, Stockopedia has AVAP on Price/Book of 1.00 and Price/TB of 1.02. But, yes, caution is needed, certainly.
Hi Paul
Looking forward to the LVIC articles. What Jaguar have you got?
As for Tungsten (LON:TUNG) I to was fortunate and got out at 206p with a £650 loss but learnt a good lesson, that story stocks with no history are simply not for me. I personally can not understand why anybody would invest in these type of shares when there is so much choice out there!
Paul, I posted this a few weeks ago on the iii bulletin board for AVAP. This was in response to someone who asked why the PER was low in relation to those of peer companies on other markets.
"I think that there may still be a perception that AVAP is dependent on Virgin Australia, on SkyWest routes in WA serving the mining industry there and on Australia itself.. That certainly was the case when the company was set up, a situation perfectly normal since the driver behind the company is Jeff Chatfield, an Australian and the former chairman of SkyWest. Virgin Australia has been losing money, although their last results were much improved and, I suppose, the fall in the oil price will bring its benefits. VA's shareholders include, I believe, SIA and Etihad who, presumably, see VA as their foothold in Australia's regional air market so, for me, this concern increasingly seems exaggerated. I understand AVAP's intention is to diversify to other regions and evidence of this strategy being carried through is in the contracts with Air India Regional, Flybe and Thomas Cook, the last two together growing the lease book by about 40% . I understand that AVAP is now among the top forty aircraft leasing companies in the world so it's perhaps not so small, really. The aviation industry is forecast to grow strongly, the share of aircraft purchases through leasing is now in the 40%-50% region (up from around 20% at the turn of the century), the aircraft mainly used by AVAP, the ATR-72 from the Airbus-Alenia consortium, is by far the most popular regional route aircraft in the world, Asia-Pacific is the fastest-growing region, AVAP has a good position in options (about 35?) on the ATR-72 stretching two years forward, while the recent financing deals (the one for the pre-delivery finance on the two TCG aircraft, as well as the US$500m bond deal) show that AVAP is "growing up" and is now seen as very bankable for continued rapid growth. I'd say that the foundations for steady growth are all there. For me, there's one other factor which is the attractiveness of yields on aircraft leasing in an age of very low yields on other financial instruments, evidenced by leasing companies (admittedly, bigger than AVAP) being acquired, particularly in Asia-Pacific, for their operating yield as much as for anything else.
There in a nutshell are the reasons I'm invested and why I'm prepared to take a chance on the market's perception being behind the curve"
Imo, the bond deal is a second step in effectively widening the margin falling through to shareholders on the leasing business, the first having been the renegotiation last year of the rates on bank borrowings that resulted in a reduction of about 1%pa in average interest paid. AVAP makes somewhere above 13%pa on its leases and its average interest rates on borrowings is now below 5%pa. Having the bond facility in place ought to accelerate growth without the need to resort to placings and dilution and, imo, has been set up to enable the maximum benefit to be obtained from the large number of aircraft due for delivery over the next two years. In the comment above, I failed to mention the preferential corporation tax rate of 10% that AVAP now has for the next five years under Singapore's scheme to foster the growth of aviation-related businesses.
I'm cautious about this business, as you are, but the company does seem to have its strategy clearly identified and to be carrying it through carefully and step by step.
All IMHO, DYOR.
Well...... what a horror show Tungsten (LON:TUNG) turned out to be. I'm disappointed and angry with myself for getting involved in a story stock due in part to the CEO buying £2.5 million worth of stock in 2015 alone and naively believing that they might actually be on to something. I have to learn from this expensive mistake.
Likewise Ben. Truell sucked in a lot of very smart people - some of the best investors I know believed the story too, and also got it wrong. Maybe it was hubris on Truell's part, thinking he could conquer the world? That said, I wouldn't write it off completely - he'll sort out some new funding one way or another, and I'm sure will make it work, but I'm not convinced the current business model of massive cash burn is viable. Also, who knows what slice of the pie existing shareholders will end up with?
P.
Dilution is a risk but he's a shareholder too and may not want to do it, even if he could find a deal where he rebounds financially in other ways. You're sort of losing the game if you do that, and he's got more reputational capital to lose than the average second-tier city Chinese CEO. And there's other ways this thing can be financed, so a hat trick seems pretty plausible.
(Long, tripled the position today, if still a fun-sized gamble.)
Hi bsharman -
I too have burnt my fingers with Tungsten (LON:TUNG). I looked up the notes I made at that time, and I remember asking myself 2 questions. 1) is the proposition sound and viable? and 2) does the management of this company have the competence and qualification to carry it out?
On the first count I believed and still believe that if they can seamlessly integrate and provide a seamless platform to carry out e-invoicing, spend analytics and e-discounting and provide all that at a competitive rate then there is huge profitable market out there.
On the second count, Eddie Truel's CV and background were impressive with successful financial services initiatives to show.
In the event Eddie Truel has shown all the qualities of a buccaneer, and made all the amateurish gaffes that you would ascribe to a wet-behind-the-ears CEO. Put simply, I was taken in.
Have I learnt something from this? Yes. Ignore the siren calls of story stocks. You can make money, serious money, in the stock market without them.
Regards, Ram
out of interest who was the interviewer?
I am being unkind, as the compere is excellent, David Shapiro. But myself & others did get frustrated with his waffling. I think interviewers should ask direct, and simple questions, not effectively make a speech, with numerous points/questions embedded in it.
Woodford himself looked a bit non-plussed, and pointedly asked, "Oh, would you like me to come in?" when the interviewer finally shut up!