Small Cap Value Report (23 Dec 2014) - THT, CBUY, ITQ, INB

Good morning! I'm running a bit late this morning, as it's taken about half an hour to get a reliable WiFi signal here in the wastelands of Cheshire (I'm visiting family for Xmas). Plus we were up boozing until 3am, so hangovers all around this morning.
I like this time of year, not just because of getting together with family, but also because the stock market is thinly traded, so there are more opportunities - fewer people are paying attention, so you can gain first mover advantage when significant news is released, and thin trading can create erratic price movements - so more buying and selling opportunities tend to arise.
We're also likely to see a few profit warnings slipped out too - like this one;
Thorntons (LON:THT)
Share price: 91p
No. shares: 68.6m
Market Cap: £62.4m
Profit warning - the company mentioned two main reasons for a profit shortfall - reduced demand from supermarkets, and disruption from the move to a centralised warehouse.
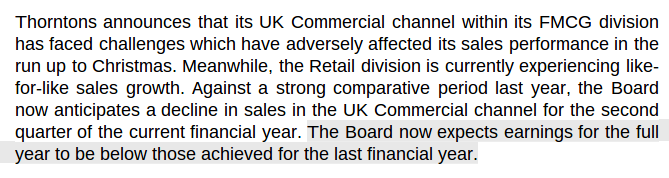
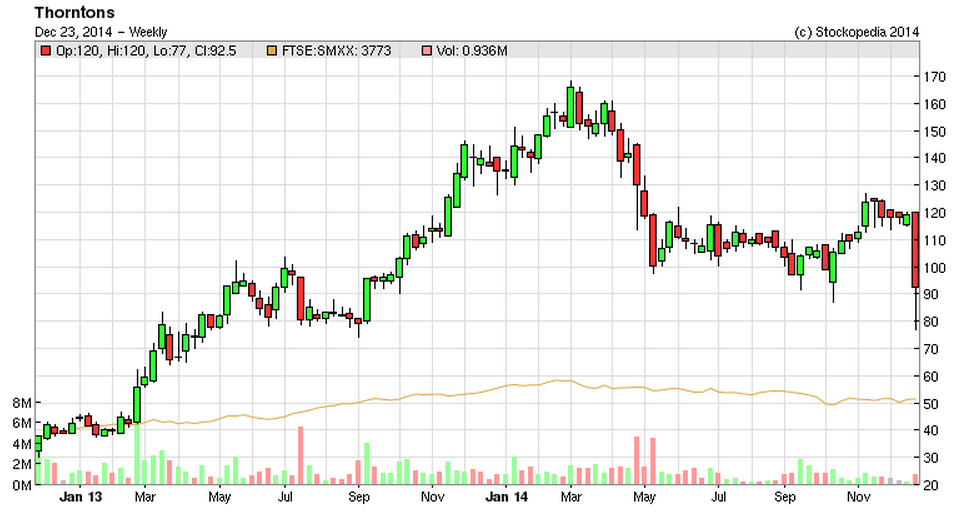
That's a disappointment, and it badly undermines the investing case for this share - which was that earnings were in a recovering trend. If that's no longer the case, then really it's difficult to see any reason to invest here - since the operating profit margin is thin, the Balance Sheet has too much debt, and a pension deficit, and there's no divi (although I seem to recall there was talk of reinstating a divi).
Broker consensus was for 10.4p EPS this year (to 28 Jun 2015), but at a guess it looks to me as if perhaps c.8p might be closer to the mark. That would put the shares on a PER of just over 11, which isn't particularly cheap considering the Balance Sheet liabilities.
My opinion - I don't share the Board's confidence in their strategy. Also, bungling a warehouse move just smacks of incompetence. Overall these shares are not of any interest to me - I'd only be interested on a very low PER, so maybe at 50p per share or below. It's just not a very good business, in my view.
Cloudbuy (LON:CBUY)
Share price: 28.7p
No. shares: 119.9m
Market Cap: £34.4m
Trading update - I don't know this company well enough to be able to fathom what today's statement is telling us. The market has interpreted it as a mild profit warning, as the shares are down c.10% this morning.
They seem to be saying that £1m of work that has already been done is going to be booked as revenue in 2015, rather than 2014. Also that costs have over-run. There is then a lot more detail on potential revenue from contracts overseas.
To date this company has a track record of very upbeat-sounding trading statements, but very poor financial results. So I tend to regard it sceptically. Let's see the profits and divis!
Interquest (LON:ITQ)
Bit of a strange one, this. The company seems to have have put itself up for sale, but announces today that no deal has been done, despite discussions with a number of interested parties. That sends a rather worrying message to shareholders - i.e. that potential buyers clearly don't think the company is worth as much as management hoped.
So the formal sale process has now been terminated.
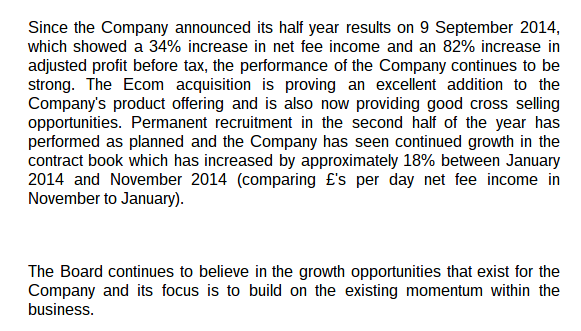
Today's trading statement sounds OK though;
The Stockopedia valuation graphics look middling to good, although it should be noted that lots of small recruitment companies are priced on a similar, fairly modest rating, so there are plenty to choose from. I haven't checked the Balance Sheet, although it looks from the EV figure that there is some debt.
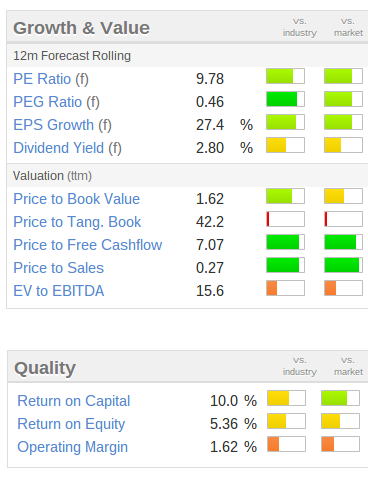
There is a risk that the market might see this company as damaged goods, given that it initiated & has now abandoned a sale process.
Interbulk (LON:INB)
Results for the year ended 30 Sep 2014 are published today.
Its financial position looks precarious - the Balance Sheet has net tangible assets of negative £36m, and it seems clear from the narrative that the company is dependent on bank facilities, and the situation looks precarious to me.
Bottom line, they need to do an equity fundraising to repair the Balance Sheet. That makes it uninvestable for me - it's too high risk, and for that reason it's gone on my bargepole list. Everything might well turn out fine, but why risk the chance of a 100% loss, if the bank turn nasty?
That's it for today. I think it's a half day tomorrow, so I'll do a report here as usual, probably a bit shorter than usual, depending on what news items there are.
Regards, Paul.
(of the companies mentioned today, Paul has no long or short positions.
A fund management company with which Paul is associated may hold positions in companies mentioned)
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

12 comments
Thanks Paul. I would be interested in your thoughts on Gervais William's book on investing in AIM. I haven't read it yet - probably you haven't either? But I saw he got some good press from Anthony Hilton, who in my view is the best financial journalist out there. http://www.amazon.co.uk/Future-Small-worlds-market-beyond-ebook/dp/B00P7VJGD4/ref=sr_1_1?ie=UTF8&qid=1419346944&sr=8-1&keywords=gervais+williams
I saw Gervais talk about this at Mello 2014. It was an interesting pitch and he had some useful statistics to back up his argument that outsize returns will be made in the small-cap arena in future. However to a degree he's talking his own book (pun intended) and I think that his investing book is intended to convince people who consider anything below 500M uninvestable. If you already have money in small-caps (and AIM) then I'm not sure what you'll get out of the book. Other than an entertaining few hours that is!
Thanks! Very useful feedback. I agree with the premise that small cap offers good returns (Adnams is my only 10 bagger). And actually I think small cap is the one place where private investors have an "edge" over large institutions, HFT, and all the other shenanigans. Hence I really like the stockopedia product, and Paul's blog particularly.
In terms of the Thorntons (LON:THT) trading statement this morning, they say earnings will be below those achieved last year. Given broker estimates were 10.4p for 2015, and they achieved a basic EPS of 7.8 for 2014, I would expect them to maybe do between 6 and 7 for 2015. This would push the PER to between 13 and 15 based on the current SP of 91p. This looks a stretched based especially given the balance sheet issues raised by Paul previously. I'd be interested in getting other readers views about the company.
For information - I don't have a position, but have had it on my watchlist for a while.
Current level of hideousness = 17.6%.
Probably because most of the Manchester City and United football stars live there. (Unlike their fans who mostly live in Essex.) :-)
Steve
Zamano released interim statement after hrs yesterday. http://www.investegate.co.uk/zamano-plc--zmno-/rns/interim-management-statement/201412221631255129A/
This company is on something like 2.5x last years cash flow. The statement last night says they are ahead of last year. Well worth a look but it is under 10m mkt cap.
Hi shauniekent,
Good spot - I've had a quick look at Zamano (LON:ZMNO) and it looks very good value.
Too small & illiquid though - I try to avoid things that small, as once you buy them, you tend to be stuck in them & unable to exit, except for a hideous bid/offer spread.
Regards, Paul.
I looked at Zamano (LON:ZMNO) a while back, but then googled them and was faced by streams of complaints and allegations that they are scamming people. Try it. Not for me.
Good Morning Paul!
And welcome to Cheshire! Those of us that are fortunate enough to live here will know that it is a green and pleasant land, rather than a wasteland!
Paul.
Hi Warranstar,
Indeed, Cheshire is lovely. I was only teasing of course, with my original description!!
Nice fast trains into London too, from Crewe.
Regards, Paul.
Apparently the county boasts the highest levels of Rolls Royce ownership and champagne consumption, per head, in the UK. I am from Essex: Ford Cortinas and Skol lager!!!!