Small Cap Value Report (23 Dec 2016) - RCN, NGR, NETD

Good morning again! Paul might not find it necessary to write today, as news is likely to be quiet.
As is customary before Christmas, the LSE closes this afternoon at 12:30.
Redcentric (LON:RCN)
Share price: 84.25p (+1.5%)No. shares: 147.2m
Market cap: £124m
Interim Results to 30 September 2016
This technology services provider has been at the centre of an accounting misstatement issue, as discussed by Paul here.
I also recommend this article by Mark Bentley at ShareSoc.
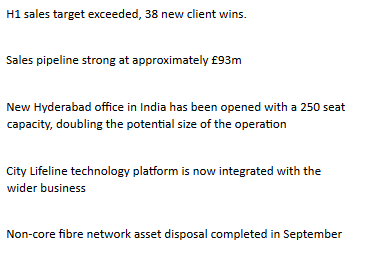
Today's H1 2017 results are quite positive on the operational side:
The financials are a lot more mixed, however.
Accounting problems tend to affect public valuations in a dramatic way. This is largely to do with questions around integrity but also because they make the act of valuation itself far more complicated.
For example, today's announcement includes restated H1 2016 figures, which need to be compared with the original figures as published here.
Here's a selection from today's results:
- Revenue up 2.0% to £53.0m (H1 FY16 restated: £51.9m)
- Adjusted EBITDA* up 16.6% to £9.1m (H1 FY16 restated: £7.8m)
- Statutory profit before tax £0.3m (H1 FY16 restated: £2.5m loss)
- Net debt £34.4m (31 March 2016 restated: £37.8m)
And here are the effects of the restatements for the year ended March 2016:
- Revenue restated at £103.3m vs £109.5m (reduction of £6.2m)
- Adjusted EBITDA* restated at £13.0m vs £25.8m (reduction of £12.8m)
- Statutory operating loss restated at £4.4m vs a profit of £8.4m (reduction of £12.8m)
- Statutory loss after tax restated at £5.2m vs a profit of £5.2m (reduction of £10.4m)
For me, these changes make it impossible to value the company in a sensible way. We can think about applying an earnings multiple to a £5.2 million profit, but we can't do the same for a £5.2 million loss!
To give credit where credit is due: despite the disastrous nature of recent events here, the company seems to have dealt with it in a very professional way. A forensic review is underway, a new CFO has been appointed, and the latest interim results have been produced, along with restated numbers, in a reasonable timeframe.
An explanation of what happened:
A number of accounting policies and practices,
specifically those in respect of cost accrual, cost deferment and
revenue recognition had been incorrectly applied and other accounting
errors and misstatements had been made. To date there has been no
evidence of theft and the misstatements are attributable to profit
overstatement over a number of years with revenues being overstated and
costs understated in broadly equal proportions.
It looks as if the debt position has been manipulated:
Following restatement of cash, trade creditor and trade
debtor balances at 31 March 2016, net debt was £37.8 million. Net debt
at 30 September 2016 was £34.4 million. Despite these adjustments
the Group's restated net debt position as at these dates was not
representative of the underlying position as although technically
correct from an accounting perspective, there was significant stretching
of creditor payments in particular around operating cost items. The
average month end net debt position over the eight month period to 30
November 2016 was £42.0 million and better reflects the Group's
underlying net debt position over the period.
Dividend: Unsurprisingly, the Board has resolved not to pay a dividend.
Bank support: Banks have given covenant waivers for prior periods, and are discussing future covenant levels. They are said to remain supportive!
My opinion:
I've managed to work my way through most of this announcement, but it's slow work. As I said, things get complicated in a situation like this!
Even those on the inside will have found it very difficult. The RNS says that "a level of judgement has been applied" - in other words, there is no objective answer to fixing what has gone wrong.
On valuation, I'm a bit perplexed as to why the market cap remains so high.
The current share price gives it an enterprise value of £166 million, for a fairly mature business which made a multi-million pound operating loss last year, has only scraped a tiny statutory profit over the last six months, and is going to suffer a lot more short-term costs and headaches associated with these accounting mistakes.
Even if the adjusted EBITDA was £9.1 million for the latest period, I'd have no interest in paying anything remotely resembling a normal earnings multiple for this. For me, the share price is still about double what I'd consider to be fair value.
When the dust settles, perhaps it will make a good case study for clues or red flags for spotting accounting problems.
NATURE (LON:NGR)
Share price: 11.5p (-16%)No. shares: 79.3m
Market cap: £9m
Significant Oil & Gas Contract Win
A regular reader has asked me to mention this tiddler, whose share price closed 150% higher yesterday after the announcement of a contract win.
It's a small wastewater treatment company which has been unprofitable for the past several years, and it has a StockRank of just 13.
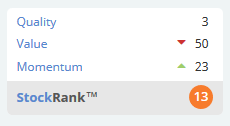
In general, it's a great idea to avoid investing heavily in companies with very low StockRanks. They tend to be speculative - so you can win big occasionally, but there is also a good chance you will lose 100% of your investment.
Based on some online comments, investors are hopeful that this is a portentous contract win:
Nature Group PLC (AIM:NGR) the provider of port reception facilities and waste treatment solutions for the oil, marine and process industries, is pleased to announce that its Oil & Gas division has been awarded a major contract by an international oil company ("IOC") for the provision of containerised slop-treatment units in the Central North Sea.
The contract is for the deployment of multiple treatment units and will commence on 1st January 2017 for a period of 5 years. The overall contract value is estimated to be at least £5 million.
For context, the company generated £6.2 million of revenues in H1 2016.
At those results, it was revealed that the company had a cash position in late September of £0.7 million, with a further £0.3 million in working capital facilities. The pre-tax loss for the period was £0.9 million.
My opinion:
This sort of stock goes into my "too difficult" basket. Maybe it will generate more oil company contracts, and start generating positive financial results again. But that's just not something I'm going to be able to figure out without a lot more research and information, I'm afraid.
I can't find much else of interest this morning, so all that remains is for me to wish you a Merry Christmas. I hope you had a profitable 2016, and that 2017 will be even better!
Thanks for reading.
Graham
Just an after-thought from me (Paul) too. Thanks to Graham for covering the above.
Another announcement caught my eye;
NetDimensions Holdings (LON:NETD)
Share price: 73.6p
No. shares: 51.3m
Market cap: £37.8m
Trading update - an intriguing announcement from this software company.
Sales revenue for the period is expected to be above US$26M.
In addition the Company is anticipating that adjusted EBITDA will be approximately US$2.0M.
This compares favourably with the interim results, when the company reported $10.5m revenues, and a $0.8m adjusted EBITDA loss.
Therefore, deducting one from the other, H2 must have been $15.5m revenue (up 48% on H1), and a significant move from loss into profit (at the EBITDA level anyway).
Looking at the consensus forecast shown on Stockopedia, it looks as if this upturn was expected - with a forecast of $26.5m revenue.
I've checked the cashflow statement, to see if the company is aggressively capitalising development spend (which would make EBITDA meaningless). It's not, which is good news - only $12k was capitalised last year.
Balance sheet - is strong, with a large net cash balance of $11.2 when last reported at 30 Jun 2016. Although bear in mind that deferred revenue of $7.5m reflects amounts that customers have paid up-front for. Treat that how you wish, I'm just flagging it.
Possible takeover bid? - this is intriguing;
On 5 October 2016, the Board of Directors of NetDimensions ("the Board") also announced that it had received an approach which may or may not lead to an offer being made for the entire issued share capital of the Company.
The Board is in advanced discussions with interested parties and further announcements will be made in due course.
That seems a fairly direct steer that a takeover bid could happen.
My opinion - I don't know this company at all well, but I think this announcement looks interesting.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

20 comments
Kicking myself that I didn't buy NetDimensions Holdings (LON:NETD) when I predicted they would get taken over by Learning Technologies (LON:LTG) earlier in this thread.
It's nice to be right but not much use if I don't make any money from it.
It's a good strategic fit for Learning Technologies (LON:LTG) but I worry they have over paid. Learning Technologies (LON:LTG) down 9% on the news while NetDimensions Holdings (LON:NETD) is up 24%
I see NetDimensions Holdings (LON:NETD) has offices around the world with a base in Grand Cayman and AGMs held in Hong Kong - not my cuppa tea. Pays dividends although it makes a loss (forecast to turn in 2017). It does look like it could be a young rocket though . . . .
Thanks Paul and Graham for not pulling your punches on the companies you cover. More of the same when you get back in 2017 please.
Many thanks to Paul for all your hard work this year. Your methodical approach to get to the heart of the fundamentals and balance sheet has really helped inform my own knowledge.
Looks like a great addition with Graham joining the team. I wish you both a Merry Christmas!
A very happy Christmas to all the team at Stockopedia, with an especial thanks to Paul and Graham who have between them stopped me losing a great deal of money and may have helped me to make some!
A healthy and profitable New Year to all.
Compulsory morning reading for me these days. Thank you very much not only for the analysis, but for the constant reminder that a disciplined approach is vital.
Jon
PS And for BooHoo, my second biggest winner this year after the joy that was PetroLatina.
Many thanks and a very Merry Christmas to Paul and Graham! What started off as a terrible year for me (-19% in June) has been turned into a marginally profitable one, and I can hopefully maintain my 18 year record of never having a down year. I owe a big thanks to these reports for that!
PS. Excellent, balanced summary of Redcentric Graham!
Merry Christmas - re Redcentric - perhaps people have just assumed that the bad news is already in the share price following the recent falls.Perhaps the analysts are already away on holiday !
I would like to echo the above sentiments to Paul and Graham and the great community of investors who share information via the stocko site. Also thanks to Ed and the stocko team for a great site. Merry Christmas and Happy New Year to all.
Nice overview of Redcentric Graham. Very clear overview of a pretty messy picture...
It occurs to me that maybe Learning Technologies (LON:LTG) could be one company interested in buying NetDimensions Holdings (LON:NETD) .it might be a nice match although you have to wonder what premium over today's price they might be willing to pay.
Whoever they are talking to seemed to become interested when the NETD price was 40p so you have to imagine that they would be unlikely to want to pay more than 80p now?
Just speculating but it does fit the LTG strategy.
I'd just like to offer my heartfelt thanks to Paul and Graham for these excellent articles. They have been of enormous help to me over the last three years.
All the best to both of you
Steve
Many thanks to Paul and Graham for these fantastic SCVRs.
Wishing you both a very happy Christmas and successful New Year.
Thank you to our 2 guides for sticking to your guns and calling it how you see it. I have found it interesting and thought provoking. Good luck in 2017.
Merry Christmas everyone, this year has been the most successful in my 2 decades of investing and this site plays no small part in that, I'm off to buy more champagne flutes, may all your seasonal hopes bear fruit!
Merry Christmas Graham (thanks for all of your recent articles), Paul (thanks for much interesting reading)... and to all
Thank you to our two contributors and the many correspondents for a great year of enjoyable - and informative - reading.. A happy Christmas to all.
I thought I would look to see who the Redcentric (LON:RCN) auditors were. It was PWC.
http://www.redcentricplc.com/media/2181/redcentric_report_accounts_2015.pdf
On Redcentric
How could elementary accounting mistakes be made year after year without the auditors noticing? May not be theft but it certainly smells of manipulation.
The FD has been replaced by an internal candidate. He is part of the problem! Either he must have known of the problems or he is incompetent. The company needs a new board before I will even consider an investment.
I was genuinely surprised to see PWC had signed off the previous Redcentric accounts without reservations. I really would have expected them to pick up these issues. I imagine they will be the ones driving the recovery to try to salvage some reputation from the debacle.
That being said, the issue of "significant stretching" of supplier payments to hit a year end net debt position exists in many companies that I know of. Perhaps it's a grey area that people are pushing too far and the debt positions should be stated as an average over the year and not a year end snapshot.