Small Cap Value Report (23 Jan 2015) - SAL, RBN

Good morning!
Spaceandpeople (LON:SAL)
Share price: 57p (up 27% today)
No. shares: 19.5m
Market Cap: £11.1m
Trading update - this niche marketing company, which manages retail & promotional space in shopping malls & other open spaces (e.g. railway stations) in the UK & Germany mainly, certainly had an annus horribilis in 2014, with two profit warnings, and a severe drop in the share price. I covered it extensively here in the past, click here for my previous articles.
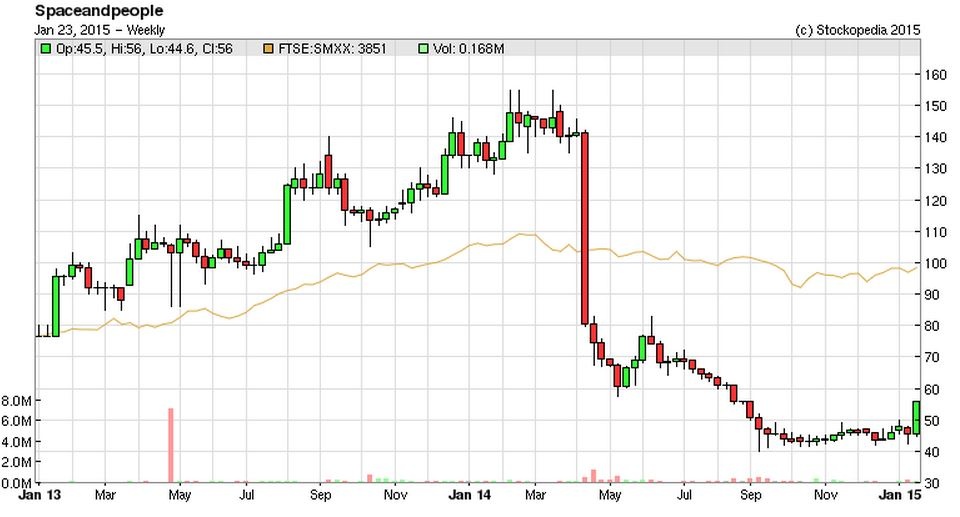
Looking at the chart, the shares have been bottoming out since Sep 2014, having lost two thirds of their value from the peak in early 2014 (when profit expectations were much higher).
Things sound a lot more positive today, with the update saying;
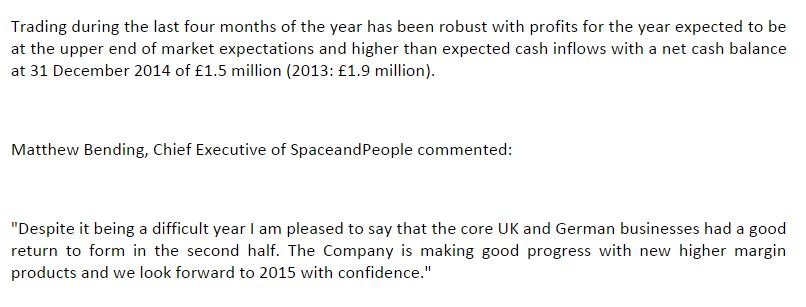
"Upper end of market expectations" is the key phrase above. Although obviously market expectations are now much lower than they were a year ago. The range is, I believe, £0.8m to £1.0m forecast profit for 2014, pre-exceptionals (some redundancy costs mainly).
Net cash - reported at £1.5m - whilst probably a seasonal peak, it's not bad for a profitable, dividend paying company that is only capitalised at £11.1m, and that's factoring in today's share price rise.
I understand there was never any issue with solvency here, which is one of the good things about screening for adequate financial strength - you don't have to worry about companies going bust, even if something goes wrong with trading.
Forecasting - the company has learned from its experiences in 2014, when a series of problems with contracts - not renewing, being delayed, etc, lead to the original profit forecast turning out to be far too optimistic. This was a new issue for the company, as in the past it had won the business it expected to win.
Going forwards therefore, the company now has a policy of guiding the market to a base case scenario for profits, on existing levels of business. The pipeline of new business is now treated as icing on the cake. Therefore, we should from now on receive very conservative profit forecasts, and see those gradually edge upwards as the year goes on.
Strategy - as part of the recovery process from its problems in 2014, SAL had a refresh of the board, bringing in new Non-Execs who have relevant (and considerable) experience. This has helped refocus strategy on the core businesses in UK/Europe, and in particular on generating new, higher margin revenues.
New promotional kiosks have been designed and trialed, which considerably broaden SAL's appeal to its shopping mall landlord clients. Instead of just offering kiosks for third parties to sell things like mobile phone covers, jewellery, etc., SAL will soon be offering promotional kiosks that are rented out on a weekly basis to companies wishing a professional-looking stand in a very high footfall area. So think charities, utility companies, any company that wants interaction with the public on a short term basis.
The trial has gone well, and it's now a roll-out over the next two years. Edison have put out a note today with more detail - it's on their website. I think this additional, high margin business, augurs well for future profitability. It's good to see SAL's business model evolve, and the company is innovative in outlook.
My opinion - I don't believe in adopting a standard policy for profit warnings. Some people do, and they immediately ditch shares which disappoint. That works for some people, and it's a strategy I respect, but it's not for me. It's important not to let the emotional pain of a loss from a profit warning cloud your judgment. I try to get over the emotional response as quickly as possible (within a few minutes), and not dwell on it. Draw a line under it mentally, and then look at the current position with a cool head.
I see every profit warning as being a unique situation which needs properly investigating. So it's a question of crunching the numbers, untangling the Directorspeak, and forming a view on essentially whether the company is a good company that has run into temporary problems and can recover, or whether it's a bad company that is permanently on the wane.
My view, after doing a lot of digging, was that SAL would almost certainly recover from the problems in 2014. That it would take a bit of time, but it would have been a mistake to throw out the shares when sentiment was negative, and the valuation extremely low.
I'm looking forward to seeing management again after the results are published in Mar 2015. In my opinion, they've got their mojo back, and are looking forwards to growing the business, rather than firefighting problems (which have now been resolved).
We might well see a headwind on the share price from stale bulls wanting to exit, so it wouldn't surprise me to see the shares give back some of today's big rise, but the negative trend is now clearly over, and I am looking forward to hopefully getting my money back here, with a timescale of c.1 year.
Robinson (LON:RBN)
Share price: 150p (down 13% today)
No. shares: 17.7m
Market Cap: £26.6m
Trading update - sounds fine for 2014, with profits in line, but a wobbly outlook;
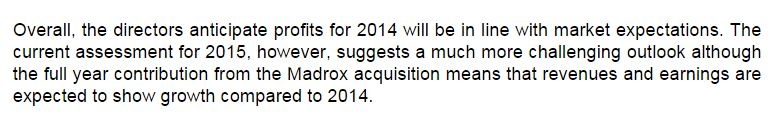
The words "much more challenging outlook" have rattled me, as that doesn't sound like a temporary issue.
Valuation - broker consensus is 12.8p EPS for 2014, so that looks in the bag, for a PER of 11.7. The outlook isn't good, but note the last sentence says that EPS should still rise in 2015, but not by how much.
Bear in mind also that this company has surplus property assets, so there's hidden value in the balance sheet from that, although I don't recall the figures. Update: I've just checked the 2013 Annual Report, and note 10 says that the market value of surplus property is est. £2.7m, so not particularly material, and less than the company's net debt.
I did more detail on the figures after the interims, in my report here of 20 Aug 2014.
My opinion - I did have a small position in this share, but have decided to ditch it today. Packaging is surely an area where margins are going to come under increasing pressure, as the supermarkets squeeze harder & harder? With an uncertain outlook, I'd say the risk of another profit warning is high. Looking at Robinson's Annual Report, most of the pictures of their products are food packaging. So I think they will be mercilessly squeezed on price by their customers, in a supermarket price war situation that is likely to continue permanently.
This is an extremely illiquid share too, and I've only been able to trade 1,000 shares at a time, so £1.5k, which makes it pointless getting involved really, with a nasty 10p bid/offer spread at most times too. I might revisit it once the level of sustainable trading has become more clear, but it's not a sector that appeals.
updating, pls refresh page periodically
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

21 comments
I was surprised by the SP reaction to yesterday's prelims. To me the accompanying chairman's and ceo's comments read very much as a "the worst is behind us and we are getting back on track" message.
they reported yesterday...
http://www.investegate.co.uk/spaceandpeople-plc--sal-/rns/preliminary-results-and-proposed-final-dividend/201503230700091032I/
regards
THESE NOTABLE COMMENTS IN JANUARY GAVE ME COMFORT…..
Space and People, (AIM:SAL) the retail, promotional and brand experience specialist, today issues a pre-close trading update ahead of its final results for the year ended 31 December 2014, which will be released on 23 March 2015.Trading during the last four months of the year has been robust with profits for the year expected to be at the upper end of market expectations and higher than expected cash inflows with a net cash balance at 31 December 2014 of £1.5 million (2013: £1.9 million).
Matthew Bending, Chief Executive of SpaceandPeople commented: "Despite it being a difficult year I am pleased to say that the core UK and German businesses had a good return to form in the second half. The Company is making good progress with new higher margin products and we look forward to 2015 with confidence."
BUT IM CONFUSED THEREFORE WHEN YOU SAY
it is probably a mistake to judge the business on the share price reaction to a set of results that we already knew were going to be bad.
????
It's all about what timeframe you are looking at. they'd already halved profit forecast on 17th April 2014:
http://www.investegate.co.uk/spaceandpeople-plc/rns/trading-statement/201404171200020922F/
and then halved it again on 11th September:
http://www.investegate.co.uk/spaceandpeople-plc/rns/trading-update---september-2014/201409110701023748R/
before giving the more positive update that you refer to. So better than where the market had them after the september update but still bad in the context of where they expected to be at this time last year.
ok- Ive personally always gone on most recent company updates so that is what i base my analysis on largely - It hasn't been a bad strategy over the last 30 years of my investing career.
The January update was positive or am I missing something? Then the share price tanks this week….
It's all about expectation. The results were worse or the outlook was more cautious than some expected following on from the January update hence they sold. Maybe their expectations were too high, maybe it was just a short term trade expecting further out-performance in the results that didn't materialise. If the results exceeded your expectations, you have a 30 year track record of getting these calls roughly right and the share price drops that's called opportunity!
Looks like we might be on for another annoys hornbills . Paul, any further thoughts ?
Looks like we might be on for another annoys hornbills. (sic)
Clearly the SP reaction today implies that some were hoping for more, however if you believe that the management have understood the issues and are adressing them the comments in the results imply a cautious optimism and a return to growth for 2015 rather than another bad year:
The 2015 pipeline is potentially much stronger and we are working hard to ensure that we are in a position to win as many new contracts as possible whilst continuing to increase the number of promotions and retailers we place into venues and improve the quality and pricing overall...
A tough year has brought focus on developing the most profitable aspects of our business, cost cuts, a new board with added dynamism and experience, new products and a realisation if you don't innovate you go backwards. That said we have managed to generate £1 million of normalised profit for the year and the Board will recommend a final dividend of 2p per share at the forthcoming AGM. The management and Board feel we have a sustainable and profitable route to growth and we are driven to improve profits in 2015.
We obviously have to wait to see if this optimism is warranted (and management didn't exactly cover themselves in glory with how rapidly the businees missed expectations) however it is probably a mistake to judge the business on the share price reaction to a set of results that we already knew were going to be bad.
Paul - good comments on SAL. Except Edison Research. Edison is a joke. Stockopedia should have nothing to do with them - they damage your brand. Full disclosure - they fired me while I was on probation and didn't pay me. They claimed the reason that the fired me was "cultural differences" - but I suspect it was more to do with the fact that I raised concerns about the accounting at one of their corporate clients - Adler Real Estate.
Pity I didn't read you article about Robinson before today! Can't help thinking the shares have been oversold. Falling oil price should help the bottom line. I like the fact they have been open about the trading outlook. A case of cold comfort after a massive fall.
I don't think I'll be revisiting Spaceandpeople (LON:SAL)
I remember speaking to the CEO at the time and struggled with his explanation of how things had deteriorated so quickly, sounded more like it snuck up whilst the celebrations were ongoing.
I promptly sold and glad I did as I'd still be down from that point given the rise of yesterday.
That said, there may be some much needed momentum behind the shares now. My worry is what happens when the shopping centres decide to re negotiate the contract again at terms that are not so good like last time - bit too much of an accident waiting to happen for my risk apatite these days
Hi Paul
Slightly off point with the report but wondering whether you have heard anything that would explain the massive fall in Flybe (LON:FLYB) today?
Cheers
Looking at Digitallook there appear to have been some quite recent broker downgrades of earnings for the next 2 years. They are quite significant downgrades from what I can see, Perhaps this might be the cause?
I would ignore purchase of shares by the chairman as this was his first purchase since November, when he was appointed. To be fair had he bought earlier he could have got the shares cheaper. Other director purchases were made to prop share price in September after profit warning.
Grant of options is different matter, harder to justify but generally this happens in AIM so standard practice - not that I approve of it but it does happen...
If the Board knew that a positive announcement was coming, how would the issue of options and purchase of shares in such circumstances avoid being seen as insider trading?
Hi Paul -
" Going forwards therefore, the company now has a policy of guiding the market to a base case scenario for profits, on existing levels of business. The pipeline of new business is now treated as icing on the cake. Therefore, we should from now on receive very conservative profit forecasts, and see those gradually edge upwards as the year goes on. "
That's a splendid way of managing stakeholders' expectations going forward. I only wish other AIM companies take a leaf from their book.
I believe this morning the board of SAL confirmed its reputation for poor communication of the status of their company. The year-end trading update is six lines long (Paul’s quotes comprise the whole thing). It includes the minimum requirements expected by Paul but I think the board needs to comment more often and more fully until it regains the trust of the market after the fiasco nine months ago when the board finally woke up and the SP dropped 40% in a few minutes.
Meanwhile, Paul believes the company has learned from its mistakes in managing last year but I believe the company needs to communicate with its owners much better. As of right now the SP is up 26% this morning but still 57% down in the nine months. High enough for now.
Hi Splode,
Fair points. I think the company is learning from its mistakes, and I agree that they need to communicate trading performance more frequently, as the gaps in between news are too long.
In fairness though, Xmas trading is key, so they can't update on that until all the figures are in from the traders operating the stalls in the UK & Germany. Operational gearing is high, because most costs are fixed, so the profit figure can move about a lot depending on how well the kiosk traders perform over Xmas.
They know that it's going to take time to rebuild investor confidence, but today was a pretty good start!
I thought today's statement was perfect. No unnecessary waffle, just a clear indication of what profit they're going to make. They even gave the range specifically in their last update, and have now confirmed they're towards the top of that range. What more do you want?!
Regards, Paul.
SAL Management have "come through" with lots of options granted 10 days ago at 47p. Also I see the new Chairman bought a few shares less than 3 weeks ago. I am a bit surprised the company was not in a closed period at that point but no doubt that is me misunderstanding the rules on such things.
I am a bit surprised the company was not in a closed period at that point but no doubt that is me misunderstanding the rules on such things.>
The key is in the title of the RNS 'Pre-Close Trading Statement' :-)
The regs are to do with trading close to the results announcement so a lot of companies issue a trading statement beforehand indicating that they are entering a close period. It's close as in near to not closed as in not open.
This is an exciting ride Paul. One of the challenges is getting stock in the market on a day like today. Worth noting if anyone is looking at taking a stake. That said the 5% yield is helpful and the Management team have come through this with, in my opinion, colours. We all expect there to be problems in small companies and yet they have shown themselves to understand the market, the issues and be as transparent as they can. In this day and age that puts a premium on the share for me.