Small Cap Value Report (23 Jul 2015) - INL, MTC, VTU, BMY, JDG

Good morning!
Inland Homes (LON:INL)
Share price: 70.7p (up 2.6% today)
No. shares: 202.2m
Market cap: £143.0m
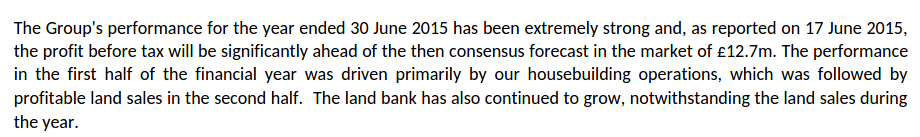
Trading update - this covers the full year to 30 Jun 2015. It all sounds very positive, with the key paragraph saying this;
A lot more detail is given, and the Directorspeak sounds positive:
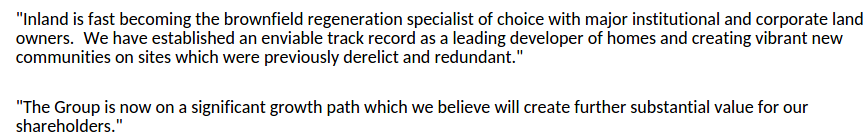
My opinion - I like this company, and it seems to be on a roll. There are rich pickings to be had in land & property development at the moment, and there's no doubt the Directors here know what they're doing.
However, it's also important to remember how cyclical housebuilding is, and how inflated prices in the South are - so the party won't last forever. I will need to see the full figures, when they are released in Sep before being able to assess whether the shares are still good value or not. Most housebuilders are looking richly priced in comparison with net assets now, but that's justified to a certain extent because land is in the books at cost, and is often worth more at open market value, and much more once they've built a house on it.
Mothercare (LON:MTC)
Share price: 265p (down 7.5% today)
No. shares: 170.7m
Market cap: £452.4m
Q1 trading update - I used to be negative on this stock, due to its poor performance and weak balance sheet, plus legacy issues such as onerous leases, and a pension deficit. However, I took the shares off my bargepole list on 30 Apr 2015 at 222p, because the company did a big refinancing, thus addressing my concerns.
Astute investor/trader Richard Crow made a good case for the shares in one of my audiocasts with him, pointing out that new management have a good track record in the sector. Although I considered buying some shares, the valuation looked to have got a bit ahead of itself, so I decided not to. Therefore I'm interested to see if this morning's dip might be a buying opportunity?
The company says that overall trading in Q1 was "in line with expectations".
It sounds as if the UK is trading well, but international not so good, with sales in constant currency down 1.3%, and when currency headwind is added into the mix, international sales were down in sterling terms by 4.8%.
Online sales in the UK are noteworthy, at +23.9%, so clearly their online strategy is working well.
The Directorspeak sounds a tad cautious, in particular;
"It is still early days in our turnaround and we recognise that there is still much to do. Our vision remains clear - to be the leading global retailer for parents and young children."
Valuation - since they are trading in line with expectations, the current year broker forecast is a figure we can probably hang our hats on. This shows 9.5p EPS for y/e 28 Mar 2016, rising to 13.9 next year. So at 265p the shares look to be on a fairly racy rating - the PER being 27.9 falling to 19.1 next year. That's fine if the broker estimates turn out to be too pessimistic, but based on today's statement the estimates look to be bang on.
My opinion - I like the turnaround story here, but for the time being the shares look fully priced to me.
Vertu Motors (LON:VTU)
Share price: 66p (up 2% today)
No. shares: 341.1m
Market cap: £225.1m
Trading update - as you would expect in a time of ultra low interest rates, improving consumer sentiment, and the strong pound making imports cheaper, car dealerships are doing a roaring trade at the moment. Although the margins on new car sales are tiny these days apparently, with manufacturers squeezing out the maximum profit for themselves.
Today Vertu says;
During the four month period to 30 June 2015 (the "Period") the Group saw continued growth in like-for-like revenues and gross profits, both from its vehicle sales and in the higher margin aftersales activities. With overheads remaining under control, the Group's profitability in the Period was strong and ahead of last year. The Board expects that the Group's trading performance for the year ending 29 February 2016 will be in line with current market expectations.
That sounds fine, no surprises there.
Vertu also has a smashing balance sheet, with loads of freeholds - I went through the figures in some detail in my report here on 13 May 2015.
Overall, I like this share, but there's not much difference between several car dealerships, e.g. Cambria Automobiles (LON:CAMB) and Caffyns (LON:CFYN) also have very strong balance sheets too, and are on similar valuations. This one is bigger, so the shares are probably more liquid than those other two. I suspect there is likely to be a wave of consolidation in the sector sooner or later, so there could be nice upside from a takeover bid perhaps?
Bloomsbury Publishing (LON:BMY)
Q1 trading update - says the group has traded in line with expectations.
Interestingly, it sounds as if they are getting another bite out of the lucrative Harry Potter cake:
We are on schedule to publish the Illustrated Edition of Harry Potter and the Philosopher's Stone on 6 October. Rights in the illustrations have already been sold in 24 languages.
My opinion - it's so difficult to value this company, because nobody really knows what the long-term future of book publishing is going to be. I'm not interested in investing in book publishers, unless they are incredibly cheap, so it's not for me.
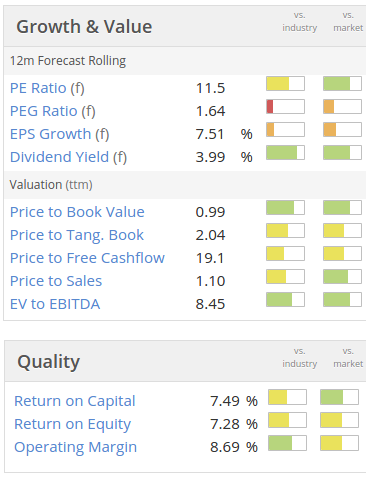
It's got a high StockRank at 97, although I don't think StockRank would really be able to anticipate the structural decline of a sector. Note that the divis are useful here, and it has a decent balance sheet.
Judges Scientific (LON:JDG)
Trading update - this seems a rather long-winded, and slightly confusing update. But the upshot seems to be that H1 will be below last year's H1, but the order book is strong, so they think the full year will be alright.
Notwithstanding a positive contribution from Armfield, your Board expects interim earnings per share to be below last year's level, with a stronger second half weighting based on the interim order book that has built up during the period. As a result, the Board remains confident in the Group's ability to achieve current market expectations for the full year.
If my memory serves me correctly, something like this happened before with Judges, and the full year figures were indeed alright. So I think the company's outlook statements have credibility - which is probably why the shares are almost unchanged on the day today, whereas most companies's shares would have sold off on an H2-weighted year type of statement.
My opinion - the shares look priced about right, on 16.4 times this year's earnings forecast, and 14.7 times next year's. Upside may come from more acquisitions, since David Cicurel has a terrific track record of buying good companies at bargain prices. So there is a good argument for paying a bit of a premium for management.
Ed has written a fantastic article about Dart (LON:DTG) - if you haven't seen it, the link is here - highly recommended.
I'll leave it there for today, and I seem to have inadvertently duplicated today's article, so I'll sort that out now.
See you tomorrow, which will be my last report from Spain.
Regards, Paul.
(of the companies mentioned today, Paul has no long or short positions. A fund management company with which Paul is associated may hold positions in companies mentioned.
NB. These reports are just Paul's personal opinions. They are never financial advice, nor share recommendations)
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

14 comments
For those interested, Simon Thompson of Investors Chronicle is remaining positive on INL, recommending running profits in his article 'Tapping into hidden value', published 09/11/15. Simon's article adds further detail to points presented by carmensfella (above).
Simon added INL into his 2013 Bargain Shares Portfolio and published an update 07/02/14 and another 13/08/15.
(for transparency I hold INL shares)
Howard
There are quite a few valuation clues in the results statement and I have always held the view that the true NAV of the Inland assets to another housebuilder would be at least three times higher than that shown using the previously recorded valuation method.
This is one...
This outstanding set of results has been helped by a revaluation surplus of £14.5m on the existing housing portfolio at Wilton Park, Beaconsfield, Buckinghamshire where 76 houses are being held as investment properties. This revaluation should help give shareholders an indication of some of the underlying value behind Inland's stated NAV per share. These properties are being rented out on assured shorthold tenancy agreements with 31 properties going under offer to tenants in the first few months. Once all the houses at Wilton Park are let, we expect gross residential rental income on this project to exceed £1m per annum.
Then later the section on WP says....
We achieved adoption of the planning brief for the development of this site during the course of the year. This confirms the capacity for at least 300 new homes, together with commercial space and the retention of a substantial number of existing former MoD houses.
This site is our 'jewel in the crown' and is geographically situated in one of the most affluent parts of the country outside Central London. We estimate the gross development value to be in the order of £250m. Shareholders' can rest assured that we are managing and nurturing this asset very carefully.
So...
If we know the cost of the land at WP and that it has already been increased in valuation by £14.5m because of 76 houses and the overall GDV is in the region of £250m I will be very surprised if the added value with full planning consent is not at least £60m and that is if we sold off all the plots available whereas there will be plenty of housebuilding profits to be made on top if they build there for the next three to five years no doubt. Do not forget Drayton Gardens has been a five year story and most of the plots were sold ahead.
The next interims will be very interesting with the new EPRA reporting method but we may be quite a while before knowing true value on Wilton Park and planning & deals are coming through almost every month now as Inland scales up
The interest rate stability to at least the end of 2016 is also good news of course.
David
The INL FY results have just been loaded into Stockopedia. This has resulted in the StockRank increasing from 47 to 96 with significant increases in the Value (37 --> 85) and Quality (18 --> 63) metrics.
Balancing this are a couple of negative broker notes this week on the housebuilding sector which seem to be having a very significant effect on the sector's SPs.
I've looked at Inland and there's a lot to like, but are holders happy with the poor dividend (even after the divi raise) vs. the very generous exec compensation?
240k a year each for the 2 main directors but also 2 million shares per annum for hitting some very modest targets.
http://inlandhomesplc.annualreport2014.com/our-governance/directors-remuneration-report
http://www.investegate.co.uk/inland-homes-plc--inl-/rns/achievement-of-performance-targets-under-2013-ltip/201511051236167169E/
..and bang on cue shareholders get diluted by another 4 million shares for the directors, just a thought would they have hit the jackpot if Inland hadn't moved the goalposts on revenue recognition at Beaconsfield?
You can't value housebuilders on conventional metrics. The PER & divi yield, are meaningless, as it's feast or famine. They have a separate sector valuation method - build out value. It's the only sensible way to value them.
P.
Paul
I agree with your comment re build out value, albeit the larger housebuilders do appear to have a sustainable model in terms of land acquisition and obtaining planning permissions.
In that context, INL do seem to be moving a little in that direction as per the following from last week's FY results...
"Net assets attributable to shareholders were £88.8m at 30 June 2015 equating to 43.92p (2014 restated: 29.63p) per share. The major part of the Group's land bank is held as inventories at the lower of cost and net realisable value and it should be noted that the unrealised value within the portfolio of sites is significantly higher than the stated value. NAV is a key performance measure used in the real estate industry. However, IFRS NAV does not provide shareholders with the most relevant information on the fair value of the assets within an ongoing real estate company with a long term strategy. Accordingly, after consultation with our advisers, we have decided to adopt the accounting practices of the European Public Real Estate Association ("EPRA") to address this issue. Specifically, the EPRA NAV measure highlights the fair value of net assets on a long term, ongoing basis. While not recognising unrealised gains due to planning gains in the income statement, the adjusted value of trading assets and land subject to planning gains would reflect their current fair value under EPRA's NAV measure. We intend to introduce this additional disclosure when we report the Group's half year results for the 6 month period ending 31 December 2015 expected in March 2016."
This may help a little with the estimation of build out value.
Regards, Martin
I don't understand Inland either. I can only assume it's down to a view that (a) it's cyclical (b) we're reaching the end of the housing cycle in the South East (c) therefore, sell down one's position and lock in gains made over the last couple of years. The price has been weak for a few months now. On paper, it should be a great buy.
Hi Paul,
I have been following INL for some time, it baffles me the SP has not gone up on the great news on their prelim results announcement. It actually seems to be going the other way. Could it also mean the SP already had the over achievement in results baked in? I am still awaiting an article post their results. It would be great to get your opinion. (SP -3.5% 4pm)
Kind Regards
Jab
Interesting points re Bloomsbury Publishing (LON:BMY) many thanks.
I've had a look at their most recent Annual Report, and you're right, there is a nice split of revenue & more importantly profits, from their various divisions:
Drat, my computer is playing up & won't let me copy the table in here, so I've done a screenshot of the table from their Annual Report, and created a URL for it here: http://puu.sh/jcjdl/459ad6b2ae.png
Regards, Paul.
Bloomsbury is a bit of a unique publisher - yes, they do the standard B2C consumer books like Harry Potter. But they have also diversified into professional publications and publications that are somewhat more resilient.
Indeed - at work, for example, we all have digital libraries for tax and accounting standards on our desktops provided by none other than Bloomsbury. It is my understanding that the service is very reasonably priced and everyone uses the material on a daily basis with no complaints.
I therefore see no reason why the firm wouldn't continue to use the service for many years to come. Accountancy firms will always need such products and the continual changing of standards provides opportunities for Bloomsbury to keep updating the product and charge extra where new sets of rules come in to place etc.
Such revenue streams make up quite a large part of Bloomsbury's revenue and it is their stated intention to expand ever further into this sector. It is certainly not an exciting growth opportunity but the business looks pretty durable to me - people may stop buying physical books but the demand for information and reading material appears as high as ever and it is this that Bloomsbury are really selling.
Talking of Cambria Automobiles (LON:CAMB), this one has certainly rewarded the patient over the last couple of weeks. In an apparently delayed reaction to good six-month interims, on which you commented on 12 May, It has finally taken off, from 57p on 10 July to 73p today. I so nearly sold after 16 months of going nowhere!
I bought over 1 year ago, I sold out after 1 year as went nowhere. Fortunately I bought back in May, did lose a bit as the spread is quite wide. This is where momentum scores over value.