Small Cap Value Report (23 Mar 2016) - ALY, TRCS, CLL, QXT, BAR, SWP, CNKS

Good morning!
What a busy day yesterday! I added loads more companies to yesterday's report, but there were so many companies reporting, in the end I had to do brief comments on the last 8 companies added to yesterday's report. So you might like to recap on that report here.
My CEO interviews seem to be popular, so I've got more in the pipeline. Yesterday afternoon I had a long chat with the CEO of accesso Technology (LON:ACSO) (at the time of writing, I hold a long position in this share) - very illuminating too, he's so bullish about the business, and its seemingly unique opportunities for growth.
Accesso seems to have a huge moat around it once clients are signed up - the company already has c.60% visibility of its revenues for 2022! The interview is just over an hour long, which I know some people baulk at - I can't understand why, because if I'm risking thousands of pounds on a company's shares, an hour of my time to listen to the CEO is time very well spent. The link for the audio is here.
Laura Ashley Holdings (LON:ALY)
Share price: 24p (down 0.7% today)
No. shares: 727.8m
Market cap: £ 174.7m
(at the time of writing I hold a long position in this share)
Results 52 wks ended 30 Jan 2016 - the company is in the process of changing its year end from 31 Jan to 30 Jun, so this will be an extended, 17-month year. Hence today's results are called "second interim results", but are 52 week figures, so I'll treat as a normal year's figures.
The share price has already come down a lot from last summer's peak of 35p per share. So clearly the market has been anticipating lacklustre performance. That's why the price has barely budged today, on publication of lacklustre figures.
The core UK retail business performed pretty well in 2015/16, as you can see from the table below:
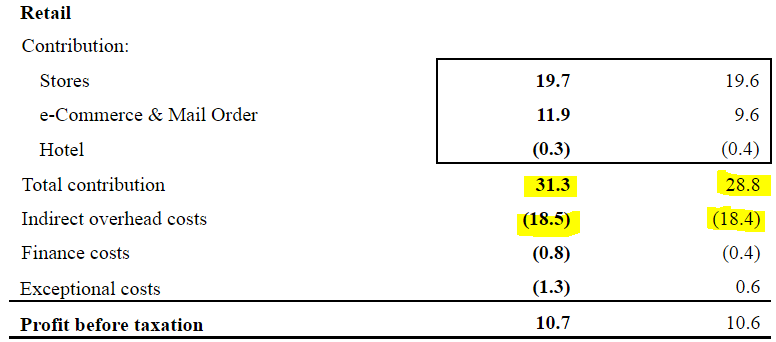
The highlighted items are what I regard as the underlying performance of the retail business. As you can see, "contribution" (i.e. the profits from the UK shops, before central overheads such as warehouse, Head Office costs, etc) rose 8.7% to £ 31.3m. That's a pretty good performance from a mature business.
Overheads were up a tad at £ 18.5m, so the net profit of the highlighted items above was an increase in profit from £ 10.4m to £ 12.8m. That's a good result from UK retailing. Note that additional finance costs, and a swing from an exceptional gain of £ 0.6m last year to a loss of £ 1.3m this year almost completely mask the good underlying improvement in profit.
Problems emerged in the biggest overseas market, Japan, and that has hurt profits at non-retail (which is mainly the group's overseas wholesaling operation);
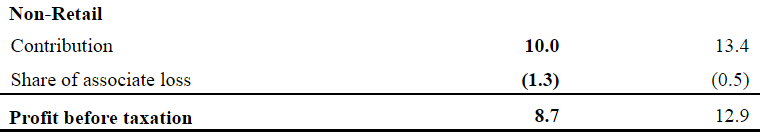
Quite a sharp drop there, which has pulled down overall group results.
Put this all into the pot, and the overall group pre-exceptional profit before tax was £ 20.7m, down 9.6% against last year's £ 22.9m - so a bit disappointing, but certainly not a disaster, is my verdict on the P&L.
Outlook - current trading looks a bit disappointing, although they're up against quite a strong prior year, but that's no excuse - LFLs should not be negative.
Trading for the seven weeks to 20 March is down 0.4% on a like-for-like basis.
It's not clear whether this just relates to the retail division, or both retail and wholesale? I'm assuming that it probably relates to just retail.
I'm interested in what the group is doing to fix the problems with its international wholesaling business, and reassuring noises are made on this;
We will continue to work closely with our partners and remain confident that these challenges will be overcome. Work continues on establishing the Brand in new territories.
The acquisition of the Group's Asian head office in Singapore will help lead our Brand expansion into the Asian territories.
At the moment, the market is not attributing any value to the group's planned expansion in the Far East. This is quite surprising, as the group has already demonstrated that its international franchise business works, and is decently profitable.
The purchase of a large freehold Singapore office block last year spooked some investors. This is why fixed assets has shot up, and also a long term bank loan has appeared on this year's balance sheet.
It was certainly an unconventional decision, but the company's finances are strong, and its balance sheet does not look stretched at all.
Franchising is a terrific way to expand internationally, as it means someone else finances all the capex, and takes the pain of any trading losses in the short term. However, the downside risk is that franchisees may go bust - as happened in 2015/16 when ALY's Australian franchisee went under, which is what the £ 1.3m exceptional item relates to. That's already known about, as was announced to the market on 11 Jan 2016 here.
Dividends - this share's main attraction is the monster dividend yield. Essentially all earnings are paid out as divis, and that has been the case for the last 5 years.
So it's pleasing to see the 1.0p second interim divi (on top of a 1.0p interim divi) has been maintained. The 2.0p annual payout represents a yield of 8.3% - pretty remarkable. Anything could happen, but there doesn't seem to be any inclination to cut the dividend, and the balance sheet is robust enough to make it look reasonably safe.
Ultimately though, the dividend payout is a policy decision, driven by the controlling shareholder(s). So it could change in the future. Some investors don't like the shareholding structure, but I've not seen anything to indicate that minorities are being disadvantaged in any way - quite the opposite, we're being showered in money, with the huge dividend payouts. I can live with that!
Balance sheet - overall looks fine to me. Note the pension deficit of £ 15.0m.
Cashflow - I don't give enough prominence to cashflow statements, which in some ways is the most revealing part of the financial statements. This one tells the picture of the year beautifully;
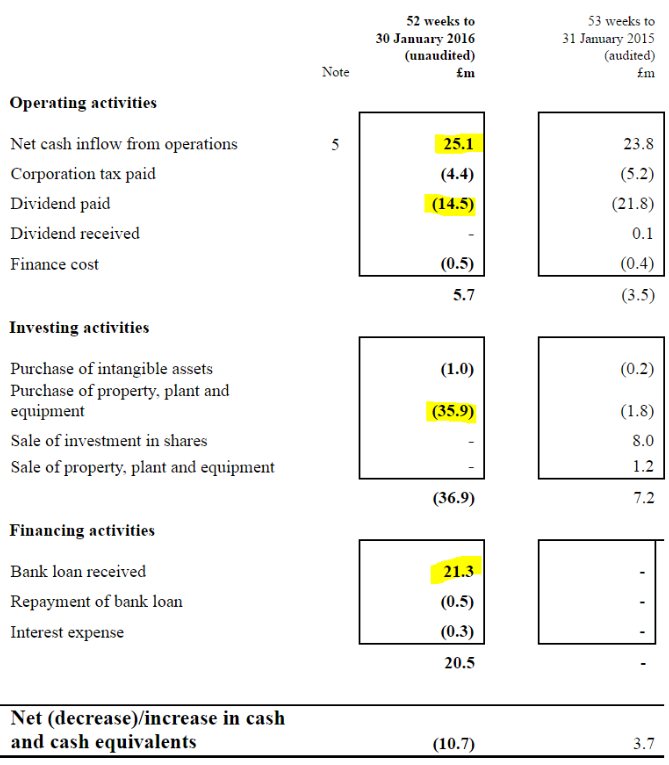
So the figures I've highlighted above describe the year's main events;
1. The business is a cash cow.
2. Paid out huge divis, but generated plenty of cash to do so.
3. Bought a massive office building in Singapore.
4. Took out a mortgage to part-finance it.
That's it, that's the year in summary!
My opinion - for me, this is a core long-term holding. Results today are a bit disappointing, and the outlook comments are not great, so I don't think there's any particular reason to rush out and buy the shares.
Having said that, where else can you find what looks to be a sustainable 8.3% dividend yield, plus potentially exciting growth plans underway (with little to no capex requirement, as being done through franchising)?
The brand has considerable value too, and at some point the controlling shareholder, who is getting on a bit now, will want to exit at the best price he can achieve. So I believe there is likely to be a nice payday here, at some point in perhaps the next 5 years? Who knows, it's icing on the cake if it happens. Meanwhile we're paid a monster divi to sit tight.
People moan that the shares never go anywhere, but if you include divis, the total shareholder return has been alright.
It's not for everyone, but personally I quite like it as a long-term holding, whilst accepting that today's figures are somewhat disappointing. The divi yield should put a decent floor under the price in my view. So risk:reward from the current price looks favourable to me.
Tracsis (LON:TRCS)
Share price: 495p (down 2.9% today)
No. shares: 27.4m
Market cap: £ 135.6m
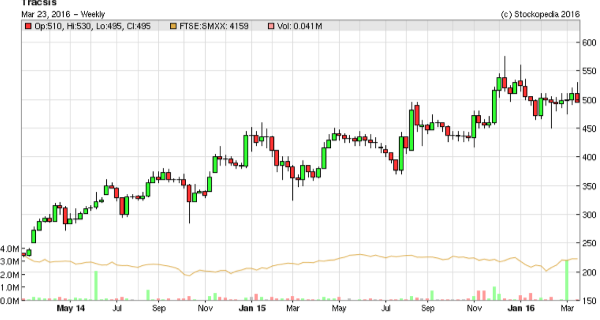
Interim results, 6m to 31 Jan 2016 - revenue rose 19% to £14.3m, reflecting some recent acquisitions. Adj. pre-tax profit was flat at £3.2m. I seem to recall that the CEO previously said that the seasonality of the group would become more H2-weighted because the recent acquisitionsin particular SEP Ltd, is a summer-orientated business. So I don't think there's any particular concern that there hasn't been any profit growth in H1, as it covers slower trading at SEP over the winter.
Most importantly, the group confirms that it is trading in line with full year expectations.
Remote condition monitoring - this is the highest margin part of the business, but only did £1.3m turnover in H1, flat vs last year. This is due to the absence of any large orders (framework agreements) from this subsidiary's biggest customer (presumably Network Rail). Therefore it's good to see the group still performing well, without it's previously biggest money-spinner doing very much business. That suggests to me that the rest of the group is trading well, and that there's interesting potential upside if this product can successfully be sold in the USA. We've been told before that USA sales are a slow-burn in terms of opportunity. Today the group updates on this;
Outside of the UK our activities in North America continue and we are pleased to announce the appointment of a second technology partner in order to expedite sales channel progress for both Class 1 freight railroads and passenger transit operators. At this point in time, interest in our remote condition monitoring technology (RCM) remains high with good potential to win further pilot projects and test sites this year. We continue to view the US rail industry as being the largest and most directly accessible growth market for RCM although the specific timing for technology adoption to material level remains difficult to predict with any certainty. Given the inherent uncertainty of timing, our overseas strategy for US RCM remains low risk in terms of financial commitment and exposure given our model of using well established domestic resellers and agents. We are also targeting other overseas markets and also non rail applications, such as monitoring of micro-turbines within the distributed power generation market.
If/when material USA sales do kick in, that could certainly be a catalyst for a nice upward move in share price.
Balance sheet - whilst still strong, the surplus cash is now effectively spoken for (EDIT: this is wrong - please see the company's comments below). So cash has fallen from £ 10.0m a year earlier, to £ 8.0m at 31 Jan 2016 - clearly still a very healthy position, and that's after making payments of £ 6.8m towards acquisitions.
However, note that new lines within creditors have appeared, namely a £ 2.8m deferred consideration liability due within 12 months, and a further £ 5.8m due after 12 months. Combined that's an £ 8.6m liability, which means all the £ 8.0m cash is now spoken for.
It's not a problem, but is a material point to note, hence me pointing it out.
EDIT: the company's CFO has been in contact, has given additional colour on the deferred consideration. I think his comments are really important, so have reproduced them verbatim below;
You are absolutely right in that the deferred consideration is a new line this year and a material one at that. The liabilities recognised are the maximum amounts payable in both cases.
Without going into the detail of both of the agreements, the deferred consideration in both cases is linked to profit targets, some of which are stretched and contingent on certain levels of profitability being achieved. So they should be self funding in that if the businesses perform as expected, then they should generate the profits and the cash to largely pay for themselves, which would mean that we still have a very strong cash position that should not really be affected by the earn out payments. If the businesses do not deliver, then the deferred consideration will not be payable. However, due to the deal structures, it is in everyone’s interests for them to succeed and for the earn outs to be paid but if not, we have de-risked for us by the deal structures we have entered into.
Valuation - broker consensus is 21.1p EPS this year, so the PER is 23.5 times - a rating that doesn't leave any wiggle room for disappointment. I think the high rating is probably anticipating some upside from future sales of RCM equipment in the USA.
Dividends - not material.
Outlook - this sounds reassuring;
Following the acquisitions of SEP and Ontrac, the Group will be significantly enlarged and will also benefit from new product development which will enhance the Group's offerings further; the benefit of which will be seen in the second half of the financial year and going forward.
Given a good start to the financial year, the Board is confident the Group is well placed to deliver full year results in line with market expectations.
My opinion - regulars here will know that I like this company, and particularly rate the CEO - whose disciplined approach to acquisitions has worked very well. What's interesting is that the group is now becoming bigger, and hence that's smoothing out performance somewhat.
It's an interesting collection of transport-related (mainly rail) technology businesses, with plenty of product innovation going on. The valuation is a bit too warm for my taste, so if I held it, would probably be tempted to top-slice at this level. However, I do still like the business, and management as a long-term proposition too.
Please note also (above) the CFO's clarification email to me, emphasising that the earn-out payments (deferred consideration) are the maximum potential payout, and should be self-funding as they are linked to profit targets. This is a really important point, so apologies I didn't pick up on it first time round.
I chat to the CEO every Nov, so here is the link to my most recent interview with him, from Nov 2015 (audio and transcript available).
Cello (LON:CLL)
Share price: 95.4p (down 1.7% today)
No. shares: 85.3m
Market cap: £81.4m
VAT Update - this sounds worrying. HMRC has rejected a £2.4m settlement offer from Cello for a VAT dispute. So it sounds as if Cello will have to increase its existing provision for this liability (which is £3.2m, to cover penalties, costs, etc).
The market doesn't like uncertainty, and the RNS today doesn't quantify the maximum extent of the potential loss. As this announcement was issued at 4:21pm today, there will probably be more damage to the share price tomorrow.
I think the company needs to update the market asap on the potential financial impact of this.
Quixant (LON:QXT)
Share price: 209p (up 10.9% today)
No. shares: 64.6m
Market cap: £135.0m
Results y/e 31 Dec 2015 - these results look excellent. The growth is nearly all organic too, as the company states that its acquisition of Densitron was the first acquisition in 10 years, and only happened near the end of the period.
Note not only strong growth, but also a very high operating profit margin;
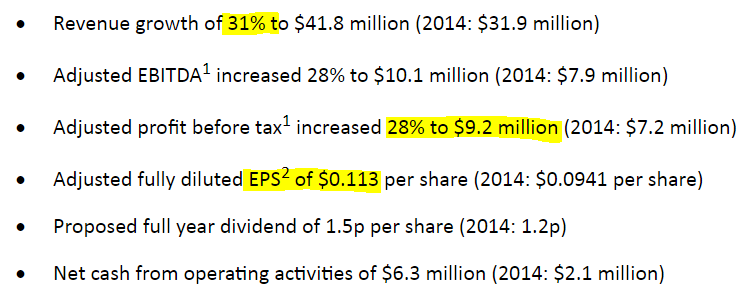
The EPS figure of 11.3c looks to be a bit ahead of consensus forecast of 11c.
Outlook - comments sound upbeat, the company seems to be on a roll;
"We have had a strong start to 2016 in both our core business and also gaming monitors and with the potential opportunities Densitron provides in other markets, I am confident the Group is well placed to deliver strong growth in 2016 and beyond."
Balance sheet - at first glance I thought debtors looked too high, but that's because it would include the figures for the Densitron acquisition, which very little went through the P&L. So it's fine.
Overall it looks alright to me. There's a bit of debt, but it looks moderate in relation to the profits & cashflows of the business.
My opinion - this looks an interesting, high quality company, which is growing strongly. So definitely worth a closer look.
Densitron wasn't anything exciting when it was separately listed, but perhaps Quixant is doing something more interesting with it?
The shares could perhaps have further to rise, based on these excellent figures? Although the valuation is already on the warm side, and could end up over-shooting, with a resultant sharp correction perhaps? There's also the question of how sustainable the rising profits are? Sometimes this can be due to large orders which may not recur, so that's an important point to check out when doing more detailed research on the company.
A few snippets to finish off with, as I've run out of time & energy after a long day.
Eclectic Bar (LON:BAR) - a potentially interesting turnaround. Luke Johnson bought into the company last year, and became its Exec. Chairman. Interim results show an improvement from a loss last time, into a small profit of £276k this time.
The balance sheet's not great, but not a disaster either. This share is really all about piggy-backing on Luke Johnson, who of course is a hugely respected entrepreneur.
I've generally found that nightclub/bars make lousy investments, so decided to sling out the small position I took in my SIPP some time ago. That said, I'm toying with the idea of buying back in, as there is now evidence of the turnaround beginning to work.
SWP (LON:SWP) - profits down, but at least it's still profitable. ULVA subsidiary has been impacted by fall-out from oil/gas sector. Although Fullflow (rainwater systems) sounds like it's trading well. Interesting comments from management about shareholder value, and interests being aligned. Risk they might de-list, reading between the lines of outlook statement. Balance sheet looks satisfactory. Is it worth the £12m market cap? Questionable I'd say.
Cenkos Securities (LON:CNKS) - I don't usually cover financials, but keep getting drawn back to this one, on value grounds. It has a remarkable track record of dividends & share buybacks. In both 2014 and 2015 it benefited from one-off large transactions, being The AA, and BCA Marketplace. I'm tempted to revisit this one, once it has stopped falling.
All done for today! See you in the morning.
Regards, Paul.
(usual disclaimers apply)
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

33 comments
I am surprised that there is no comment on the ALY RNS yesterday where over 100m shares are pledged as collateral for a loan.
Hi tiswas
I'm assuming in a sense it's old news as everyone knew his divorce was going to be painful so this looks like just his chosen way to maintain exposure to Laura Ashley Holdings (LON:ALY) upside whilst providing an alimony pot?
Paul, many thanks for the link to your interview with accesso Technology (LON:ACSO) CEO, does sound very promising, I'm now a long holder. Also thank you for the Tracsis (LON:TRCS) review.
middle east shipyards, dealt with a few, dodgy to say the least, i'd avoid
I'm not especially familiar with the company, but it looks as though they may suffer from the view that their new business flow is lumpy and unpredictable. Yes, the producers will keep drilling in the shallow water ME but pressure on Capex might lead them to sweat their rig assets for longer delaying new orders etc., for Lamprell (LON:LAM) . Presumably they themselves have pretty high overheads so if running at less than full capacity there is likely to be significant cash burn. This said, this already seems built in to the share price so I agree there seems a good risk:reward profile, especially if you think there is an oil price recovery on the way.
Gus.
If you can update on Lamprell when you get a chance, it would be much appreciated.
Hi grym02,
I'm reporting on absolutely loads of companies at the moment, as we're in the busy season.
So once the article's signed off for the day, that's it, I'm done!
There are only so many companies one person can cope with. I do about 500, which is hard work.
Perhaps you could take up a bit of the slack, and tell us why you think Lamprell is good or bad? Just a couple of sentences is good. It's a team effort here So it's much more useful when people say something about the stock they are interested in, rather than just asking me to do the work for you, which is a bit annoying to be honest, when I'm busting a gut to cover as many companies as I can already - so asking me to do more, after already having spent all day & all evening writing the above, is a bit annoying. I'm not a machine FFS!
Regards, Paul.
LAM LN: Leading shipyard in the Middle East, where the NOCs are ramping production low oil prices. 2016 will be slow year, but can still generate EPS of 0.10 GBP per share, or 10% yield on a trough-ish earnings number. And tax advantaged status means zero tax rate so EBIT = NOPAT. In addition, company has net cash of 201m USD or almost 40% of the market cap. This will only grow due to the NWC unwinding as part of PoC accounting (they have done a lot of upfront work). so even if a chunk of that cash is needed to run the business, LAM trades for less than 8x EV/NOPAT. 2016 revenue are 90% covered by current projects. 2017 is a mystery, but doubtful that they stop drilling in the Middle East no matter what happens to oil.
Curious if you or others see it differently?
Hi Paul,
Thanks for chat with Tom Burnet at accesso Technology (LON:ACSO). The introduction of ticketing solutions to Asia sounds very positive.
We're just testing some new tickerize fixes.
888 Holdings (LON:888) BP (LON:BP.) Vodafone (LON:VOD) £10m £174
We've changed the £XYZ to work for characters or digits and only for UK stocks. We'll figure something out for international stocks later.
@Paul give it a go and see if it works better. My test seems ok
Actually - it's not released yet. Please wait a mo.
Hi Ed. could you have a look at Sports Direct while you are at it please? There are three SPD's at the moment, two of them in the UK. Only one of them ever seems to be talked about ...
Thanks,
Gus.
Re. Tracsis (LON:TRCS). I like this company a lot and I am looking for a reason to invest.
For the full year the company expects to make eps of 21p. Today's HY report shows a normalised eps of 4.04p. So for the results to be in line, TRCS has to make some 17p in 2nd half year.
Yes, the 2 acquisitions SEP and Ontrac are expected to fire on all cylinders in the 2nd half. But my back of fag packet calculations say it will be a tall order to make 17p in the next 6 months, from base business plus the 2 acquisitions.
However far be it for me to bet against John McArthur, who I rate to be one of the best CEO in the business. So I am going to take the coward's way out, and sit this one out.
Sorry Paul was meant to be a thumbs up but my hand was shaking. Thanks for the write up on ALY.
Friday 8th January, John McArthur, Chief Executive, disposed of 120,000 ordinary shares of 0.4p each ("Ordinary Shares") in the Company, at an average price of 515.9p per Ordinary Share.
Worth including in your opinion piece.
apad
Paul, I noticed you didn't comment on SEE yesterday in the end. What's your view on their premium placing with VSI, looks like VSI will manufacture their new 'reduced cost' fleet product, VSI are Malaysian based and have a link with Dyson.
I didn't get round to commenting on Seeing Machines (LON:SEE) yesterday. However I did look at their deal, with a Placing (at a premium) from a technology company. Looks very promising I think. Certainly it's an important validation of their technology & its potential I think. Not one I currently hold.
P.
Hi Paul,
Any thoughts about Cenkos Securities (LON:CNKS) ? FY results are out today, and I can't really understand why the shares are down 10%, since everybody knew 2015 would not be as good as 2014. Revenues for the FY are down 14% vs 20% in H1, so I think they are doing pretty well, and the yield is over 10%. Would really like to read your interpretation of those results, or anything strange yoy may have spotted.
Thanks as always for the reports!
By the way, I think yesterday's acalarations were not needed, you have every right not to publish reports when you don't want to!!
Thomas
very bullish price action with ALY... complete reversal on the day with higher than average volume. Guess the results when digested were more palatable.
From a technical POV this may well break-out towards 28p
I am a holder for the divi and thought about adding this am on weakness...didnt expect such a quick bounce!
I continue to sit on the fence with Laura Ashley Holdings (LON:ALY). If you look back through past years' annual reports the company has always talked about growing internationally and it never seems to happen. Having bought my first home recently I've been on a furniture shopping expedition and I have to say I am unimpressed by their offering which looks a lot more expensive and more old fashioned than similar competitors, although I appreciate I may not be the target market. The yield is tempting though.
On a different note, I see that Sports Direct International (which has been discussed on this SCVR before) has been hit a lot over the last 48 hours. It says today that EBITDA is likely to be more towards £380m for the year though I always struggle to remember what EBITDA actually is. The year to April 2015 was EBITDA of £380m as well though and that resulted in a reported EPS of 40p. So it is potentially good value? Do any readers have any views?
Not a holder of Sports Direct but the share price is down heavily again today. Great set of brands and even at the lower end of expectations, the suggested level of earnings make it look really cheap. Added to this, given the hubris surrounding Mike Ashley over both SDI and NUFC, at some point he might really throw his toys out of the pram and sell his stake in the latter to take the former private again, so there might even be a bid premium In the future. Thinking of taking a nibble at these levels.
Gus.
Update: Couldn't resist. Just purchased an entry level investment at 361p. What swung it for me was the recent RNS suggesting Odey AM was increasing its holding. First share I've looked at where they are going long rather than short
I always worry about the core shareholding in this business and where it is based. Not for me. Owning an office block is not why you sell dresses. I suspect it is more about having a bolt hole if Malaysia has a crisis and is nothing to do with the business.
Any news on yesterday's promised SEE report? :-)
Laura Ashley Holdings (LON:ALY) I wonder if the exceptional charge of £1.3m following its licence partner in Australia being placed into voluntary administration is something that may become an exceptional gain in the near future.
The sale of the (Australian) company is 'as a going concern' There are still 25 stores continuing to trade around Australia.
Carcosa, this article refers to the reasons for the collapse of the licensed Laura Ashley business in Australia:
http://www.ragtrader.com.au/news/laura-ashley-the-shocking-reason-behind-its-collapse
The chance of recovering the debt would seem slim.
Re Laura Ashley Holdings (LON:ALY) and the £1.3m debt from its Australian franchise partner going bust. I haven't looked into the detail, but normally in these situations, unsecured creditors get nothing. Occasionally there might be a small payment (a few pence in the pound), but that's the exception rather than the rule.
The business will usually resume trading, but under a new limited company, which does not inherit the debts of the old company, it's a clean sheet.
So I would work on the basis that the £1.3m exceptional charge is an unrecoverable bad debt. It's not material anyway, so forget about it.
In many ways this is a much cleaner way of doing things for ALY than it operating the stores itself. When the franchisee goes bust, it kills all the lease liabilities for the shops, which is a good thing. Therefore although ALY has been stung with a bad debt, imagine how much greater the losses might have been, if it had operated the shops itself, and been liable for years of rental payments on loss-making shops (look at the mess French Connection (LON:FCCN) has got into on that front).
So I like the franchising model that ALY uses.
Regards, Paul.
Paul,
Agree the ALY results were disappointing. I'm still confused by the need to have a couple of lossmaking hotels - it seems like someone's vanity project to me.
As for the terse single sentence outlook and current trading statement, you can see why it's easy to get the impression someone doesn't give a toss about other shareholders. What are they including and excluding in the like for like figure? Some explanation would be nice, especially since they have 12 less shops in UK retail than 12 months ago. Does the -0.4% figure exclude shops that have been closed and include shops that have been opened, or not?
I still don't understand the reasoning behind the Singapore office purchase and the price has fallen ever since it was announced. One of the other downward pressures on the share price must be the divorce case of Khoo Kay Peng who holds 44%. If his other half (of 45 years) ends up with a 22% holding in ALY and doesn't fancy equity in her ex-husbands companies it could create the mother of all share overhangs. It would certainly be another way to kick him where it hurts!
I'm still holding, but only for the dividend. It's a good job that has been held but if it ever gets cut there is little reason to continue holding.
All the best, Si
Not sure if you picked up on Jane Bolacha's recent thread, but it looks as though Laura Ashley Holdings (LON:ALY) / MUI group's plans are to expand the branded UK hotels side of the business.
http://www.stockopedia.com/content/small-cap-value-report-18-mar-2016-124184/?comment=30#30
Gus.
Paul, I see Tracsis (LON:TRCS) put out half year statement today, to me it looks disappointing, revenue up 19% but pretax profits flat. Forecast for the year is +56%, so they struggle to meet that? I'm no longer a holder I sold out after the directors sold a lot of shares. Your thoughts would be welcome.
Re. Laura Ashley Holdings (LON:ALY) Showing the dividend paid within the operating cash flow is unusual/ unconventional at least in the UK.
It is a large amount for ALY and works against the company's presentation of accounts. OCF is actually £20.2m and not £5.7m. It similarly distorts FCF.
As you can see in the StockReport, the numbers are artificially low.
Hi Ramridge,
Yes that's right. The way Laura Ashley Holdings (LON:ALY) presents its cashflow figures, the post-divi cashflow figure is picked up by Thomson Reuters. I've flagged this before to them, but nothing changed.
It just shows, there's no substitute for DYOR, as anomalies can occur with figures. Drilling down into the detail shows a very different picture - ALY is actually a terrific cash cow, even in a bad year.
Regards, Paul.
Laura Ashley Holdings (LON:ALY): no doubt I'm being overly-cynical, but the thing that worries me with these foreign-controlled companies is that things seem to go wrong one excuse at a time.
Hi Paul,
I think there's a glitch on Stockopedia related to the Market Cap value for stocks in some of the reports you've written. The current write up of Laura Ashley Holdings (LON:ALY) above refers to Gemini Investment holdings in the market cap field.
Best wishes,
Imran.
Hi Imran,
Thanks, I didn't spot that one. There's a problem in that the widening international shares covered by Stockopedia now means that it's picking up numerical tickers, if they happen to randomly relate to a financial figure I've used.
Am trying to train myself to put a gap between the £ and the number, which stops that happening, but I keep forgetting. Doh! There are just so many things to remember, it's no wonder I have to have a lie down after lunch these days LOL!
Regards, Paul.
Hi Paul. Excellent and thorough review of Laura Ashley Holdings (LON:ALY) many thanks. Also a long term SIPP holding for me. Some aspects of the business are rather uncomfortable, however, I like the brand strength and am prepared to be patient.