Small Cap Value Report (24 Feb 2016) - GRA, TSTL, MCB

Good morning!
Grafenia (LON:GRA)
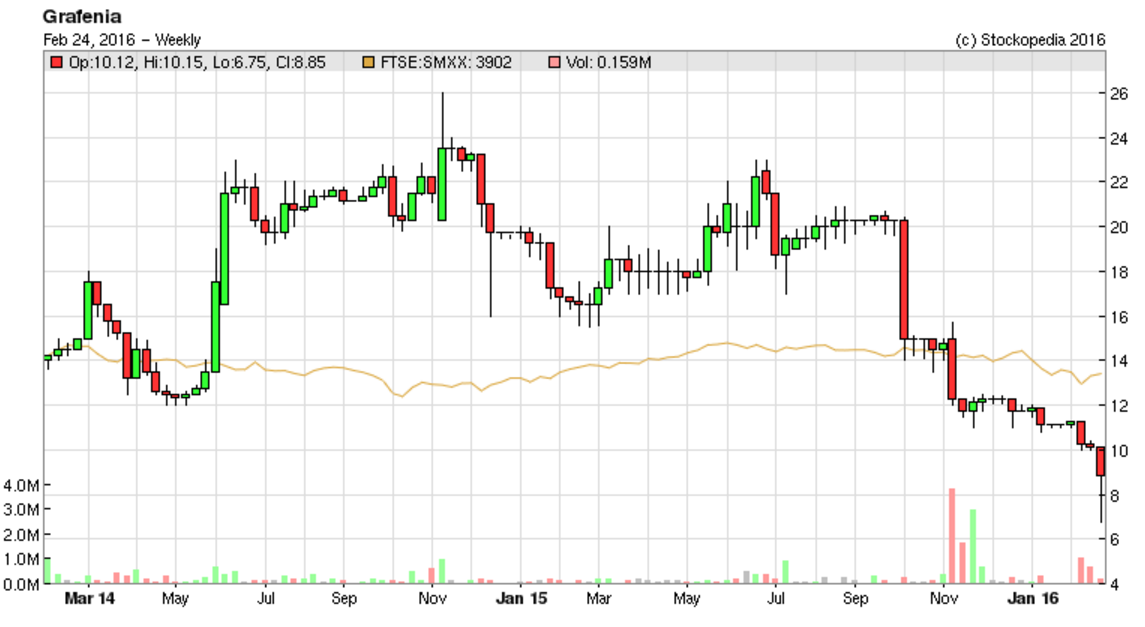
Share price: 8.5p (down 16.1% today)
No. shares: 46.1m
Market cap: £3.9m
Profit warning - I hadn't realised that the market cap had dropped this low, so will stop reporting on this trade printing company from now on.
Today's update explains the structural problems operating in this sector, and what makes it such an unattractive place to invest;
Our markets have never been more competitive, with established players, aggressive pricing from new European entrants and domestic commercial printers diversifying into the trade print sector. We are continuing to experience downward price pressure, which has intensified in the second half of the financial year. To combat this, we have increased our promotional activity, incentives and selective discounting.
Note how competitor Tangent Communications (LON:TNG) recently said it is leaving the stock market - with a takeover bid from management, although I note there was a higher competing offer subsequently announced. Both these companies are now too small, and struggling, to justify being listed. So I suspect Grafenia may not remain listed for much longer - the threat of de-listing can itself be a time-bomb under the shares, so personally I would be tempted to ditch them if I held, just to be on the safe side.
Due to the above factors, there's a nasty impact on profitability;
As a result of this and the challenging trading conditions, it is the Board's view that our full year results will be significantly below current market expectations.
Profits have been on a steadily downward course for the last 6 years, so continuing the trend, it looks as if y/e 31 Mar 2016 won't be much above breakeven in all probability.
Outlook - there is some more upbeat-sounding commentary on initiatives to improve performance, under the new CEO (who incidentally has been buying shares, and now holds just over 2% of the company).
Balance sheet - I've checked back to the last interim report, and the balance sheet looks alright to me. So this is not a financially distressed company, in my opinion.
My opinion - the company operates in a horrible, low margin, highly competitive sector. With profits trending down to zero, there's little to attract investors.
My main worry is that the company could well de-list, now that it is really too small to justify the costs & hassle of a listing. That would be an instant 50% off the share price if it happens. Why take that risk?
Historically Grafenia has paid very generous dividends, but those are also falling - the interim divi was halved from 0.5p to 0.25p. So it's probably best not to place any reliance on receiving more divis.
The shares are now just a punt on the new CEO turning the company around, and there are some interesting comments in the narrative today about new products & services. So who knows? There might be life left in this company, but it's really one for special situations investors only at this stage, due to the high risk of a de-listing.
Tristel (LON:TSTL)
Share price: 125p (down 14.0% today)
No. shares: 42.2m
Market cap: £52.8m
Interim results to 31 Dec 2015 - this is quite a crowded trade - shares in this manufacturer of infection control products are popular with private investors, and rightly so because the company has demonstrated a good track record of profitability, and growth. However, the trouble with crowded trades, is that the shares can end up being priced to perfection - leading to disappointment on results day, as we've seen today.
Revenue is only up 8% to £8.0m. That's not enough growth, for a share on a growth company rating. Growth in the UK market seems to have stalled. Overseas growth was better, at 20%. The company's 10 year growth trend is 18% p.a.
Gross margin was excellent, rising from 69% to 71%
"Very tight control on costs" led to profit before tax and share-based payments rising 36% to £1.5m.
Overall then, this trading performance doesn't inspire. Growth slipping from 18% to 8% is clearly disappointing, even if short term profitability has been maintained through cost control.
Share-based payments - this has clearly spooked some investors, and I don't blame them. A £1,015k share based payments charge is booked in H1, which consumes two thirds of adjusted operating profit, taking actual operating profit down to only £455k, down 55% on H1 LY. This just doesn't look good, whatever the reasons.
Balance sheet - excellent, no issues here at all. The company has £4.3m in net cash, or 10.2p per share, which is worth bearing in mind when valuing the shares.
Outlook - this is another fly in the ointment, in terms of short term sentiment (if not long term value);
Whilst revenue growth in the period was solid at 8%, it was below our ten year long trend of 18% per annum. However, we have many irons in the fire - both in terms of geographical expansion and new products - which will generate further revenue growth in the years ahead.
Margins, costs and cash are all being managed with strict discipline, and growth in profits and earnings per share are satisfyingly on target. Whilst the second half of the year is typically more profitable than the first, with the increased investment in new products and the 510(K) submission we expect a more equal split this year.
The outlook for the Company continues to be very promising and we remain confident for the full year.
It's good that the company is managing investor expectations down for a more equal split of profits between H1:H2 this year. Those short term costs could of course generate stronger future growth - the US market in particular is the big prize the company is hoping to break into.
Broker forecasts - The current year sees a forecast of 5.2p adj. EPS (revised down 2% today). No particular problem there. However, the 2016/17 forecast has today been revised down a whopping 20%, to 5.6p. (broker figures quoted are from FinnCap. Note that Equity Development has also issued revised figures today, available on their website).
Personally I wouldn't be comfortable with a PER over 20, so that equates to a share price of 112p, or about 10% below today's already reduced price.
My opinion - the increased costs of gaining US approvals doesn't concern me that much, because that could turn out to be a very good investment for future years.
However, the fairly pedestrian 8% revenue growth (suggesting that maybe the main UK market might already be saturated?) is more of a concern. Growth companies have to grow reasonably fast, to justify a rich PER. The growth here isn't enough at the moment.
Add in excessive share-based costs (which we can't just ignore - it's another form of employee remuneration - so that is a very real cost), and I can understand why some investors took fright this morning.
For me, the price is a bit too high now, given fairly uninspiring results - OK adjusted profit was up nicely by cost control, but it will need stronger top line growth to get much further. I appreciate though that long term holders of the stock might be perfectly happy to sit and wait for (hopefully) US approvals to come through - later in 2016 possibly (EDIT: likely to be mid-2017, according to a note today from Equity Development) - which could propel the shares upwards again.
So overall, I would say a bit disappointing short term, but the longer term upside still looks good. Also note that the dividend yield of over 2% isn't bad for a growth company - so investors are at least being paid to wait. Note that a 3p special dividend was paid in Aug 2015 too, a healthy sign.
Webinar details - here is registration link for a webinar with Tristel management tomorrow, starting at 1:15pm, so best to sign in shortly beforehand.
Also, please see the comments section below, where Tristel's PR - Paul McManus - has helpfully posted details of a meet the management event (also tomorrow) in London. It's great to see a company reaching out to engage with private investors both in person, and through a webinar, especially after results that have clearly disappointed somewhat. Let's hope more companies follow this lead - I'm very keen to encourage this kind of engagement by companies and private investors.
McBride (LON:MCB)
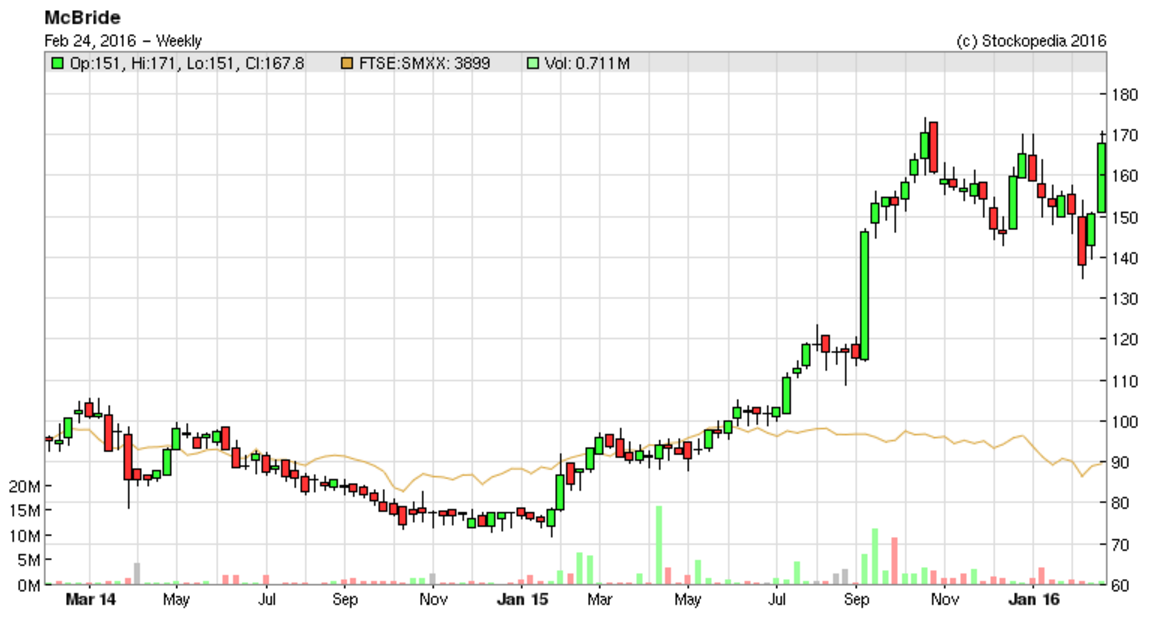
Share price: 167.4p (up 8.3% today)
No. shares: 182.2m
Market cap: £305.0m
Interim results to 31 Dec 2015 - there's been a decent move up in share price today, so the market must like these half year results from this manufacturer of household & personal care products.
I last reported on the company here on 8 Sep 2015, noting that its results for y/e 30 Jun 2015 were good, and that a convincing turnaround was underway. Although the balance sheet displeased me, with too much debt, and a pension deficit.
Today's results look really good. Bear in mind that the company is radically reducing the number of product lines it makes (by about 30%), in order to concentrate on efficiency, and higher margin products. That strategy is clearly working (remember these are just 6 month figures);
Revenue - down 5.6% to £344.1m, but up 0.4% in constant currency. That's fine, as you would expect revenue to be flat or falling during this kind of restructuring.
Adjusted operating profit - up 40.8% to £17.6m (up 57.1% in constant currency) - a very convincing result.
Adjusted operating margin - up 3.4% to 5.1%, again an excellent improvement, really impressive for this type of business. It's unusual to see such a big leap in this sector. Perhaps there are favourable raw material price falls in play also? Note that the company is targeting further improvements, to reach 7.5% margin eventually.
Broker forecast - a key broker has upgraded this year's EPS from 10.1p to 10.9p, and 2016/17 also upgraded from 12.8p to 13.6p.
Net debt - has reduced by 6.6% in the last year, but is still substantial at £86.3m. As usual, management say that their level of debt is conservative relative to earnings. No it isn't!!
Gross bank borrowings of £114m seems a lot to me, compared with forecast £28m profit before tax this year. Although given the improving trading, I'd say net debt of £86.3m overall doesn't look a particular problem. Bear in mind though that the bank might take a very different view when the next credit crunch happens - and bank share prices are telling us that maybe it's already happening, or in the pipeline? So I'm wary of getting into shares of any highly indebted companies right now.
I like that McBride states what it's bank covenants are, and confirms that it is "comfortably within" these. So on balance the situation looks alright, but it's definitely not conservative, as management repeatedly, and wrongly (in my view) state.
The Group's funding arrangements are subject to covenants, representations and warranties that are customary for unsecured borrowing facilities, including two financial covenants: Debt Cover (the ratio of net debt to EBITDA) may not exceed 3:1 and Interest Cover (the ratio of EBITDA to net interest) may not be less than 4:1. For the purpose of these calculations, net debt excludes amounts drawn under the invoice discounting facilities. The Group still remains comfortably within these covenants.
Pension deficit - the accounting deficit is £30.7m. However, the triennial actuarial deficit (which are usually higher) is £44.2m. A revised deficit reduction plan has been agreed, and this has resulted in a big increase in contributions by the company, from £0.4m p.a. to £3.0m p.a. with effect from 31 Mar 2015 (so already in place).
Whilst not necessarily a deal-breaker, in terms of whether or not to buy the shares, an annual cash outflow of £3m p.a. is actually quite material, as it's money that could otherwise have been paid to shareholders in dividends. So investors definitely need to adjust their valuation of the shares to reflect pension deficit payments.
Expectations were that pension deficits would sort themselves out when interest rates rose. Yet here we are, 8 years on from the GFC, and if anything, expectations of rate rises in future seem to be disappearing off the horizon. So pension deficits are likely to remain a problem, or get worse, as in this case.
Outlook - very pleasing;
For the second half year, current expectations are for constant currency underlying revenues to be slightly lower year-on-year, in line with market conditions.
The start of the impact from the customer choices project, planned during our first half year, is expected to reduce second half revenues by an additional £6.0 million.
The ongoing actions of our "Repair" phase are expected to provide further progress in profitability, despite the backdrop of lower revenues. As a consequence, the Board is now expecting full year results to be modestly ahead of its previous expectations.
So modestly ahead - hence the broker upgrades today. Excellent stuff, really impressive, this all smacks of very good management, and gives confidence in the company.
My opinion - it's not something I would buy shares in, as the balance sheet is too weak, and being a supplier to supermarkets means that profits are always going to be squeezed. Sure, the company has done a terrific job in turning itself around, but whether the 5%+ operating margin can be defended, against relentless customer attacks (remember that supermarkets generally are making hardly any money at all right now, so they are desperate), is the big question mark.
Overall though, hats off to management for executing a very impressive turnaround, that has been been reflected in a buoyant share price. Is there more upside? Possibly. Investors who don't concern themselves with balance sheets might decide to chase the shares up to the 200p level in due course? I could see that happening. I'm usually too cautious with this type of share, so there may well be more upside to come.
Note that the Stockopedia black boxes like it, with a StockRank of 93.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

25 comments
Thanks herbie47... Yep, sold BUR far too cheaply in hindsight. Sold many other shares even more cheaply too. Nonetheless I have done alright over time, though I admit I am not the greatest investor out there. I simply write my blog for my own benefit as I feel it helps the thought process.
FWIW, Paul Scott has just issued his SCVR fund performance for 2015. Up 11%:
http://www.fundamentalasset.com/wp-content/uploads/2015/10/SCVP-2015-Q4-Report.pdf
So using that as a benchmark I think I did alright.
Thanks for that information, had not seen it before, just back from holiday so much catching up to do. Surprised Paul was only up 11% last year. Yes 18% is good.
I do hold many of your shares and some on your watchlist. I would be interested to know why you held off buying some such as Ab Dynamics (LON:ABDP) and Bioventix (LON:BVXP). 2 of my better performers last year although I have sold ABDP now and BVXP looking to top up if it falls anymore.
Since switching to Stockopedia ...
23% for 2015
22% for 2014
33% for 2013
Currently down ~4% in 2016, though signs of strong recovery in high quality stocks coming and currently hedged with super short positions on FT100 and DAX
#justsayin #findasystemthatworksforyou
Best of luck
Phil
Tristel (LON:TSTL) I see 4 directors bought shares yesterday, 1 director has over 25%, someone said directors do not hold many shares in the company but I can't find the comment now.
Him
Just listened to the Tristel (LON:TSTL) webinar hoping to get some answers to above. Interviewer was pathetic - No mention of share price collapse, nor £1M share payments - Hopeless.
Was a bit surprised by the results. Did notice the negative FX impact on their sales in Germany, their largest overseas market. This negative impact is being reversed with a vengeance, may even be positive in the coming half year. Thanks Boris.
Hopefully they can become very competitive in overseas markets. They can either reduce prices to grow market share or increase margins. Not sure how price sensitive their products are, but likely to be insensitive.
I can see why they are using the German subsidiary to expand into other continental markets
Very interesting analysis of Tristel (LON:TSTL) results especially options by Maynard Payton:
http://maynardpaton.com/2016/02/24/tristel-these-results-were-a-letdown-and-i-have-been-selling/
Nigelo/Ian,
Thanks for your comments and feedback.
Commentary from Maynard Payton is interesting. As he points out, the RNS suggests that £1m expense appears to cover both the long term scheme that vested 35 employees with 793,000 shares in the last 6 months (not sure at what price) as well as the new Exec scheme that only seems to cover the CEO and CFO and appears to grant shares at 1p exercise. Certainly seems a red rag to a bull with Maynard who is pretty damning about how the share price might have been artificially ramped with recent control of news flow to stay above the required 134p options vesting threshold.
Should make tomorrow's results Webinar quite spicy!
Gus.
"Certainly seems a red rag to a bull with Maynard who is pretty damning about how the share price might have been artificially ramped with recent control of news flow to stay above the required 134p options vesting threshold.
Should make tomorrow's results Webinar quite spicy!"
Yes, I have submitted the following questions to TSTL's management for the webinar. Let's see what gets asked and what are the responses.
1) 2017 revenue target: The previous two results statements had cited a 2017 revenue target of £20m — implying c15% per annum revenue growth. No mention was made of that revenue target in yesterday’s results. Has that £20m target now been dropped? And if so, what is the revised 2017 revenue goal?
2) UK revenue: During the October 2015 webinar, management anticipated further organic growth in the UK. Particular quotes included a “huge opportunity” in ophthalmology and “growth in all areas, UK and overseas, continuing in the short term, in the next couple of years”.
So what has happened since October’s bullish tone? UK revenue appears to have stalled. Do UK hospitals no longer need many more medical wipes, surface disinfectants etc?
It would be very useful if management owned up to what exactly has occurred in the UK, as well as disclose the UK revenue figures for wipes, surface disinfection and ‘other’ for H1 2016 vs H1 2015. The October 2015 webinar did divulge the figures for FY 2015, which were £5,090k for UK wipes, £1,169k for UK surfaces and £1,973k for UK ‘other'.
3) AGM statement: December’s AGM statement did not reveal that first-half revenue had advanced by 8%. However, AGM updates for 2014 and 2013 did reveal the revenue advances for those half-years. So can management explain why it delayed disclosing the below-expectations revenue advance until these results, when the figure should have been known (and revealed) at the December AGM.
(A cynical shareholder may think that the delayed disclosure was due to management trying to keep the share price above 134p to collect certain options).
4a) FDA approval: Can management confirm that FDA submission is still on track for June 2016 and an outcome is still on track for June 2017?
4b) FDA approval: Can management outline the possible reasons why FDA could REJECT its submission and the likelihood of such a verdict.
5) Share-based payments: Equity Development understand the share-payment charge will reduce to £100-200k/year. Is that management’s understanding, too?
5b) Share-based payments: Was the full cost of the senior management option scheme agreed in April 2015 all expensed in H1 — despite the share-price condition not being met until after the period on 6 Jan? The statement does not make it clear. Some clarity as to what was expensed in relation to this particular scheme — and how much more of it there is left to be expensed — would be useful.
6) Underlying dividend: It seems the current-full-year dividend will be 2.85p — just 5% ahead of the payment for 2015. Can management explain the pedestrian payout uplift, especially given its comments of a “very promising” outlook in the statement.
7) Market size: The preliminary results presentation given during October 2014 claimed the instrument decontamination market into which Tristel then sold was valued at £91m.
The £91m value was based on 32.56 million procedures throughout Western Europe, China/Hong Kong, Russia and Australasia, which each procedure valued at £2.80.
Can management provide an update to the £91m market value? Or at least some rough guidance as to where the estimated 32.56 million procedure number and £2.80 procedure value now stand.
8) City speculation about handsome licensing income: The Equity Development note published at the time of the December AGM referred to a multi-billion consumer disinfectant sector, a “major break-through in household cleaners" and speculation that Unilever or Reckitt Benckiser “would pay handsomely to license this proprietary technology”
Can management explain the “major break-through” and whether there is a genuine likelihood of any handsome licensing deal with Unilever etc.
If Tristel does not answer at the webinar you can always email your questions to the ceo personally, and tell us here what outcome you get
Interesting article, I don't know him although I have read a few of his articles now. His 2015 performance is not bad but not as good as many on here. I see he sold out of Burford Capital (LON:BUR) last year at around 120p, now 216p, so me his opinion does not carry much weight.
Disclosure I hold Tristel (LON:TSTL) shares and topped up on recent falls. I agree about the share payment scheme which I dislike.
Re reading the RNS, it is not entirely clear whether the £1m share payment cost is solely attributable to a benefit for the two top execs or for the wider Group scheme that has been in existence for several years and appears to have hit vesting thresholds based on decent share price performance in the past 12 months. It doesn't appear to be broken down in the notes - a cynic might argue to obfuscate the fact it is building the senior execs' package - so needs more enquiry that will inevitably come at forthcoming meetings with fractious investors.
Pending clarification, I'm inclined to give the company the benefit of the doubt for the time being and managed to top up sub 110p per share earlier today. May be another falling knife, but I feel it's been oversold in a generally poor market day.
Gus.
Gus, You are more optimistic than I am. I looked back and noted in an August statement mention of only 2 directors:
Tristel plc , the manufacturer of infection prevention, contamination control and hygiene products, announces today that Paul Swinney, CEO and Elizabeth Dixon, Finance Director, have been granted options over 636,567 ordinary 1p shares under the Tristel plc Performance Share Plan 2015. The options are exercisable at 1 pence per share subject to certain profit objectives being met, or the share price of the Company being equal to or greater than 134p per Ordinary Share for a period of 30 consecutive dealing days.
The options are exercisable for a period of 3 years from date of vesting in 3 equal tranches following publication of the annual results. The first tranche will vest, if performance conditions are met, on publication of the results to 30 June 2016.
Ian
Additionally there is a Webinar for Tristel (LON:TSTL) tomorrow:
https://attendee.gotowebinar.com/register/3054205079824371458
If anyone is interested in finding out more about Tristel and hearing their results presentation directly and meeting the management, there will be a briefing by CEO Paul Swinney and FD Liz Dixon open to all investors / potential investors tomorrow evening (Thursday 25 February) at No.1 Cornhill, London, EC3V 3ND from 5.30pm for a 5.45pm start, which will be followed by drinks and canapés.
If you would like to register to attend either presentation, or require further information, drop us an email on tristel@walbrookpr.com
Paul McManus (Walbrook PR Ltd) - Financial PR to Tristel plc
I liked more the old picture... hopefully we'll see it again when the market is up again
I think the most important news of the day is Paul's new picture!
Is that really you Paul or Richard Osman from Pointless? They say everyone has a double somewhere.....
Hehe, I'm glad you like the new picture - we had a proper photoshoot and everything at Stockopedia's glamorous Oxford office. We chose this one because I looked suitably imperious, and the double chin was minimised, either with clever lighting, or airbrushing lol!
P.
"photoshoot" - are you sure you don't mean "photoshop"? Sorry, couldn't resist.
Twitter behind the times as usual and still showing the old photo.
Paul,
Agree the £1M Tristel (LON:TSTL) share based payments to the 2 senior executives looks terrible because it was only set up in August last year and has such a huge impact on H1 profitability. At the very least these 2 should have deferred or spread out the cost more. I cant help thinking they are putting themselves before shareholders. Sold my Tristel (LON:TSTL) holding 1st thing this morning and I am glad I am out. Ian
Hi Paul,
In terms of Tristel, I believe Equity Development released a note this morning indicating EPS for 2016 is 5.7p and for a revised figure of 6.2p for 2017. Out of interest where did you get the 5.6p figure from. Was this a different broker note?
Disc: I don't have a position in Tristel (LON:TSTL), but trying to better understand the company.
Best wishes,
Imran.
Hi Imran,
The Tristel (LON:TSTL) figures I worked from are from today's FinnCap note.
I'll update the article now to make that clear.
Regards, Paul.
Tristel (LON:TSTL) - Equity Development today upped their FY17 numbers from 6.93p to 7.1p (pre SBPs and US investment outlay), or from 6.1p to 6.2p (pre SBPs, post US outlay). I assume the downgrade you talk about must be from the finncap figures (the other covering broker)?
The H1 revenue growth was a little under forecast, but the gross margin is higher than expected. The UK slowdown is no surprise if you graph the UK revenue figures over the past few results statements. The next stage was always about international growth. Perhaps it is only today that the reality of that is sinking in (that, and the Simon Thompson effect as this was a long standing recommendation of his).
Taking a leaf from your book Paul, and after seeing Lord Lee speak at the FT recently ( he made a point of saying investors should take time to get to know the management of companies on their watch list) I decided to contact the CEO at Somero to arrange a meeting.
He has agreed to meet me when he is over from the US in two weeks time. Good to see CEOs who are open to engaging with private investors. Well done Somero! Possibly raises a flag for others that it is possible to engage directly with management