Small Cap Value Report (24 Mar 2017) - RBN, CPP, IGR, PVCS

Good morning!
I'm holding the fort here today as Paul is traveling.
Cheers,
Graham
Robinson (LON:RBN)
Share price: 115p (-14%)
No. shares: 17.7m
Market cap: £20m
A significantly weaker result (pre-exceptionals) had been well-flagged - Paul discussed the trading statement here in January.
Revenue fell by 7% to £27.5 million and operating profit almost halved to £1.4 million, thanks both to a lower gross margin and higher costs.
Perhaps the shares are down by a further 14% today because of the cautious outlook statement:
The general economic conditions suggest another challenging year ahead with continued pressure on consumer product brands and the UK retail sector. Continued investment in both personnel and equipment are leading to significant additional expenditure in 2017, justified by new business, some of which is already coming on stream. We remain on track to deliver revenue growth in 2017.
Although it is difficult for companies to do so, I much prefer when they acknowledge that they are struggling to compete within their industry, rather than blaming macro conditions.
In this case, is it true that consumer product brands generally are under pressure? Or is it more likely that Robinson's packaging solutions simply haven't quite managed to differentiate themselves from the alternatives in recent times?
"Significant additional expenditure" is a sign that the company does feel the need to change, but of course is likely to impact profitability in the short term. Revenue growth is mentioned, but there is no explicit mention of any anticipated profitability growth for 2017.
My opinion
Despite the weak outlook, I can see a potential value investment here. Net tangible assets are £15.6 million.
Paul's previous report suggested that the value of surplus land might be some £10 million. According to today's statement:
The Group is currently working with partners to find prospective tenants, develop detailed plans and sell the sites. Proceeds from the eventual sales will be used to finance the expansion of the operations and reduce debt.
So the company could potentially pay off all of its £5.6 million borrowings and swing into a healthy net cash position.
So on balance, the £20 million valuation here strikes me as reasonably attractive, if you can make the assumption that earnings will at least stabilise from the current level. In saying that, bear in mind I am always heavily biased in favour of family businesses, and those which have illustrious histories. Robinson ticks both of these boxes!
CPPGroup (LON:CPP)
Share price: 13.125p (-13%)
No. shares: 858.7m
Market cap: £113m
Investors have been very unsure about what to make of CPP's prospects, as you can see from the Stocko chart below:
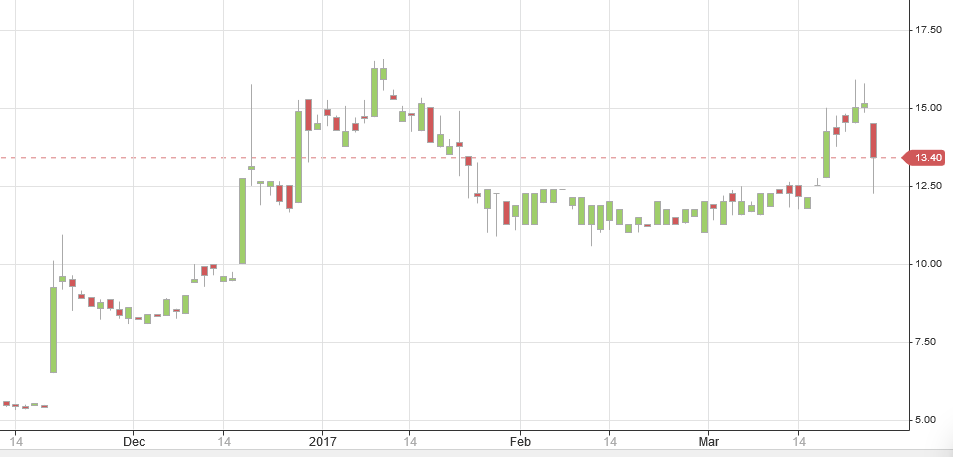
The company got into some financial and regulatory trouble a few years ago but appears to be on the mend.
it provides a range of related services - credit card protection, mobile insurance and passport assistance, both through its own channel and via business partners.
Today it reports growth in policy numbers for the first time in five years (up to 4.3 million from 3.8 million).
Revenue is down 4% on a continuing basis, however, as lower-value policies outside the UK are now driving the business strategy. International revenue is now 61% of the total (up from 44%), revenue in India more than doubling.
Profitability: only at breakeven, although the company claims to have generated £8.4 million on an underlying basis.
This looks like a fair claim, as £9.1 million in impairment and settlement costs are due to severing its relationship with an insurance software provider (this was widely reported in the insurance industry last September).
My opinion
It's a rather complicated situation, and I'm not surprised the share price has been so volatile.
Following on from the historic mis-selling scandal, CPP comprises a legacy book of business in natural decline, and a new book of growing (primarily international) business.
This gave it something of an artificial boost in 2016, as revenues fell by 10% on a constant currency basis (only 4% on a reported basis). But the international diversification does hopefully reduce the company's specific country risk going forward.
It has a new CEO (appointed May 2016), who worked at CPP from 2002-2014, and appears well-placed to drive a new business strategy.
Potentially cheap against underlying earnings and the growth in international revenues.
IG Design (LON:IGR)
Share price: 300.5p (+14%)
No. shares: 62.6m
Market cap: £188m
It's not difficult to see why the shares are up here today, with the following sub-heading to the RNS:
Record revenue, delivering EPS, profit and cash generation ahead of expectations
And then, under "Financial Milestones":
- Group revenues are now expected to achieve record levels - exceeding £300m;
- Profitability expected to be ahead of current market expectations;
- Cash generation is well ahead of previously expected levels and such that the Board's target of average annual leverage at less than 2.5x EBITDA will be achieved for the year ended 31 March 2017 - two years ahead of plan.
EPS is said to be "significantly ahead of market expectations", those expectations being in a 15.8-16.1p range based on November's upgraded forecasts.
So if we add 10% on to that range (presumably a 10% beat would be significant?), we get EPS of 17.5p, putting the shares on a PE ratio of 17x.
My opinion
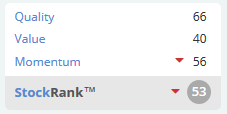
My initial review of the company chimes with the Stocko ranking: above-average quality, below-average value, so at a quantitative level it's hard to see what makes this stand out as a potential investment:
Given that the Board's target leverage has been achieved ahead of schedule, I'd expect them to be back on the acquisition trail again before too long.
So perhaps you could make an investment case based on the company's recent successful track record in acquisitions. Not one for me, though.
PV Crystalox Solar (LON:PVCS)
Share price: 21.125p (-2%)
No. shares: 160m
Market cap: £34m
Paul has previously suggested that the core operating business at PVCS may be worthless and that appears increasingly likely as the company warns today of "bleak prospects" for 2017, unless there is a recovery in market pricing.
But why would there be a recovery in pricing? There is said to be "massive over-capacity" of solar cells and wafers originating in China. What that says to me is: Chinese companies have figured out how to produce these items at much lower cost. And we should assume that this change is irreversible. If anything, we should expect pricing trends to continue lower, as technological and process improvements continue to increase supply.
Managed decline
Given that context, it sounds as though PVCS is taking the sad but necessary decisions needed to conserve shareholder value. Ingot production facilities will be closed at the two UK facilities in 2017.
Long-awaited judgement on its dispute with a customer is not expected before Q3 2017. It would not be surprising if this was delayed further, though the pay-off is likely to be highly material if PVCS is successful.
Cash-rich
Net cash rises by €16 million to €29 million (£25 million) thanks to a profitable result for the year despite the reduction in volumes, and much lower inventory levels.
Outlook
Wafer prices are said to be "well below production costs". Production has accordingly been reduced, but could be back on stream should pricing improve. As noted above, I think the base case assumption must be that this won't happen.
In the meanwhile, the company is focusing on the "niche low carbon footprint wafer market", and undertaking a Strategic Review which has been extended until the customer dispute has been settled.
It looks to me as if shareholders at the current level should do reasonably well: the market cap is mostly covered by net cash, there is a small but profitable niche activity which can still be pursued, and the award from the customer dispute could be worth "a multiple of the Group's market capitalisation" (it said that when the market cap was £22 million). Sounds like a value investment to me.
That's it from me today, have a good weekend everyone.
Best regards
Graham
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

22 comments
Third and last try! £Digital Barriers.
Did you mean Digital Barriers (LON:DGB) , as in EPIC code DGB ...prefaced by a £sign
Digital Barriers (LON:DGB) I don't think it needs an expert analysis, they just spend too much and earn too little. Directors lifestyle company IMHO.
http://www.stockopedia.com/share-prices/digital-barriers-LON:DGB/profit_loss/
Hi Graham/Paul
Would you have a look at £Digital Barrier's trading update on Friday (today) please? Obviously fallen short, but how do you interpret the stated contracts and their prospects please?
Thanks.
Hi Graham/Paul
Would tyou have a look at Digital Barriwer's trading update on Friday (today) please? Obviously fallen short, but how do you interpret the prospects please?
Thanks.
IG design: Your feelings on the company seem vastly different to Paul's in Janauary
@oxford,
On Jan 5th Paul said "My opinion - I think this is a good company, well managed, and performing well. The current valuation seems about right to me. However, we're in a bull market, so the price could yet rise further. It's been strangely volatile of late, I don't know why."
The price then was 256p.
Doesn't seem a vast difference to me?
For the avoidance of doubt, I do like IG Design (LON:IGR) - good management, and seems to be on a roll, of improving performance.
The latest trading update is clearly excellent, so the rise in share price looks fully justified.
Generally, on all stocks, Graham & I will have our own opinions, which might differ. We're not trying to form a consensus, or "house" view. Although we usually seem to broadly agree on most stocks.
Regards, Paul.
Robinson; I think th planning permission could well be worth more than the company.
Thanks for the suggestions...
Francis Dwan - that's the second request I've received on CPP so am looking at it now.
InvestedGeordie - that also looks like one I should cover, cheers
PVCS and SCT - if I can.
Regards
Graham
Not a company to get very excited about
Graham, would you mind to cover PV Crystalox Solar (LON:PVCS) which Paul has covered previously (and I hold)? The investment case is basically the value of net assets of about 22p plus the potential for a payout from a legal case of "several times market cap" (when the share price was about 13p/share). It seems reasonable to put a value of about 20p on the legal case so the share price should be 42p minus a discount for the wait (result of arbitration due in Q3) so surely the shares should be above 30p however you look at it. The company reported results yesterday saying mediation had failed and arbitration will now take place with results due in Q3. I would have though that is positive as there was always a possibility the mediation would fail, at least we now have certainty and hopefully a clear timeline. Yet for some reason the price has fallen from 24p to 21p. Do you or anyone else have any comments on this? Thanks very much.
Hi Dgold
This has happened before, in 2012. PV Crystalox Solar (LON:PVCS) won the legal case and received a big cash sum, but they never paid it out to shareholders. Rather they used it to subsidise the endless ongoing business losses until such times as the Chinese dumping issue might possibly have been resolved and hopefully prices of their products would recover. My concern at the time was that Chinese and/or other imports would still undercut PVCS, and/or their existing products would become superseded with newer & cheaper technology, requiring more R&D. Basically I did not trust them to use the funds better than I could, so without a special distribution of the cash pile I sold out.
Out of interest, I bought in at 4p and sold at 7.52p. Today’s price is 20.83p. So maybe I should have held! In any case my own view is I'm not certain it qualifies as an investment, so much as a punt.
Best of luck anyway!
Thanks for your comment. I do feel though that this time is different as the company has more or less said openly (the way I understand it anyway) that it will close down and is just waiting for the result of this legal case before it finalises its review of the company - sounds like it thinks it might be more successful with the claim it if continues to be nominally still in business.
Hi dg.
I hold PV Crystalox Solar (LON:PVCS) as a punt on the litigation settlement. I think the drift this week after the results is possibly a combination of disappointment that the case seems to be going the distance through the courts (more expense and delay) and a bit of impatience by punters who've made a bit of cash from the doubling of the share price in the past 6 months and who are selling out and moving on to the next GRQS.
In addition, courts have a habit of being a law unto themselves (no pun intended) and I think there is still the risk of the dispute ruling going against the company. I did try and do a bit more digging a few months back to ascertain the identity of the litigation counter party and with the input from some others on the board came up with a short list of candidates but nothing concrete. I found this a bit unusual in that litigants will often rehearse their case in public but not a peep so far as I can ascertain. So far, all we seem to have is the company's assurance that they have a watertight claim without the benefit of hearing what the other side thinks. One concern arising was that the case is being heard in a German court and I recall one of the possible counter parties was an offshoot of a big German corporate (Siemens, sorry can't recall?) and there is always scope for the additional risk of partial due process when playing away from home.
I continue to hold for now.
Best,
Gus.
Hi Gus
PVCS came up on my radar today price/volume rise, I would value your current view.
thanks
Ken
Hi Ken.
In the middle of the Australian outback at the moment so not paying too much attention to be honest. Thursday's RNS suggests PV Crystalox Solar (LON:PVCS) have streamlined their limited ongoing options and the level of the cash balance in the company (higher than expected I think) but the big potential payday remains the ongoing litigation case. No news on that so far as I can tell.
Gus.
INTREPID !
Would be interested in your take on Softcats results a few days back we had Paul's view's but I know you follow larger cap stuff also and its a popular one with private investors.
Cheers
Andy
Really appreciate it if you could cover the CPP full year results out this morning.
I'd be keen to see you cover IGR if you have time, Graham. Many thanks
Thanks Graham. I'd also be interested in IGR.
The company doesn't show up that well on the Stockopedia metrics (Ranks and Screens) maybe because of the historically high debt levels (net gearing was over 100%) but it has shown consistent profits growth. And today's results report forecast beating growth and a significant reduction in debt levels. Total return on this share (share price growth plus dividends) have also been excellent - Total return has been 57% per annum over three years and 40% per annum over five years.
So any insights would be very welcome
Julian