Small Cap Value Report (24 Nov 2016) - BLV, LTHM, MTC

Good morning!
Apologies for there being no report yesterday, I was under the weather so had a sick day. I know the service from me is a little unreliable, but it's still pretty good coverage considering it's just one person working all year round.
Plus I don't think anyone is complaining, considering the series of big winners we've had here (e.g. BOO, AVS, LVD), in what is turning out to be a blockbuster year. My broker even quipped that if I find any more takeovers, the FCA will probably come knocking. Still, when you have a portfolio of 40 value/GARP shares, there do tend to be plenty of takeover bids.
There's a very clear trend now of overseas (esp. American) companies buying up cheap UK companies, since sterling weakened. Let's hope there are lots more!
Letting agents
The Autumn Statement earlier this week has put the cat amongst the pigeons for letting agents, as the Government is proposing to ban fees to tenants. Although it should be noted that proposals like this are often watered-down, or dropped altogether, during the consultation period. No doubt lobbyists will be paid handsomely to nobble the proposals.
I've been sounding out opinion on Twitter, and it seems mixed. Some people think that landlords will just jack up rents to recoup their additional costs. My view is that, even if that is the case, it's still a much better idea to have the landlord paying the letting agent, since the agent works for them. Also, there's greater transparency with no fees for tenants - the rent is transparent, but often the fees are not.
I rent a flat in Hove, and was recently appalled at being charged £70+VAT just for a one year renewal document. This would have take all of 5 minutes for the agent to prepare. I texted my landlady and suggested we draw up the document ourselves next time. She agreed, as she had also had to pay £70. So that's £140 the agent earned from a few minutes work, and hitting a few buttons on her keyboard. As I quipped to my landlady, "we're in the wrong game!". She laughed, and said that she's just been saying the same thing to her mother-in-law.
Belvoir Lettings (LON:BLV) has issued an interesting RNS on this matter today, saying;
At this stage, Belvoir cannot fully predict the likely financial impact on the results for the year ended December 2017 and beyond. Based on the Group's experience following a similar decision in Scotland in 2012, however, the Board anticipates that mitigating action should be possible over time and indeed it should be noted that no franchisees were lost in Scotland as a consequence.
The Board believes that less than 10% of the income derived by franchisees is from fees to tenants and, due to the broader revenue streams to the Group, the impact on total Group gross profit is anticipated to be less than 8%. The impact may well be far greater for many of the large number of independent letting agents.
Whilst this may sound reassuring, I don't see it this way. Lettings agents are largely fixed costs businesses. So losing 8-10% of their income, which is 100% profit, is likely to have a devastating impact on the bottom line. Over time though, as noted, they'll presumably be able to pass on the additional costs to landlords.
Countrywide (LON:CWD) also puts out an update today, which points to slowing residential property transactions;
As expected when we reported our Interim results, transactional activity in the residential property market has remained challenged.
A combination of changes in stamp duty and the EU referendum in June means transaction levels are currently running significantly below 2015.
Bank of England mortgage approvals in Q3 2016 were 12% below last year. We now expect transaction volumes for 2016 to be 6% down on 2015 and while too early to say definitively, it is likely that the level of market transactions in 2017 will be lower than 2016.
So with sales volumes down, and now lettings fees to tenants likely to be scrapped, it looks like estate agents are going to have a lean time going forwards. There's additional pressure from new entrants in the online space, offering a much cheaper (although arguable quality) service.
I chuckled at the Dire Straits song reference from Peel Hunt today, who gave this clever & amusing title to their latest note on Countrywide - "Money for nothin' and checks for free". It does indeed look as if estate agents are in dire straits.
Speaking to a couple of friends who are very experienced property magnates, they both told me that the mid to upper end residential sales market in London is absolutely dead. Therefore they see Foxtons (LON:FOXT) as facing a very nasty outlook. For that reason, I closed my long on it, and went short.
Countrywide also made this interesting comment about an improvement in supply of rented housing easing the upward pressure on rents;
The lettings market was affected by the rush to beat the changes in stamp duty at the end of Q1, resulting in a larger than usual supply of rental properties.
Stock has increased more than tenant numbers, meaning more choice for tenants slowing rental growth, with rents falling in some areas.
Overall though tenant numbers have increased slightly compared to last year and we expect the slowdown in the sales market to support the growth in the size of the rental market in the medium term.
Whether that's a temporary factor or not, who knows?
Clearly something has to be done about the chaotic state of UK housing. It's ridiculous in the South East anyway - rents are far too high for most people, and availability is a big problem. Yet we have all these empty flats, owned by speculators. What a crazy situation.
Overall then, with estate agents facing 2 headwinds, I'll be avoiding buying any of them, and may open some new shorts in this sector. I've never understood why estate agents are so reviled as people. Personally I've chosen good ones in the past, and had excellent service from them. In my view estate agents are a bit like PR people - usually very pleasant, but take most of what they say with a pinch of salt!
James Latham (LON:LTHM)
Share price: 700p (up 5.6% today)
No. shares: 19.6m
Market cap: £137.2m
Half year results for the 6 months to 30 Sep 2016 - these figures look good to me. I note from the StockReport that broker estimates are for a fall of about 11% in EPS this year. In the past brokers have been too pessimistic about this company, and it looks as if that may be the case for y/e 31 Mar 2017 as well.
From what I can make out, this company seems to mainly be a distributor for imported wood products. So forex is a key issue for it - weaker sterling means higher cost prices. Judging from these interim figures, it seems that Lathams has been able to pass on the higher prices to customers.
Although it sounds to me as if the impact on margins has possibly been deferred somewhat (maybe through forex hedging, although this is not specifically mentioned in today's RNS, it seems to be implied from the comments below);
Management information shows growing revenue for October and the first half of November, at slightly lower margins.
The weakness of sterling, whilst increasing prices, could put pressure on margins in the coming months.
Market conditions continue to be difficult in some areas, while improving in others. We are in a good position with our wide range of customers and we are trading comfortably in line with market expectations.
We are progressing with our plans to relocate our two oldest depots. Construction work has started on the new Yate site and terms have been agreed for the new Wigston site, subject to planning.
Given what the company says above, it's perhaps best to be a little cautious.
Valuation - going by the broker consensus of 47.1p EPS for this year, the PER is 14.9.
That may not look cheap but as I always say when reporting on this company, investors are also getting an "inefficient" balance sheet, stuffed with surplus working capital.
Current assets are £89.2m (including £16.1m cash), but current liabilities are only £27.3, which is a current ratio of 3.27 - extremely healthy. If you reset that to say 1.3, which would be a perfectly acceptable position, then theoretically that implies there is £53.7m in excess working capital - i.e. liquid assets. That's a big chunk of the £137.2m market cap. This is dormant value - at some point, something might happen to unlock that value. Or it may not. However, it loads the dice in your favour.
Pension deficit - it's not all plain sailing though. As you would expect, the deficit has shot up, more than doubling from when last reported, to £23.2m. This will probably have since reduced, due to bond yields rising recently from extreme lows around 30 Sep 2016.
Dividends - there's a well-covered divi here, yielding c.2.5%. Not madly exciting, but it looks very safe, due to strong earnings cover, and a balance sheet stuffed with cash.
My opinion - it's long been a favourite company of mine, but I found it too illiquid to buy, so don't hold any. With a big housebuilding programme being required for many years to come, I imagine Lathams should be well-placed to benefit. It's got a fabulous balance sheet, and seems very well managed.
Bear in mind that margins may come under pressure in future, but so far the company seems to be coping absolutely fine.
Mothercare (LON:MTC)
Share price: 105p (down 5.8% today)
No. shares: 170.9m
Market cap: £179.4m
Interim results - 28 weeks to 8 Oct 2016 - a strange 28 week reporting period, although the prior year comparatives are also 28 weeks (as opposed to the more normal 26 weeks), so they are comparable.
This is a difficult company to analyse, as there are lots of moving parts, and it's now into the 2nd year of a restructuring which, so far seems to have just steadied the ship, as opposed to delivering good results. This has been reflected in a poor share price performance, which now has little recovery potential priced in, as hopes for recovery dissipated.
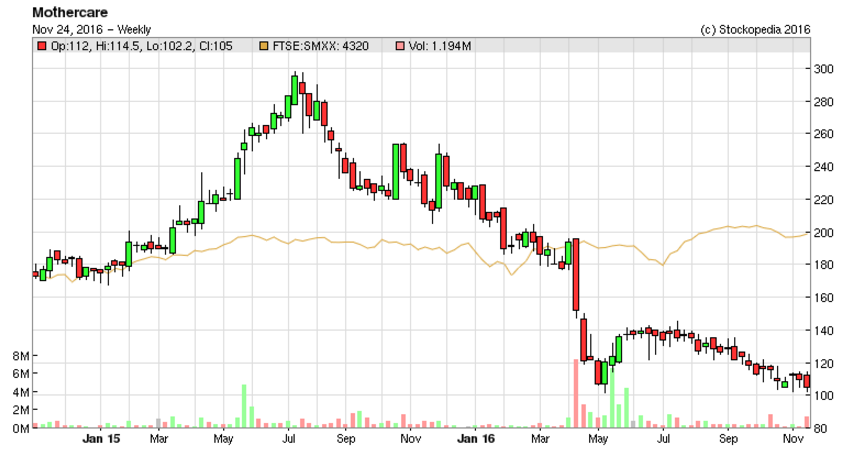
You would clearly have to be quite brave to buy this share, given this unnerving chart.
Today's drop in share price isn't encouraging either - if investors don't like a share on results day, then that could indicate more selling to come.
H1 results - the UK business is still a problem, generating a £8.8m underlying loss on turnover of £231.1m - so still looking a pretty marginal operation. Although better performance is expected in H2.
International is really the core business. It generated a £20.8m underlying profit in H1, on international revenues of £405.6m. That looks a reasonably OK performance - profit was down £4.1m on last year's H1.
I note from the narrative that forex hedging seems to have blunted the improvement in profitability which should flow through from sterling's weakness. So that could provide potential upside to future results.
There are more exceptionals and "non-underlying" charges, of £6.7m.
Digital sales - I nearly fell off my chair when reading that 40% of UK sales are now digital. However, this is not really true. The narrative later points out that 44% of digital sales are actually from customers using Mothercare's iPads in store! So that's clearly not digital sales at all, it's just that a customer is happening to use an iPad whilst in the store.
Broker downgrades - Peel Hunt has today cut their EPS forecast for this year from 10.7p to 9.2p. Although some of the reason for under-performance in H1 is temporary - e.g. the 8 week period of disruption in the UK business, due to a warehouse reorganisation.
Store refits - c.60% of UK stores are now refitted. So it's all the more worrying that the UK operation is still loss-making.
Outlook comments - sound alright. Here's an excerpt;
"Finally, we are making good progress with the reorganisation and focus within our International business. While sales are still volatile across the globe, many of our markets have now returned to growth.
We are putting retail space down and exporting our learnings and good practice from the UK into International online, which has grown by +46% in local currency.
"While conditions in the first half have been challenging, the second half has started in line with our plans and the business is well prepared for the important peak season. We expect to make further progress in the second half which will partially compensate for the effect of the headwinds experienced in H1.
Dividends - it's not paying any at the moment.
Balance sheet - is dominated by the pension deficit, which has ballooned for the reasons we're familiar with - ultra-low bond yields makes the liabilities much bigger. The £106.5m deficit is worrying.
Other than that, the rest of the balance sheet looks OK-ish. There's a bit of bank debt, but not at alarming levels.
My opinion - I'm on the fence on this one. It's tempting to pick up a few for a future improvement in performance. There again, the UK business seems to be going nowhere. There must be so much competition online these days.
Forex movements are likely to hurt the UK business, but benefit translation of overseas earnings, once forex hedging has expired.
At some point this share could make a decent investment. I'm just not convinced this is the right time, but who knows? So overall, I'm probably neutral on it right now.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

55 comments
MTC I emailed them 3 years ago and said they should put chairs in the shops. They did not. When my partner was heavily pregnent and we went to mothercare the was no where to sit so we left before buying all we wanted to. Obvious to put chairs in and what pregnent women drinks coffee?
Craig
Regarding my AXS Accsys Technologies comment earlier, here's the link to the Interim Results and webcast:
https://www.accsysplc.com/investor-relations/financials/
~
Paul, the standard of your analysis is excellent. I've made money on Boohoo & Avesco, although selling out of the latter too early.
I would much rather read high quality analysis, which you only write when you are fit & there is something you see to be worth writing.
That beats subscribing to some magazine or newspaper where there is more volume and less quality, since the journalists have to fill so much paper every day.
Paul
Keep up the good work. Thanks for higlighting the Countrywide trading statement, the decline in conveyancing (not just in London) was surpring to me. Many home improvement related companies could be affected by this - I need to look at my portfolio again to check my exposure. There seems to be a marked difference between the New Build market for homes (still robust) and the secondary market.
Paul, the fact that when I log in and don't find a report from you I feel lost, disappointed, for me says it all. Lovely Lovely thingy above is so off, someone at Stockopedia should note him and refuse his subscription renewal !! :) I have benefited considerably from Boohoo, Avesco and Lavendon, and I am pretty certain I wouldn't have if not for you. Like you I am an FCA so can "critically" I think, appreciate your observation and commentary. So apart from the above I have used your comments insights and observations together with other research and the stock rank system to guide my general investments. I took a trip down memory lane yesterday and my SIPP is up 78.7 % since October 2013. Now I am going to take a little credit for that BUT your observations and commentary has provided me with parameters and guidance, almost rules to use and add to my own intellectual research. That sort of gain in three years at my age is literally life changing. To be direct I will now be able, if I chose, to retire earlier and certainly far more comfortably then perhaps I would have. So to end, you bloody well have a busy or duvet day when ever you want :)
Hi Tanglands,
Many thanks for your kind comment!
Just to correct one point though. As I've mentioned in the past whenever this question has been raised, I'm not an FCA qualified accountant, because I flunked my finals exams in 1993.
Although having subsequently run a finance department for 8 years, peaking at 25 people, am regarded as QBE (qualified by experience).
Anyway, I've never done anything the conventional way, so the lack of a specific bit of paper hasn't ever held me back on anything! In fact I think it's been an advantage, because you have to always excel on your own merits if you don't have a formal qualification to fall back on.
I've seen far too many mediocre but studious people pass accounting qualifications, but be totally useless in the real, entrepreneurial world of commerce.
Regards, Paul.
Looking at the VCP H1 report, it looked very positive, with profit doubling, debt reducing and a promising outlook for the rest of the finacial year. I could see any major negatives, yet the share price didnt move at all following the release of the report...? Anyone know why?
Hi Reubencash207,
I recently had a meeting with Geoff Wilding of Victoria (LON:VCP) and we covered a lot of ground in a 1 hour Q&A.
I came away tremendously impressed. He seems to have worked miracles with a disciplined & effective buy & build there. Am pretty sure I did a write-up of our meeting here. Let me have a rummage. Yes, found it - here is the link.
I should also disclose that more recently, I've picked up a bit of stock in VCP personally.
Interim results are due out soon, so I'll comment on those figures, and reserve the right to pick up more stock if I like the numbers.
Regards, Paul.
Paul,
Victoria (LON:VCP) Interim's out last Friday. Would be interested in your comments if a slow news day today.
Creightons (LON:CRL) (I hold) put out what looks to me like very good half year results yesterday, but appears to have generated no comment. Underlying eps (there was a major disposal last year) appears to have more than doubled, with a mixture of both organic and result-of-acquisition profit increase.
Has anyone got any bear points on this stock before I'm tempted to top up a bit? I guess lack of dividend is one - I like to see at least a nominal dividend even from growth stocks as an indication that management realise that ultimately their purpose is to return cash to shareholders and not just themselves.
Too small / illiquid for me, but apart from that ticks all of my boxes
I also have a small holding in Creighton, in the hope any measurable success in its export markets would transform the company. It has roughly doubled over the last year so probably the result is in the price. It's very small so I doubt the results will generate a rapid response on the back of analysts upping target price and institutional buying. I was a bit sceptical when I bought but I am now a fan, it could easily double and double again.
I hold Creightons (LON:CRL) in reasonable size , I think they'd have been on course to pay a dividend if they hadn't done a very cute deal to buy a competitor's assets & customers out of administration. That deal has paid off in style but it meant that working capital went up substantially and they conservatively put in place a £600k term loan to deal with that.
Overall I can see very few more compelling growth stories at such a low valuation.
Cheers
Has anyone got any bear points on this stock before I'm tempted to top up a bit?
Well, releasing a RNS results announcement at 10 to 3 on a Wednesday afternoon is a pretty big black mark IMHO. Why can't they arrange this at 7am like everyone else? Is there any good reason for management doing this other than not giving a stuff about other shareholders?
All the best, Si
Good Point Si
In fairness they'd pre announced the T/O increase a few weeks ago to enable those of us with a calculator to add to our holding and await the good news re profit which duly arrived.!
problems for me, first is MCap is below £10, second the spread is very wide. I used to invest in a few small companies but after nearly getting trapped I decided to avoid them in the future. Ones I nearly came unstuck with were Elektron Technology (LON:EKT), Universe (LON:UNG) and Aukett Swanke (LON:AUK), problem is with a small fall in share price these types of shares can be like value traps.
Apart from that I can't see any obvious red flags. I will add to my watchlist.
Hi ISAllowance Re Creightons (LON:CRL) Yes I think the management is shooting itself in the foot by releasing such sparkling results late afternoon. I certainly missed it until you pointed out the RNS.
Having analysed it last night, there is little to fault and a lot to like. The only comment I would make is that the cash flow at this interim stage is negative. But this is a flea bite when you consider all the other positive factors. In summary, double digit growth in sales and eps, PE below 8 , EV/ EBITDA around 6 and P/S 0.35 with no debt.
I bought this morning.
No strong opinion on the letting fees as I don't really know enough about the sector/area but if these fees are beyond reasonable (seems they are), then what about:
Airlines charging £30-100 for a customer to type their new name into a webpage following marriage?
Home Office charging £70 for forms that are printed and sent through the post with virtually zero input from the Home Office
Building Companies allowed to sell houses leasehold with annual ground rent increases that would shame Wonga
I'm sure there are many other examples.
Any thoughts on AXS Accsys Technologies please Paul.
I think something people are missing with regards to agents potentially shifting their fees from tenants to landlords is that landlords do already pay fees themselves when a new tenant signs up. I just had a new tenant move into one of my properties today and I had to pay £470 in up front fees. When you add onto that the management fees @ 10%, that means I already run the first month of any tenancy at a loss (before even taking into account any mortgage payments where the properties are geared). If we're then stung for £200-300 in fees that normally would be charged to the tenant then we're looking at month 3 before we start actually turning a profit then I think its quite unfair on landlords. Especially with the government already hammering us on multiple fronts (mortgage relief removal, stamp duty increase etc...)
Not that I agree with the amount of fees tenants are currently charged as yes, they are marked up ridiculously by agents in many cases (as are landlord fees). I remember a time when our agents tried to charge us £25 a time just to provide a printed monthly rental statement. We still get charged £50 for a contract renewal (i.e. printing out a new contract and getting the tenant to sign it)
With regards to shares in estate agents, I suspect this to be a buying opportunity in the short to mid term because I think they will claw these costs back from landlords and will be no worse off. I personally wouldnt hold any traditional estate agents longer term as I think its a sector that is gradually moving away from traditional high street set ups and towards online providers.
I'm a landlord and I think the admin fees they charge tenants are outrageous. Particularly because I feel I have already paid for the agent to do that job and they are ripping off my customer/client which could impact my business. It will leave a bad taste in the tenants mouth and get the relationship off to a bad start. I think they have got so high because there is very limited price competition - i.e. the tenant cannot choose a different agent to complete the administration for the flat they have chosen, By the time they have viewed lots of flats, chosen one they like, gone through screening etc. they are begrudgingly willing to pay what ever they are asked to, so not to loose the property. Ensuring the landlord foots the full bill so it is visible when deciding which agent to use will mean that this 'admin fee' will be price competitive once more.
It also gives agents an incentive to churn tenants.
"...we'd all still be down a mine working for Lord Blimp."
Really? that's like me saying this change will end up with us all enjoying the life of North Korea.
What I fear may happen is this and other recent changes, adverse to the landlord, will gradually reduce the amount of rental property on the market to the detriment of renters as much as landlords.
I am not a landlord by the way.
Maximum fee I paid was £1000 (passed to my company in relocation expenses). Tenants choose houses, landlords choose agents. Agent fees belong to the landlord...
As ever satire gets it:
http://www.thedailymash.co.uk/news/business/this-is-communism-say-letting-agents-20161123117735
What an unpleasant post from NastyNastyHorrible above. Keep up the good work, Paul, it is much appreciated by most of us.
... being charged £70+VAT just for a one year renewal document...
Assuming that your agreement is an Assured Shorthold Agreement under the Housing Act and that no material changes made to the terms, sadly, you (and your Landlady) have been conned.
An Assured Shorthold Tenancy (AST) automatically morphs into a Statutory Periodic Tenancy at the end of the AST initial period. There is no documentation involved in this process. Your notice period automatically becomes equivalent to your rental frequency (1 month if you pay monthly, 3 months if you payquarterly,. etc) and importantly, the agent does not need to do anything and no documentation is required. The agreement can go on for as long as you and your landlady want it to and you don't need to pay a penny toward documentation!
Paul
No need to apologise. This (your column) is the best investment resource for PI's (professional managers?) on the internet. If you retire I would probably have sell up and buy an index tracker!
I hold Boohoo.Com (LON:BOO) and Avesco (LON:AVS).
KR
Michael
Hear hear to Paul. What you do you do you do extremely well IMHO. I am the wiser for following your column thought not always richer because at times I have not followed your conclusions!
Naturally you do change your opinion from time to time, sometimes without explanation. Re £STAFF I can remember when you were extremely critical of the model, and I followed you and sold, I think immediately before the election which the Conservatives won against the odds. Then surprise, surprise they suiddenly became a long for you, without further comment on low pay etc. It was good to hear the recent interview. As the CEO rather eloquently put it, they work very efficiently in a tough environment - the food industry..
Actually the villains of the piece are not the employers, or even the retailers but we, the consumers who demand food at very low prices, with no concern for what the producer or the intermediary worker receives.....and most of the time most of us have the gall to complain abough high food prices! We often buy rubbish without thinking what are the food values of the ingredients in say a £1 prepared meal? I say, if you think food is dear here, go to the happiest place on earth, Copenhagen / Denmark and see what you have to pay for food there!
But going back to my original comment, and your change of stance, a girl can change her mind cant she, especially when she learns more about the company? (you and me both). Pity we didnt sell a year ago, isnt it? Hope that the factors holding back the SP now will gradually ease in th cmpany's favour. I have confidence that the job will continue to need to be done - in both the general service and back to work sectors of their business, and that they are cery well placed to succeed in both.
Naturally you do change your opinion from time to time, sometimes without explanation. Re £STAFF I can remember when you were extremely critical of the model, and I followed you and sold, I think immediately before the election which the Conservatives won against the odds. Then surprise, surprise they suiddenly became a long for you, without further comment on low pay etc.
If the facts change, then I change my mind.
The key fact that changed with Staffline (LON:STAF) is that the share price halved from 1600p to 800p! So combined with strong results & a good outlook, it moved from being something I was nervous about (when it was expensive) to something I was prepared to back at a very much lower valuation.
Also I went to an analyst meeting, which I mentioned here, inviting other people to attend too, where management gave a very good account of what they were doing with the business.
I think you have a misconception that mine (or anyone else's) view on a share should somehow be set in stone. Nothing could be further from the truth. One weighs up the constantly changing facts & valuation, and based on assimilating all that information my view on shares will often change - based on my interpretation of the facts & figures. It sounds like you take a more emotional approach to markets, which is not a good thing.
Hope that clarifies.
Paul.
In reply to LovelyLovelyGorgeous, post #15
I think the difference you are not understanding is that you are paid for your time but Paul is not.
The letting market is ugly, in particular the fees charged to tenants and landlords. Notwithstanding that I still hate to see the government of a supposedly free society telling parties how they may, or may not, arrange their business affairs. Given almost all profitable enterprise that benefits our lives to such an extraordinary extent developed from parties working freely together, I fear the unforeseen long term effects of an increasingly interventionist government.
To a certain extent I would agree, but in the case of letting agents fees I think it is somewhat of an asymmetric market, and agree with their proposed abolition. A capital poor demographic (renters) is frequently put in the position of having to pay out hundreds of pounds by the actions of a capital rich demographic (landlords) over which they (the renters) have no control, typically the landlord moving back from abroad, deciding to sell up, etc. If there was a reasonable proportion of properties available let directly without fees I would say let it go, but IMHO there aren't - fees seem to be charged across the board and in this case I support the government intervention.
FWIW I am neither a tenant nor a landlord, and know members of both groups socially, so I have no particular axe to grind.
I fear the unforeseen long term effects of an increasingly interventionist government.
The problem is that it had got to the point where letting agents were taking the mickey. If they had kept their charges reasonable - i.e. based on the actual amount of work involved - then there would have been no need for the government to get step in.
I fear the unforeseen long term effects of an increasingly interventionist government.
An interventionist government is the only reason there are pensions, the NHS, roads, free education, etc. Left to its own devices we'd all still be down a mine working for Lord Blimp.
An excellent move imo re:landlord rip off fees - in what other field would a purchaser pay for the cost of setting up a contract - should be built into the rents and the fees taken from that.
And its naieve to think that just because a fee is banned in one form it will ultimately be bourne elsewhere - sometimes its lost altogether
I wonder how many bosses will be ok with staff calling in sick and saying that is unreasonable for them to have to work all year. I'd be asked to leave even though I do a good job, work 9 till 6 five days a week, commute for three hours total a day and have five weeks paid holiday.
Yes, yes, I know it is different here
Paul works 52 weeks a year with an agreement that he takes a duvet day when he sees fit. Snarky remarks from folk who have more conventional working arrangements seem spectacularly pointless, as is my response so I'll shut up and leave you to the joys of your 9 -5 slog
Good luck with your investments , if they do well you might be able to escape the rat race..
I wonder how many bosses will be ok with staff calling in sick and saying that is unreasonable for them to have to work all year. I'd be asked to leave even though I do a good job, work 9 till 6 five days a week, commute for three hours total a day and have five weeks paid holiday.
You forgot the bit about using your employer's internet connection and posting nonsense to blogs during work hours...
All the best, Si
@LovelyLovelyGorgeous I do think it would be a good thing if you could retract your comment above and apologise. It is really unnecessary and uncalled for. I see that you have been a member since early 2015 so you must realise what an AMAZING job Paul does (see the archive and for example and his involvement in the Profit Warning book which Stockopedia published this week).
I would suggest that you try writing 40,000+ words a month for several years, after analysing 100's of stocks and thousands of RNS's, and making extraordinary returns (see his fantasy portfolio [http://www.stockopedia.com/fantasy-funds/beam-me-up-scotty-4990/] which is showing an annualised return of around 50% since inception in early 2015) and then come back criticise.
In the mean time please show a little respect.
KR
PS
'and have five weeks paid holiday.'
Oh Irony! No duvet days there then :-)
Keep up the great work Paul.
I don't see LTHM going out of business any day soon. As its illiquid I am happy to have a small holding sitting on the side as a long term buy and hold rather than to trade it.
Ho Gorgeous
I used to have a crappy job, just like you. I resolved not to whinge about it, or gripe about how much better other people had it. Instead i packed it in and learned to live a cheaper life. If I had been LovelyLovelyGorgeous I would have tried to marry money instead, but unfortunately I am UglyUglyChubster. We can't have it all!
Thanks Paul for the latest comments on James Latham. It has been run by the Latham family since 1757 and I think it illustrates how family owners like to leave a large safety margin when a substantial part of their own wealth is tied up in the company. Long live inefficient balance sheets!
mother care lost a lot of reputation and allowed a load of people to enter the market. What mother wants to wander off to a store when they can just have it delivered, so old model trying to access the cutting edge of the new world.
Hi Paul, glad you are feeling better and thanks for all your insights! Should you find the time it would be great to hear your take on QXT. Thanks!
The underlying message from the estate agents is 'don't worry, we will squeeze the money out of someone, somehow'! And to be honest I believe they will. The London market is definitely cooling, but rentals are a growth area across the country, so letting agents should be safe enough from any fee waiver idea in the longer term. More worrying for some may be the spread of Universal Credit. This sees Housing Benefit no longer paid straight to the landlord/agent by the DSS, but given to the tenant, who is then expected to pay his own rent. In many marginal areas, and amongst certain classes, this is a recipe for disaster. Agents will really have to start doing their job, chasing rents. I would not like to be a buy-to-let landlord in the lower social sector. For the first time in my life I think it may be time to believe an estate agent: don't worry too much for now!
Paul, well done on your recent successes, sounds like you've had a good year. Interested to know whether there's a publication date in mind for your book?
Regards
Andrew
Paul, Agree with all the sentiments above. I have learned a lot from your blog- and you owe nobody any apologies. Thanks!
Hi Paul the idea that Landlords are going to reimburse Letting Agents for lost Tenants fees is ridiculous - They will either take them off LA and manage them themselves ( as I have done) or will use a cheaper letting agent/internet LA- Letting fees are in a downward spiral and this measure will merely increase the speed of it
Apologies, I meant to say 'quality write-ups daily' .
Hi Paul
Mentally its quite tiring I would imagine to do a blog, and it takes a fair bit of time to review RNS's and dig into related accounts etc. I think the fact we miss your reports is a testament to the quality of the blog. So hope you are feeling better.
Do you think you will have an interview with the CEO of Tracsis in the future? It would be quite interesting to hear your take on them.
Hope you are feeling better Paul. No need to apologise! A very belated thank you for your quality write ups regarding Avesco.
Regards, Ruth.
Hi Paul
Hope that you are feeling better today.
From my perspective I have nothing to complain about. I bought and have now sold AVS,BOO,ands LVD. In the cases of BOO and AVS I was in them from the your first report and have done particularly well. Have a feeling that I got out of BOO too soon. Sold at 117p but still almost a 5 bagger.
Thanks for a great service
BB
Paul
Just to say, please do not apologise for missing out reports on a few days. The quality and consistency of what you provide is what, I for one and I'm sure many others, value highly. I believe most of us on Stockopedia are investors rather than traders and we will be looking at our own holdings with diligence anyway. You need your breaks from the analysis and writing in order that you return refreshed and sharpened in mind and judgement. So, please take you days away without any feelings of guilt and enjoy them.
Regards
Howard
Certainly don't begrudge you a day off Paul, you deserve it after alerting us to BOO, AVS & LVD. RBG seems to be tipped a lot at the moment, but you heard it here first folks!
Hear Hear! I'd add MYSL to that list as well!
Have you stopped your Charity things Paul? Some of us probably owe your a drink or two but failing that a contribution to some of your fave charities is probably due!