Small Cap Value Report (24 Oct 2016) - BEG, G4S, CML, MCB

Good afternoon!
Today's report will be updated throughout the afternoon, as I've got a few other things on today - including my latest CEO interview - of Ric Traynor, CEO of Begbies Traynor (LON:BEG) - actually to be 100% accurate, he's their Executive Chairman, not CEO. I'll be recording that interview at 2pm, so am preparing for it now. Will be published later this afternoon.
Note that Begbies Traynor (LON:BEG) issued its regular Red Flags Report this morning, which is surprisingly upbeat. It reports that financial distress amongst UK companies was down 6% in Q3. Listening to the daily television news, they seem to be constantly telling us how everything is going to hell in a handcart. So it's refreshing to get some proper data which actually says the opposite.
Mind you, we've not felt the impact of weaker sterling yet. Once prices rise significantly in the shops next year, then that could cast a dark shadow over the UK economy. Also, nothing has actually changed yet. We've only had the referendum vote, but nothing has changed as yet. Who knows what the future holds? Nobody does, it's all educated guesswork. Although we always seem to find a way of muddling through - individuals and companies are inherently adaptable.
Although a very interesting point was made by the CEO of Gear4Music (G4M) in a meeting I attended last week. They import a lot of product from China, either directly, or via UK distributors. He said that UK prices would not have to rise as much as some people feared. This is because the Chinese Yuan has depreciated about 7% against the dollar in the last year. This partly mitigates the weakness of sterling against the dollar. Also they can secure lower unit prices by placing a larger order - so they might increase inventories to secure cheaper pricing.
I've just checked the figures, to quantify this, and this is how much currencies have moved in the last year:
Sterling now buys 8.287 Chinese Yuan, compared with 9.73 a year ago = sterling depreciation of 17.4%
Sterling now buys 1.223 US dollars, compared with 1.535 a year ago = sterling depreciation of 25.5%
So based on those figures, the Chinese currency has absorbed about a third of the US dollar impact on sterling. These are still huge moves though, over just one year.
I see that G4M shares are continuing their remarkable re-rating, after excellent recent results & outlook. I love it when an overlooked share suddenly gets a double boost - from investors being prepared to pay a much higher earnings multiple for faster growth, and earnings estimates also being revised upwards. That's the perfect type of situation for a very rapid, and substantial gain. I just wish I could find more things like that!
To keep you going whilst I update today's report, here is a bonus report I wrote on Saturday, catching up on some companies that were overlooked in the last week.
On to today's other news.
Begbies Traynor (LON:BEG)
(I currently hold a long position in this share)
Here is the link for my completed audio interview conducted today with the Exec. Chairman of Begbies Traynor.
Next, I'm going to look at trading updates from;
CML Microsystems (LON:CML)
Share price: 395p (up 4.6% today)
No. shares: 17.0m
Market cap: £67.2m
Trading update - this company describes itself as;
CML Microsystems Plc, ("CML" or "the Group"), which designs, manufactures and markets mixed-signal and Radio Frequency (RF) semiconductors, primarily for global communication and solid state storage markets
There's a very clear trading update today, covering the half year to 30 Sep 2016;
The Group announces that its unaudited figures indicate that revenues for the half year will be circa £13m, including a two month contribution of product revenues from its acquisition of Sicomm of £0.4m.
Profit before tax is expected to be approximately £1.9m and
cash generation continues to be healthy.
As at 30 September 2016, the Group had net cash of over £11m, which includes the net effect of the cash element of the consideration paid for Sicomm and the cash balances within that business. The Group has no borrowings.
Net cash is material, at 16.4% of the market cap. I seem to recall this business also has some surplus freehold property, so it's very strong financially.
Other accounting points to note;
- Capitalisation of development spend is very large, so a key point to consider.
- There's a small pension deficit.
Comparing the above figures to interim results last year, I note the following;
- H1 2016/17 - revenues up from £11.0m last year to £13.0m, so a decent increase.
- Profit before tax last year H1 was £1.5m, and has risen to £1.9m - so a good increase there too.
- Net cash has fallen from £12.3m to £11.0m.
Outlook comments today sound upbeat;
"We're pleased with our first half performance. CML is focused on two highly niche industrial storage and communication markets where the quality and reliability of our technology sets us apart and makes us an integral part of our customers' products. The Group is seeing the benefits of our strong focus on R&D which remains a key part of our strategy as we continue to build for the future."
"The contribution from Sicomm to date has been pleasing, in line with our expectations and we look forward to the second half of the year with confidence."
My opinion - it sounds like the company is likely to meet or beat broker consensus for this year, which is 19.6p EPS. The PER is 20.2 based on a 395p share price. That may look expensive, but it's more reasonable when you factor in the property & cash on the balance sheet, so mid to high teens once those adjustments are made.
The valuation all depends on how the future pans out. I don't know anything about this sector, so can't really form a view on that. I wonder if this might be a takeover target at some point?
Overall, if you understand the sector, then this share might be an interesting one to research further. I quite like the numbers, so that's a good starting point. There's a reasonable divi too, currently yielding about 2%.
McBride (LON:MCB)
Share price: 190.75p
No. shares: 182.2m
Market cap: £347.5m
Trading update - it sounds as if the solid turnaround underway here is on track;
McBride plc, the leading European manufacturer and supplier of Co-manufactured and Private Label products for the Household and Personal Care market which today holds its 2016 Annual General Meeting, provides the following trading update for the period from 1 July 2016 to 30 September 2016.
The Group's first quarter financial performance has been an encouraging start to our new year.
Whilst Group revenues fell at constant currency and were 2.9% lower than last year (net of the impact from the customer reduction project), our margins and costs have continued the positive progress seen since the launch of our new strategy.
At this early stage of the year the Board is comfortable that the business remains on track to deliver its full year expectations, taking into consideration the many uncertain macro-economic factors ahead of us.
Falling revenues are not a problem, because MCB's revised strategy has been to intentionally drop off low margin business.
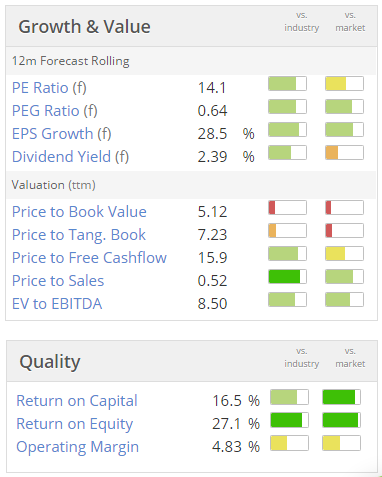
Valuation - nothing particularly jumps out at me from the usual Stockopedia graphics below. It looks priced about right, in my opinion;
That's me finished for today. See you in the morning!
Regards, Paul.
(usual disclaimers apply)
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

9 comments
Brexit
Companies across the EU would suffer more than double the hit from trade tariffs than their UK counterparts if Britain leaves Europe without a free trade deal, research from the right-of-centre thinktank Civitas says. It would cost EU businesses in the 27 remaining member states a total of some £12.9bn every year to export their goods into the UK if a deal is not reached with Europe and trade is conducted under World Trade Organisation rules, Civitas found. - Telegraph
http://www.digitallook.com/news/press-round-up-short-premium/monday-newspaper-round-up-barclays-deutsche-bank-bae-ppi-provisions--1778930.html
Tariffs on goods aren't the key issue for the UK.
It's the lack of any provisions for the continuation of service exports (where the UK has a huge trade surplus). There are no additional costs resulting from tariffs, the exports simply end without a deal. Along with a fair chunk of the tax base.
At a constant that would be £470million per country although I accept the more industrial nations would suffer more. We as one country export £5.7 billion to the eu.
Who would suffer the most. I voted brexit by the way.
Interesting point about the yuan-pound ratio.
Here's a question for economists out there: if prior to June 24th the country owed a trillion pounds, what's the impact of sterling devaluation on that debt?
There is no direct devaluation effect on the stock of debt of the UK state as it's all denominated in sterling. The capital value is constant in sterling terms.
Indirectly the increased inflation tends to drive up the interest rate on the debt as its rolled over and on index linked gilts. Unless the BoE follows Japan's example and holds the interest rate on gilts constant via QE for non indexed debt.
Paul
Thanks for your mention G4M. I see another small sell by Chairman But is that half his holding?Maybe £4 is the high for now.
Hi Stockandy,
Yes indeed, I saw that the Chairman of £G4M has sold some shares. He's cashed in about 44% of his fairly small shareholding:
On 24 October 2016, the board of Gear4music (Holdings) plc ("Gear4music" or "the Company") was informed that Ken Ford, Chairman, sold 15,971 shares. The beneficial holdings of Mr Ford now stand at 20,000 shares, representing 0.1% of the Company's issued share capital. The above transaction took place on 24 October 2016 at 408 pence per share.
I think 400p is about the right price for this share at the moment. That's also the (roughly) price target of both brokers who cover it - Panmures, and Edisons.
Having said that, personally I'm not selling any of my shares in it - as I think it's exactly the type of share that is likely to run to an over-valuation. Also, the growth is so spectacular (73% in H1, all organic), and with much more to come I think, that this is one share to just sit tight on - almost a question of ignoring the share price for a while, as I think long term holders here are likely to do very well.
Obviously, as always, if rapid growth stalled, then it could fall.
Regards, Paul.
Hi Paul,
I missed your Saturday report until I saw your mention of it on Twitter because it doesn't show up in the listing at
http://www.stockopedia.com/columns/paul-scotts-uk-small-cap-value-report-1/
Hi John,
Sorry about that. I've just checked, and it was my fault - I didn't set the article's tags correctly.
Have now fixed it. Thanks for flagging up.
Regards, Paul.